Showing posts with label $BA. Show all posts

Sunday, 29 April 2018

Week to Apr 27th


Monday April 23
After Friday’s fade non-US equities turned up again today, although this was largely due to currency weakness. Data for the day was rather mixed. SPX had the flattest day for a long time, up 0.3 points (0.01%) on the day, as US 10-year bond yields approached 3%, closing up 2bp at 2.98%, making a total of 17bp in the last four trading days. Even the GOOGL beat on earnings and revenue had little effect, a small after-hours spike that faded quickly.

USD was strong with DXY putting on 0.74% on the day, the best day this month. All currencies were down in dollar terms, as was Gold. Oil on the other hand was very volatile, moving in a 2.72% range to close 1.15% up on the day, its highest close this week.

Tuesday April 24
Today the US10Y finally hit 3%. This psychological roundpoint was generally given as the reason for a sharp market fade. SPX was down 1.72%, and tech lead the rout, with NDX down 2.57%. DAX, FTSE and NKY were also down in line. The Tuesday Turnaround was also seen in EUR, GBP, CAD and Gold, which advanced slightly, however AUD and JPY were very slightly down. CAT beat estimates and rose 4.62% pre-market, but then fell with the rest of the DJIA and ended up 6.2% down on the day. Oil had a bad day after Trump made remarks about Iran, giving up all previous days gains and then some, to close 1.78% down.
Wednesday April 25
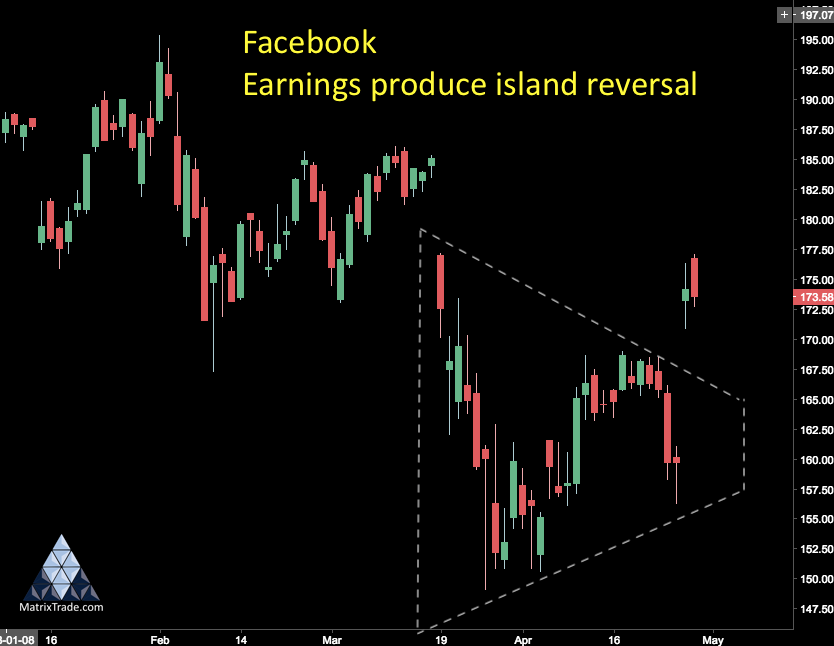
Another reversal on Wednesday as markets recovered some of Tuesday’s losses, despite yields advancing further into 3% territory (closing up 4bp at 3.03%). NKY recovered all the previous day’s fall, thanks to a weaker yen. It was good day for USD. DXY advanced 0.52% and all currencies and Gold faded against it. Oil climbed again. BA and FB beat on earnings and revenue. The aircraft giant put on 4.19%. Facebook’s report was after the bell and it gapped up 8.47% on Thursday, leaving an island reversal.

Thursday April 26
As yields retreated from 3% (down 3.7bp on the day), equities continued to climb back up, with SPX and DAX recovering most of Tuesday’s losses, and NKY and FTSE going even further, after US Jobless Claims and Durable Goods beats at 1230. The four stocks we mentioned last week comprising nearly a quarter of NDX all duly delivered on earnings, pushing the tech index up by 100 points in after-hours trading.

The ECB held rates as expected, but cautious remarks from President Draghi sent EUR southward, pulling back over a cent. This was against a backdrop of further dollar advance as DXY added another 0.4%, and all currencies and Gold retreated further. GBP has of course been falling since BoE Governor Carney expressed doubts about a May rate hike last week. Oil was more or less flat on the day (down 0.2% at $68.19).

Friday April 27
To quote two pieces of T.S. Eliot, “April is the cruellest month” is probably not true this year, but his description of the world’s end can also be said for the end of this week (and nearly the month), that it ended “not with a bang but a whimper”. Unlike many previous Fridays, there was no sell off nor was there a ramp, and with little volatility, equities and Oil were flat on the day. The only exception was FTSE which directly reacted to GBP. NDX gave up the 100-point overnight boost, with even mighty AMZN giving up half its earnings spike.

Currencies were a little livelier. Although JPY hardly reacted to the BoJ rate decision, there was a strong reaction to the UK GDP miss at 0830. Sterling fell 1% on the day (making a fall of 4.18% in eight trading days), as hopes of a May rate hike further evaporated. This was against a background of a slightly retreating dollar despite the various US GDP/PCE beats (except for raw Q1 GDP). Gold and all the currencies were up, but yields continued south, down another 3bp. Even NZD posted the first green candle in nine trading days, despite first hitting a 2018 low.

Please note all figures and percentages given for daily movement on indices cover the entire cash and futures period in that day.


WEEKLY PRICE MOVEMENT

The dollar rebounded this week, and most currencies reversed their gains of the previous week. The kiwi receded most, so selling NZDUSD would have been the best forex trade. Indices were much flatter, with only NKY managing to move more than 1% on a weaker yen. Oil held onto last week’s stellar gains but didn’t move much further. The crypto-currency recovery continued strongly following last week’s gains, with once again ETH performing even more strongly than BTC.

Another strong week for the dollar, with DXY putting on 1.4%, its best week since the week after the Trump election, and at 91.53 its best level this year. All currencies gave up ground, and the best trade, like last week was to short NZDUSD. Indices were quiet this week, with only NKY moving more than 1%. Cryptocurrencies were also quiet as volatility continues to fall.

AUDUSD 0.7580 (-1.17%)
EURGBP 0.8797 (+0.38%)
EURUSD 1.2126 (-1.29%)
GBPUSD 1.3775 (-1.62%)
NZDUSD 0.7085 (-1.69%)
USDCAD 1.2827 (+0.58%)
USDJPY 109.02 (+1.28%)
DAX     12590 (+0.47%)
FTSE     7509 (+2.74%)
NIFTY   10692 (+1.21%)
NKY     22467 (+1.38%)
SPX    2670.7 (-0.01%)
GOLD  1323.25 (-0.94%)
OIL     67.96 (-0.09%)
BTCUSD   9022 (+2.02%)
ETHUSD 654.01 (+6.38%)

(Crypto prices are given as at 0000GMT Saturday, two hours after the other markets close.)


NEXT WEEK (all times are GMT)

This is the peak week of earnings, with 1492 companies reporting including all-important AAPL (as AMZN and GOOGL reported early last week. It is also packed with economic data (remember our calendar only reports medium and high volatility items), including the Fed Rate decision and NFP in the same week.

Monday April 30
Quite a few market closures today, China takes Labor Day early, and Japan, India and Hungary are closed for local holidays, so expect a quiet Asian session. The important news of the day is the German inflation print. DJIA component MCD (ranked #7 at 4.48%) reports before the bell.

Tuesday May 1
China takes an additional Labor Day today, along with most of Europe (but not the UK, who depoliticised the holiday some years ago to ‘Spring Bank Holiday’ and take it on the first Monday in May, ie next week. Trump’s infamous steel and aluminum tariffs come into force, except for exempted countries (Canada, EU and Australia are exempt). If NAFTA is not concluded by then (a strong likelihood), the Canada (and Mexico) exemptions are expected to continue. No surprises are expected from RBA Governor Lowe or BoC Governor Poloz, although Canadian GDP may cause a ripple. Otherwise the big news of the day is the AAPL earnings after the bell. Note the release is not usually immediate, but 25-30 minutes after the market closes to reduce AH volatility. SNAP and GILD also report then.

Wednesday May 2
Today is FOMC rate decision day, with a 93.3% expectation (per CME FedWatch) of a hold. Attention will therefore turn to the dot-plot and Chair Powell’s remarks. Expect USD positioning throughout the day. The ADP estimate is 200k, almost exactly the same as the NFP estimate of 198k. There are no other Fed speakers today, only hawkish Bundesbank President Weidmann. Cult stock TSLA reports after the bell.

Thursday May 3
Today is the peak day of the earnings season with 450 companies reporting, but only beleaguered camera maker GPRO is of any note. Today is the hiatus between FOMC and NFP so some volatility many ensue. ECB speakers are Hansson (07:00), Constancio (12:00) and Coeuré (13:30), although the speech by SNB President Jordan, a market we don’t normally cover, at 16:00 may be interesting now that EURCHF has finally recovered to its pre-Jan 2015 level. Poland and Japan are closed today.

Friday May 4
NFP is always important, but as always recently, the Average Hourly Earnings is the key to a June rate hike (or not). The YoY estimate of 2.7% is the same as last month’s actual print, whereas the MoM estimate is down to 0.2% (0.3% prev act). Any miss here could stall the dollar’s recent rally. Chinese giant (but not index member) BABA reports before the bell. CB speakers today: Dudley (hawkish, voter) at 16:00, Williams (hawkish, voter) at 19:00, Quarles (centrist, voter) at 21:30, and ECB (BuBa) Weidmann at 13:00. Japan is closed again today.


CALENDAR (all times are GMT). High volatility items are in bold

Mon Apr 30
00:00 EUR EcoFin Meeting (24h)
01:00 CNY China PMIs
02:00 AUD RBA's Governor Philip Lowe Speech
06:00 EUR Germany Retail Sales (MoM)
12:00 EUR Germany CPI (est 1.5% prev 1.5%)
12:30 USD PCE/Income/Spending
13:45 USD Chicago Purchasing Managers' Index
14:00 USD Pending Home Sales (MoM)
22:45 NZD Building Permits s.a. (MoM)
23:30 AUD AiG Performance of Mfg Index

Tue May 01
04:30 AUD RBA Rate Decision/Statement (est 1.5% hold)
08:30 GBP UK Markit Manufacturing PMI
08:30 GBP UK Mortgage Approvals
12:30 CAD Canada GDP
13:30 CAD Canada Markit Manufacturing PMI
14:00 USD ISM Manufacturing PMI/Prices Paid
14:00 NZD GDT Milk Index (time approx)
18:30 CAD BoC Governor Poloz Speech
20:30 WTI API Stock
22:45 NZD NZ Empl Change/Unemp/Participation/Labor cost

Wed May 02
01:45 CNY China Caixin Manufacturing PMI
07:00 EUR Non-monetary policy's ECB meeting
07:55 EUR Germany Markit Manufacturing PMI
08:00 EUR Eurozone Markit Manufacturing PMI
08:30 GBP UK PMI Construction
09:00 EUR Eurozone GDP s.a.
09:00 EUR Eurozone Unemployment Rate
12:15 USD US ADP Employment Change
14:30 WTI EIA Stock
15:30 EUR German Buba President Weidmann speech
18:00 USD Fed Rate Decision/Statement

Thu May 03
01:30 AUD Australia Building Permits (MoM)
01:30 AUD Australia Trade Balance/Imports/Exports
08:30 GBP UK Markit Services PMI
09:00 EUR Eurozone CPI (YoY)
12:00 EUR ECB Vice President Vitor Constancio speech
12:30 EUR ECB Coeuré Speech
12:30 USD Trade Balance
12:30 USD US Jobless Claims/Nonfarm Productivity/Labor Costs
12:30 CAD Canada International Merchandise Trade
13:45 USD US Markit Composite/Services PMI
14:00 USD US ISM Non-Manufacturing PMI/Factory Orders (MoM)

Fri May 04
01:30 AUD RBA Monetary Policy Statement
01:45 CNY Caixin China Services PMI
02:00 NZD RBNZ Inflation Expectations (QoQ)
07:55 EUR Germany Markit Services/Composite PMI
08:00 EUR Eurozone Markit Services/Composite PMI
12:30 USD US NFP/AHE/Unemployment/Participation
14:00 CAD Canada Ivey PMI
14:00 EUR Buba President Weidmann speech (time approx)
16:00 USD Fed William Dudley speech
17:00 WTI Baker Hughes US Oil Rig Count
19:00 USD FOMC Member Williams speech
21:30 USD Fed Quarles speech

This report is published every week as an email by MatrixTrade.com - you can sign up to receive it here.


Sunday, 4 March 2018

Week to Mar 2nd


The upbeat mood in equities that finished last week continued on Monday, and all major indices were up with SPX up 1.2% on they day, and nearly 10% from the low on February 9 and only 3.3% away from the previous all-time high. DXY was flat on the day, with a slight gain (0.1%) by EUR as ECB President Draghi’s remarks at 1400 reversed an earlier slide matched by slight dollar gains against the other major currencies (including ZAR, which appears to have topped for now). Gold did not follow USD, and was up a shade. Oil was similarly slightly (0.7$%) up, and US 10-year bond yields also had a quiet day, down 1bp. All in all, consistent direction but only small moves.

Tuesday was new Fed Chair Powell’s first major outing, at the semi-annual Humphrey-Hawkins testimony, and some observers will say he is jinxed. You will remember that the market endured its biggest pullback in over two years on the day he took up office, and now on his first public outing, markets turned down again to start a week of decline, not helped by the German CPI miss at 1300, Trade Balance and Durable Goods misses at 1330, and the forward-looking House Price Index miss at 1400. All equity markets saw a Turnaround Tuesday and gave up Monday’s gains and then some. Powell largely stuck to agenda of his predecessor, but the market viewed it as slightly hawkish and bond prices (inverse to yields) and Gold were sharply down (to a two-week low) after his remarks. This consistency of Gold moving with rather than against indices shows that the interest rate roadmap (and therefore US dollar value) is the key driver to the price, rather than its traditional safe haven function. USD was of course up, with DXY posting a 0.62% gain, and advanced against all currencies. Oil was done in line with US strength, even before the API Miss at 2130.

The pattern from the previous day largely continued on Wednesday as Powell gave further testimony to the Senate.  Indices carried on fading, after misses on China PMIs (0100) Eurozone CPI (1000) and US GDP Price Index (1330)  and the dollar rose again. The German unemployment beat at 0855 was ignored. Today of course there was also the effect of month-end rebalancing. SPX was actually up two hours before the US closing bell, and then faded 42 handles (1.53%) into the close. DJIA lost 411 points in the same period.  Other indices followed suit after early gains. The decline was exacerbated by a sell-off in energy stocks, following Oil’s 1.3% pullback after the EIA Stock miss at 1530. As we have said previously, Oil has started to react again to this important news print, and we also saw a spike down in CAD. It is good to see islands of classic intermarket activity in this sea of sentiment.

USD was up across the board, although Gold was flat on the day. GBP fell particularly hard after a poor reaction to the EU’s draft Brexit treaty, and a warning from EU negotiator Barnier that a transition deal was far from certain. Gold was flat on the day after the hard fall in the previous session. Yields did not follow USD, and pulled back 4bp on the day.

The new month opened on Thursday with President Trump’s announcement a tariff on imported steel (25%) and aluminum (10%). Producer stocks in those industries soared. However these stocks are absent from DJIA and have low weights in SPX, but stocks of consumers in these metals are heavily represented. Boeing (BA) is 9.67% of the DJIA and fell sharply, a total of 9.69% by the low of the following day. The result was a decline in stocks across the board, with SPX and DJIA falling over 1%, the first time in two years that this has happened on three consecutive days. The ISM PMI beat at 1500 caused a brief but not insignificant (1%) rally in SPX, but this faded quickly as the tariff news spread. DAX, also troubled by four problems; the German coalition vote, the Italian election, a sharp rise in EUR, and the effect of tariff on its auto sector (14.55% by weight) fell by 2%, and FTSE and NKY followed the trend.

The dollar rally ran out of steam on the protectionist news, and the day saw the greenback down against all currencies, even CAD, the largest supplier of US imported steel and aluminum. After initially touching a six-week high, DXY shed 0.47%, and Gold was up in line. Yields fell sharply on the news, dipping briefly below 2.8% for the first time in nearly a month. Oil continued to fall on the EIA (and earlier API) stock miss.

The equity indices stabilised on Friday. After a further dip during the Asian and European sessions, SPX defensive and technology stocks led a recovery in the US session. This resulted in a 1.1% gain for the day in NDX, 0.5% on SPX, but a 0.3% loss on DJIA. Similarly FTSE and NKY eked out tiny gains, but DAX, weighed with additional problems (and a further rally in EUR) closed down 2.3%, after touching a six-month (and within 9 points of an 11-month) intraday low. Oil followed a similar pattern, declining earlier to rally into the US close, finishing 0.7% up. US Steel (X) gave up the previous day’s gains and gapped down at the open.

For once, the currency position was mixed, was traders absorbed the excitement of the week and the prospects for the weekend. EUR rallied again, to complete a V-shaped pattern and close flat for the week. JPY also rallied on BoJ suggestions that it could tighten monetary policy as early as next year. GBP continued to recover from the sharp drop on Wednesday. However Canada’s miss on GDP at 1330 and tariff fears kept the loonie in the red. AUD was also slightly down despite Gold adding a nugatory 0.4%. Yields were back up 6bp, erasing Thursday’s losses but finished roughly flat on the week.

Please note all figures and percentages given for daily movement on indices cover the entire cash and futures period in that day.


WEEKLY PRICE MOVEMENT

A mixed USD picture this week, with JPY sharply up, and CAD sharply down on the steel and aluminium tariffs. The forex trade of the week would certainly have been to sell CADJPY to make 3.11%. (The last time a pair moved 3% in week was Oct 20th last year). Volatility returned to indices after last week’s calm, with DJIA posting a lot of 100-150 point hourly candles. All indices fell all week, but the biggest mover, and best overall trade was DAX which gave up 4.34% on Italian election uncertainty. Gold has ignored most of this recent volatility and finished almost flat.

Bitcoin had a good week, up 7.98% whereas Ethereum was much quieter, finishing almost flat. Since our cut-off, both currencies have rallied into the weekend.

AUDUSD 0.7705 (-1.67%)
EURGBP 0.8921 (+1.41%) 
EURUSD 1.2316 (+0.19%)
GBPUSD 1.3800 (-1.21%)
NZDUSD 0.7240 (-0.71%)
USDCAD 1.2885 (+2.03%)
USDJPY 105.71 (-1.08%)
DAX     12000 (-4.34%)
FTSE     7129 (-1.91%)
NIFTY   10458 (-0.31%)
NKY     21181 (-3.87%)
SPX    2691.2 (-2.05%)
GOLD  1321.77 (-0.52%)
OIL     61.45 (-3.33%)
BTCUSD  11023 (+8.68%)*
ETHUSD 854.51 (-0.87%)*

*Prices at 0000GMT Mar 3rd

NEXT WEEK (all times are GMT)

Next week will initially be dominated by Sunday events in Europe, the Italian election (first exit polls at 2200), and the formation of a continuity coalition in Germany following the SPD vote. With four major rate decisions and NFP, next week should see the volatility unabated.

Monday sees the US International Trade Commission issue a decision on anti-dumping duty (tariff) on welded pipe imports. This affects Canada, China and India. Fed Quarles (voter, dovish) speaks at 18:15, but only on foreign bank regulation. The economic prints are all PMIs. All are well into growth (above 50), so only a large variation from estimate is likely to move markets. Australia is closed for Labor Day.

Tuesday sees the first of four rate decisions this week, conveniently spaced at one per day. The RBA are expected to keep rates on hold. AUD is under pressure at the moment, but any move may come on Gov Lowe’s speech which is 18 hours later (the next day, locally). Staying in that part of the world, the monthly NZ Milk Auction is today, and historically does affect NZD noticeably. We have a fractal for that. Fed member Dudley (centrist, voter) speaks at 1230, and Fed Governor Brainard (über-dove, voter) is on at 7pm Eastern (0000 Wed).

Remember this is NFP week, so Wednesday’s ADP ’sneak preview’ is always useful. Note that the new Canadian ADP report is not synchronised to be released two days before the official jobs report, so sadly we cannot plan a USDCAD position early. The estimate is 195k, close to the NFP estimate, so a large variation should have an effect. Also published at the same time are productivity and unit labor costs, part of the employment mix. Remember that four more rate hikes are said to be priced in, so a miss will have more effect than a beat. Today’s rate decision is from Canada. A hold is expected, but a rate hike is partially priced in for next month. CAD is of course under pressure because of the tariff announcements and NAFTA in general. Anything dovish could push CAD further down. Fed speakers today are Kaplan (dovish, non-voter) at 0130, Dudley and Bostic (both neutral voters) at 1300. Turkey, Poland and Malaysia also have rate decisions today.

Thursday’s key event is the ECB rate decision. As usual, the rate will are announced 45 minutes before the conference, and it is the latter where volatility usually occurs. Traders will be looking for an update on the long-term projections for Eurozone inflation (HICP), but further statements on unwinding will also be listened for. The BoC Deputy Governor Tim Lane’s speech is important as the first one after the rate decision. Otherwise the Trans-Pacific Partnership (excluding the US of course) FTA is due to be signed. Markets are closed in Russia.

Friday starts with the Japanese rate decision. It will be more interesting than usual after Governor Kuroda’s comments last Friday concerning an earlier exit from QE than expected. Maybe he will clarify further, and more JPY volatility than usual is possible

Otherwise the main event is, of course, the double NFP from the US and Canada. As in previous months, the AHE figure will be key, as an inflation indicator

The US NFP estimate is in line with previous months, but the Canada estimate at 68.5k is close to the record highs of December and January, and is equivalent to a US figure of 616k, population adjusted. If this beats, it must surely make an April rate hike a near certainty, and reverse CAD’s dismal record recently. There has also been talk about Canada being exempt from the new aluminum and steel tariffs as part of NAFTA, any firming up of this would also be a shot in the arm. Definitely one to watch. Also important in the Asian session is Chinese inflation. The Fed speaker roster is Rosengren (hawkish, non-voter) at 1740 and Evans (dovish, non-voter) at 1745. Finally as Oil seems to be responding to the API and EIA weekly stock reports, it is worth watching the response to the rig count.


CALENDAR (all times are GMT). High volatility items are in bold

Mon Mar 05
01:45 CNY Caixin China Services PMI
08:55 EUR Germany Markit PMI Composite
08:55 EUR Germany Markit Services PMI
09:00 EUR Eurozone Markit Services PMI
09:00 EUR Eurozone Markit PMI Composite
14:45 USD US Markit PMI Composite
14:45 USD US Markit Services PMI
15:00 USD US ISM Non-Manufacturing PMI

Tue Mar 06
00:01 GBP UK BRC Like-For-Like Retail Sales (YoY)
00:30 AUD Australia Retail Sales (MoM)
03:30 AUD RBA Rate Decision/Statement (1.5% hold est)
12:30 USD Fed Dudley speaks
14:00 NZD NZ GDT Milk (time approx)
15:00 USD US Factory Orders (MoM)
15:00 CAD Canada Ivey Purchasing Managers Index
21:30 WTI API Stock
21:35 AUD RBA's Governor Philip Lowe Speech
22:30 AUD AiG Performance of Construction Index

Wed Mar 07
00:30 AUD Australia GDP
01:30 USD FOMC Member Kaplan Speech
05:00 JPY Japan Leading Economic Index
05:00 JPY Japan Coincident Index
10:00 EUR Eurozone GDP (est 2.7% prev 2.7%)
13:00 USD FOMC Member Bostic speaks
13:00 USD Fed Dudley speaks
13:15 CAD Canada Housing Starts (Feb)
13:15 USD US ADP Employment Change
13:30 USD US Trade Balance
13:30 USD US Nonfarm Productivity/Unit Labor Costs
13:30 CAD Canada International Merchandise Trade
15:00 CAD BoC Rate Decision (1.25% hold est)
15:30 WTI EIA Stock
20:00 USD US Consumer Credit Change
23:50 JPY Japan FDI

Thu Mar 08
00:01 GBP UK RICS Housing Price Balance
00:30 AUD Australia Imports/Exports/Trade Balance
02:00 CNY China Imports/Exports/Trade Balance CNY and USD
05:00 JPY Japan Eco Watchers Survey
12:45 EUR ECB Rate Decision (0% hold est)
13:15 CAD Canada Housing Starts (Jan)
13:30 USD US Jobless Claims
13:30 EUR ECB Press conference
20:35 CAD BoC Gov Council Member Lane Speech
21:45 NZD NZ Electronic Card Retail Sales
23:30 JPY Japan CPI/Overall Household Spending (YoY)

Fri Mar 09
01:30 CNY China CPI/Producer Price Index
04:00 JPY BoJ Rate Decision/Press Conference (-0.1% hold est)
07:00 EUR Germany Imports/Exports/Trade Balance
07:00 EUR Germany Current Account
09:30 GBP UK Industrial/Manufacturing Production 
13:00 GBP UK NIESR GDP Estimate
13:30 USD NFP/AHE/AWH/Participation/Unemployment (est 190k prev 200k)
13:30 CAD NFP/Participation/Unemployment (est 68.5k prev -88k)
18:00 WTI Baker Hughes US Oil Rig Count

This report is published every week as an email by MatrixTrade.com - you can sign up to receive it here.


Sunday, 28 January 2018

Week to Jan 26th


On Monday the US Government shutdown was averted, and indices continued their upward trajectory, the SPX setting another all-time high. NKY and DAX followed suit enthusiastically, FTSE less so, hampered by sterling’s surprising strength in the continuing absence of bad Brexit news. Conversely, USD continued it’s downward path, with DXY shedding 0.2%., as EUR gained on progress in the German coalition. The greenback was down against all currencies except JPY, and Gold was down in line. Oil was up slightly, as was the US 10-year bond yield, which added 2bp after touching 2.672%, the highest rate in three and a half years. After the close, NFLX beat estimates and the stock went up over 10%.

Tuesday was relatively flat for indices, although that didn’t stop SPX advancing slightly (0.9%) to post another ATH. NDX was up a healthier 0.51% (to a new high) on the back of the NFLX results. Despite the raft of Germany and Eurozone Sentiment beats, DAX remained flat, as did FTSE and NKY, although the latter made a new intraday high in the Asian session. DXY manage to shed nearly 1%; virtually all other currencies (and Gold) were up, the only laggard being AUD which failed to recover fully from an dip in the Asian session. The BoJ rate decision at 0400 brought brief volatility on both directions, and then JPY continued to appreciate all day. Bond yields followed downward, and Oil was up in line.

Wednesday was a down day in the Asian session with NKY, and this continued in Europe after PMI misses for Germany (0855) and Eurozone (0900) with DAX and FTSE falling sharply. However, despite the risk-off signs of Gold and JPY both up, nothing can stop the US juggernaut, and SPX stayed flat but DJIA eked out another all-time high. TreasSec Mnuchin’s comments about being unconcerned about a weaker dollar continued to drive DXY down another 1%, and all other currencies appreciated substantially, as did Oil. Sterling was particularly strong, up 1.5% above $1.42 for the first time since the Brexit vote. Bonds yields were up 3bp, reversing the previous day’s losses.

The minor story on Thursday was another all-time high on SPX and DJIA, but for a third day, minor movement. The pressure on other indices this week is balancing the US (irrational?) exuberance. DAX, NKY and FTSE all fell. This US pricing is all momentum now, the indices barely react to news. The huge surprise of the day was, who else, President Trump at Davos who said at 1900 “the dollar is going to get stronger and stronger and ultimately I want to see a strong dollar”, effectively contradicting his TreasSec's remarks a day before. DXY immediately put on 1% and all currencies (and Gold and Oil) fell against USD for the day. Interestingly, bond yields had preceded the statement, peaking at 2.677% around 1500. After the yields receded, and ended down on the day, not reacting to the Trump remarks.

Prior to this, EUR had hit another three-year high of 1.2538 following the hawkish ECB press conference, where President Draghi ascribed the strength of the euro to external factors (ie the collapse of USD), and by implication, was not concerned, unlike last year when the single currency retreated from 1.20 after ECB concerns about the level. Also GBP touched a new intraday high of 1.4350. Cable is now back in the territory it occupied in H1/2016, when the UK polls predicted a Remain victory, or indeed the price the week before the Brexit vote. The Canadian Retail Sales print was a miss, but hardly any effect was seen.

Friday saw something we have seen every week this year (ie three times before) a strong closing rally in SPX and DJIA, and this week all the other indices followed suit. All three US indices ignored the normally significant GDP miss, and posted all-time highs again, with NDX breaching the psychological 7,000 roundpoint for the first time. The rally was repeated elsewhere with NKY, DAX and FTSE also up, the latter being particularly strong, posting its best day of 2018, up nearly 1%.

The Trump dollar effect was very short-lived, and USD continued to fall, erasing the 1% gain from the previous day. Canada missed on monthly CPI at 1330 causing a brief dip of 0.49%, which was quickly recovered, and all currencies ended up on the day, the standout being AUD (despite Australia being closed) which posted a 1% gain, and touched 0.8135, a level not seen since May 2015. Gold was slightly up, in line, as was Oil, and yields were sharply up (4bp) touching a fresh 9-year high of 2.13%.

WEEKLY PRICE MOVEMENT
These are the prices movements for the week on the instruments we cover, with USD pulling back for a seventh week, against all currencies, more sharply than in previous weeks. the best forex trade would have been to buy cable, up 2.27%. The top index and overall performer was DAX.

At the time of writing, Bitcoin was priced around $11,000, down 4% on the week as the Rodrigue bubble fractal plays out, and volatility reduces.
AUDUSD 0.8108 (+1.55%)
EURGBP 0.8776 (-0.44%)
EURUSD 1.2429 (+1.76%)
GBPUSD 1.4163 (+2.27%)
NZDUSD 0.7358 (+1.15%)
USDCAD 1.2314 (-1.46%)
USDJPY 108.59 (-2.00%)
DAX     13389 (-0.56%)
FTSE     7640 (-1.25%)
NIFTY   11064 (+1.56%)
NKY     23731 (-0.47%)
SPX    2874.1 (+2.27%)
GOLD  1350.66 (+1.43%)
OIL     66.24 (+4.36%)


NEXT WEEK (all times are GMT)

A busy week, with both scheduled and unscheduled news. The Trump Mueller investigation is back in the news, and traders are still pondering Trump’s “stronger dollar” remarks. Speculation about the Fed vice chair position may also feature. And of course it’s US rate decision and NFP in the same week.

A press conference is expected on Monday after NAFTA negotiations conclude. CommSec Ross said last week at Davos that he expected “a good chance” of success. China’s National People’s Congress Standing Committee discuss changes to the constitution. The main news of the day is US Personal Consumption Expenditure, an inflation proxy.

The main news on Tuesday comes from Europe with German inflation and Eurozone GDP, and BoE Governor Carney speaking to the UK Parliament. President Trump’s State of the Union address is at 2100 after markets close. NZ Finance Minister Robertson speaks at 2130.

Wednesday sees Australian and Eurozone inflation prints, but the big news is the FOMC rate decision. The CME Fedwatch consensus is 96.4% for a hold, so no real surprises are expected, but inevitably there will be dollar volatility following the release of the FOMC minutes, and the dot-plot forecast. We will be publishing our fractals as usual. Don’t forget also the ADP Payrolls figure, an indicator to NFP. The estimate (at 180k) is in line with the NFP estimate, so a strong variance may well move the dollar. It ought to move SPX as well, but as you know, the index seems immune to news these days. We also have Canada GDP 15 minutes after ADP, another potential flashpoint for USDCAD. Also speaking today is BoJ Iwata (dove) at 0130. Look for end of month rebalancing signs as the day goes on. We expect high volatility in NQ (NDX futures) after the US bell as FB, and MSFT report (they total 14.66% of NDX by weight). Also reporting is  BA, the largest (at 8.88%) component of DJIA. Every 1% move in Boeing causes a 23.6 point move in the Dow.

Thursday starts the new month. The calendar for the day is all PMIs, but the only important one is the ISM print at 1500. It separates out prices paid, which is, to an extent, a forward indicator for inflation. Action on the day is more likely to be driven by how traders read the Fed report, and then as the US session progresses, all eyes will again be on NDX and NQ_F in anticipation of heavyweights AAPL, GOOG, AMZN all reporting after the bell. Between them these three make up 28.87% of NDX, so volatility is assured. BABA also reports. Surprisingly, this stock is not in NDX.

Friday of course is NFP day. As usual, if the print is close to the estimate, traders will be looking at unemployment and average hourly earnings, which may include the ‘Trump tax Christmas bonuses’ although arguably some of that money may not flow through until February. In recent months, markets have paid less attention to NFP, but who knows, the effect must surely return at some time. Note that Canada’s NFP is non-synchronous this month (ie it is released a week later), depriving us of the volatile USDCAD play. To end the week, SF Fed President Williams speaks at 2030.


CALENDAR (all times are GMT). High volatility items are in bold

Mon Jan 29
0000 AUD Australian New Home Sales
1330 USD US PCE YoY (inflation proxy) (est 1.6% prev 1.5%)
1530 USD Dallas Fed Manuf Business Index
2145 NZD Trade Balance/Imports/Exports
2330 JPY Japan Jobs/Unemployment
2330 JPY Japan Overall Household Spending (inflation proxy)
2350 JPY Japan Large Retailer Sales/Retail Trade

Tue Jan 30
0900 EUR Germany CPI (prev 1.6%)
0930 GBP UK Consumer Credit/Mortgage Approvals
1000 EUR Eurozone GDP (est 2.6% prev 2.6%)
1000 EUR Eurozone Sentiment Indicators
1400 USD S&P/Case-Shiller US Home Price Indices
1530 GBP BoE Governor Carney speaks
2130 WTI API Stock

Wed Jan 31
0001 GBP UK Gfk Consumer Confidence
0030 AUD Australia CPI (est 1.7% prev 1.8%)
0100 CNY China PMIs
0200 USD President Trump speaks
0700 EUR Germany Retail Sales
0900 EUR Germany Unemployment
1000 EUR Eurozone Unemployment
1000 EUR Eurozone CPI (est 1.3% prev 1.4%)
1315 USD US ADP Payrolls (est 180k prev 250k)
1330 CAD Canada GDP MoM
1445 USD Chicago PMIs
1500 USD US Pending Home Sales
1530 WTI EIA Stock (est -2.00M prev -1.07M)
1900 USD Fed Rate Decision & MPC (est hold 1.5%)
2230 AUD Australia AIG Performance of Manuf Index
2350 JPY Japan FDI

Thu Feb 01
0245 CNY China Caixin Manuf PMI
0855 EUR Germany Markit Manuf PMI
0900 EUR Eurozone Markit Manuf PMI
0930 GBP UK Markit Manuf PMI
1330 USD US Jobless Claims/Productiivity/Labor Costs
1430 CAD Canada Markit Manuf PMI
1445 USD US Markit Manuf PMI
1500 USD ISM Manuf PMI/Prices Paid
1500 USD US Construction Spending
2145 NZD NZ Building Permits

Fri Feb 02
0930 GBP UK Construction PMI
1000 EUR Eurozone PPI
1330 USD NFP/Unemployment/Participation/AHE/AWH
1500 USD Factory Orders
1800 WTI Baker Hughes Rig Count

This report is published every week as an email by MatrixTrade.com - you can sign up to receive it here.