Showing posts with label Labor Day. Show all posts

Sunday, 13 September 2020

Week to Sep 11th

Labor day short week, US Correction continues with risk-off trading, GBP down on Brexit
MY CALL THIS WEEK : SELL EURGBP


In a week where negative news (COVID relief, jobs print) was not balanced by anything positive, it was no surprise to see a risk-off second week of retreat in equities, and reversal back up in Gold. The dollar continued to recover from its two-year low last week, and would have probably gone further were it not for a strong showing from EUR after a hawkish ECB press conference.


Next week is the Fed rate decision meeting, which invariably moves both the dollar and markets. Also of heightened interest is the BoE decision, coming during a renewed interest by the markets in Brexit, as the Dec 31 deadline to do a deal approaches with little progress in sight. 


Mon Sep 7

Markets were closed in the US for Labor Day, but European markets rose, mainly in defensives. The dollar was up across the board, but the notable move was GBP, down sharply on fears than PM Johnson plans to override part of the existing agreement.


Gold fell slightly, and Oil was flat. The US bond market was closed.


Tue Sep 8

Last week’s rout continued today with sharp falls across the board, but particularly in tech stocks. TSLA plunged 21% its worst day ever, and FANG stocks underperformed NDX overall. Oil fell over 6% in line. This was a reaction to tech overvaluations, rather than any specific news, and was probably triggered by TSLA. USD was firmly up, except, as you would expect, against JPY, which along with Gold and Bonds were up. All assets in line for a classic risk-off day.


Wednesday September 9

There was a rebound today from yesterday’s drop and all indices were up. Notably tech and industrial stocks recovered in about equal proportions, typically 2/3 of the Tuesday drop. Oil and yields were up in line. The dollar was down, dipping as EUR bounced off August support lines, and Gold rose on the weaker dollar.


Thursday September 10

A disappointing Initial Jobless Claims figure, and a blockage by the Dems of the latest COVD recovery package put a damper on the market, which fell again today. Once again, tech fell further. The ECB left everything unchanged, and did not express any concern about appreciation, which was consider hawkish, and EUR shot up, but then faded. Together with a further decline in GBP, this left USD up for the day. Oil was down, and Bonds and JPY were up, both in line with equities, and Gold was down in line with the stronger dollar. An interesting comparison to Tuesday, a similar equity move, but an opposite direction for USD.


Friday September 11

The week ended quietly, with SPX flat, DJI slightly up, and NDX down. Similarly the dollar was flat today with little volatility, as was Gold, and Oil. Bonds were slightly up. The week closed with notable divergence, with US indices down, but foreign (particularly FTSE) up.


WEEKLY PRICE MOVEMENT

Unusually we had an index over 4% down (NDX) and one over 4% up (FTSE) this week, the latter due to the large fall in GBP, which was reflected in the largest forex move, EURGBP up 3.85%. Cryptos went back to sleep, and FANGs underperformed NDX, particularly AAPL down 7.41%.

I played safe buying AUDNZD, and safety only gets you small rewards, up 0.80% (7.12% running today 16 wins out of 31). I am backing reversion this week, selling EURGBP, which is overbought on the daily chart for the first time since March.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.


NEXT WEEK (all times are GMT)

(Calendar High volatility items are in bold)

  • Fed Rate Decision week
  • UK and Japan rate decisions
  • Expect Brexit volatility
  • UK, EU and Canadian inflation

Monday September 14

There is a vote scheduled today on Boris Johnson's new 'internal market' bill which is at odds with the current agreement on Northern Ireland. EU leaders have said that if this passes, it will make a deal impossible. Otherwise, there is very little in scheduled news today.


09:00 Eurozone Industrial Production


Tuesday September 15

News from China and Europe, but nothing important from the US today. There is a rate decision in Poland.


01:30 RBA Meeting Minutes

02:00 China NBS Press Conference

02:00 China Industrial Production (YoY)(Aug)

02:00 China Retail Sales (YoY e-1.4% p-1.1%)

06:00 UK Unemployment (e3.9% p3.9%)

09:00 Eurozone ZEW Sentiment Survey

09:00 Germany ZEW Sentiment Survey

13:15 US Industrial Production (MoM)(Aug)

23:50 Japan Imports/Exports/TB


Wednesday September 16

The Fed rate decision today has a hold 100% priced, and it is unlikely that the current QE plan or dot plot will change. However, markets are always look for more. There is also a rate decision in Brazil. Markets are closed in Mexico.


06:00 UK CPI (YoY e1.3% p1.0%)

12:30 US Retail Sales (MoM e1.1% p1.2%)

12:30 Canada BoC CPI (Core YoY e0.9% p0.7%)

18:00 Fed Rate Decision/Statement

18:30 Fed Chair Powell Presser

22:45 NZ Q2 Final GDP (QoQ e-1.0% p-1.6%)


Thursday September 17

The Bank of England leads today, especially as Brexit rears its head again. There are also a rate decisions in South Africa and Indonesia.


01:30 Australia Jobs/Unemployment (Jobs e40k p114.7k)

03:00 BoJ Rate Decision/Statement (e-0.1% hold)

06:00 BoJ Presser

09:00 Eurozone CPI

11:00 BoE Rate Decision/Statement (e0.1% hold)

12:30 US Building Permits/Housing Starts

12:30 US Jobless Claims

12:30 Philly Fed Mfr Survey

23:30 Japan National CPI


Friday September 18

The main US release is the Michigan Consumer Sentiment Indicator. There is a rate decision in Russia. Markets are closed in Chile.


06:00 UK Retail Sales

06:00 Germany PPI

12:30 Canada Retail Sales (MoM e24.5% p23.7%)

14:00 Michigan Prelim CSI (e76 p74.1)

Sunday, 6 September 2020

Week to Sep 4th

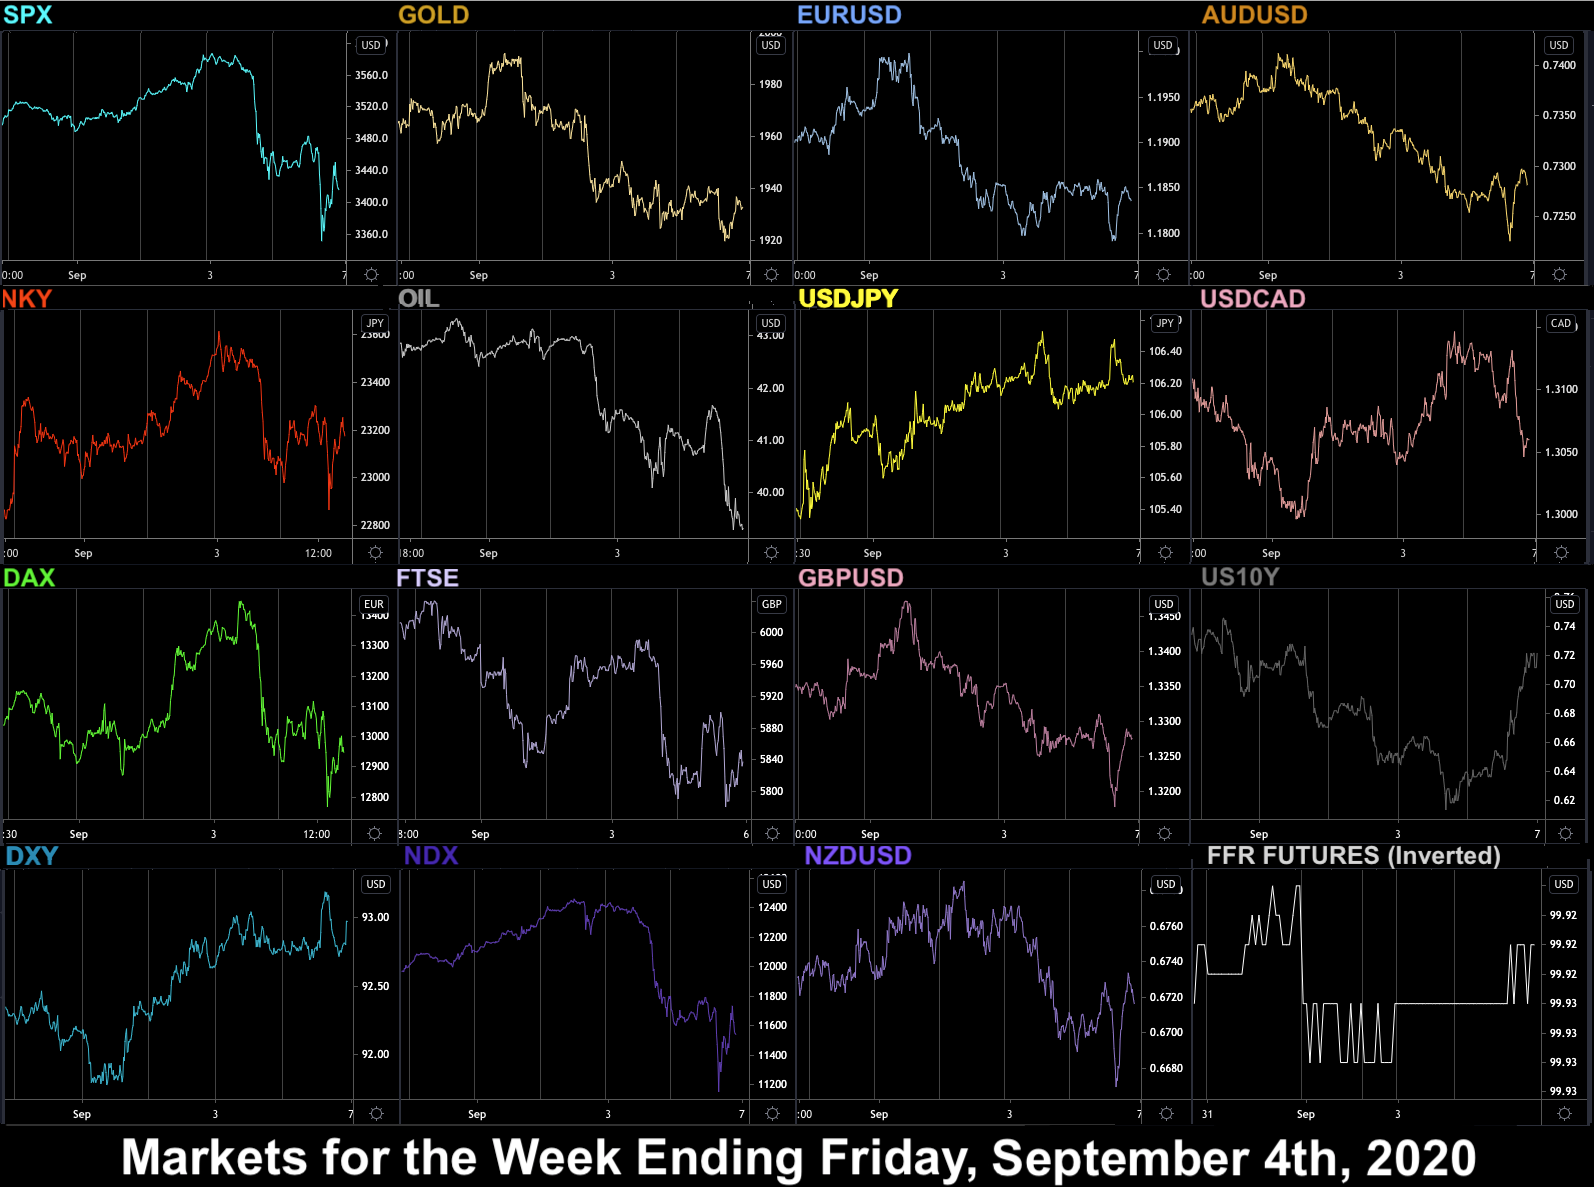
Firm tech and general correction, Softbank ‘whale’ revealed, DJIA component change
MY CALL THIS WEEK : BUY AUDNZD


This week saw the most significant market splits (AAPL and TSLA) for years, and the market close its best August since 1986, making new all time highs in SPX and NDX. On Wednesday, NDX broke 12400, a 24% gain in two months. The next day a bubble burst, with NDX shedding 650 points, its third-largest ever point drop (and in the top 30 worst days ever). This was later confirmed to be partly due to a ‘whale’ buyer SoftBank driving up particular stocks in the tech market to extreme levels.

The DJI/NDX ratio touched 2.317 this week, a level only seen once before in the second week of March 2000. Also VIX touched its highest level since June, and notably had been rising since August 26, a rare example of index/VIX positive correlation.

There was no particular news trigger on Thursday. It was a thin news week, with only the ISM PMI (beat) on Tuesday and the ADP (miss) on Wednesday. Friday’s NFP miss may have contributed to a further fall. At the lowest point on Friday, the index was 10.3% down in two days, but still only back to the level three weeks ago.

Next week is also very thin on US macro news, with Friday’s inflation report the only print of note. We can therefore expect sentiment-driven two-way enhanced volatility which invariably follows sharp drops.


Monday August 31
It was the first day of the newly constituted DJIA today. Markets took a breather today and pulled back slightly, although NDX advanced again, and all three US indices recorded their best August since the 1980s. TSLA ramped 13% after its 5:1 stock split. Non-US indices did not join the party, both DAX and FTSE were down on stronger currencies.
Oil was down in line with the pullback. The dollar continued down, except surprisingly against JPY. However the other two haven assets move up in line with the equity fade.


Tuesday September 1
Another up day, lead by tech. AAPL was up nearly 4% (over 7% in two days), adding 0.28 points to SPX on its own, which made a new ATH. Note AAPL’s weight in SPX, at 6.89% (a market cap weighted index) is now much more than it is in DJIA (an absolute share price weighed index). Lockdown darling ZM was up 40% on earnings. Oil was up in line. DAX was flat, and again FTSE on strong sterling, touching 1.3480 for the first time in 2020, 

However the RSI reading on SPX today of 83, and this fragility may be reflected in the fact that all three haven assets were up today. USD was up, after DXY touched a new 2-year low of 91.75 but this was mainly due to weak EUR after the German Manufacturing PMI miss. 


Wednesday September 2
Yet another up day, but this time with DJIA outperforming NDX, with the markets shrugging off the ADP 50% jobs miss, but who can tell with jobs figures these days. DJIA stalwart KO was up 4%, whereas AAPL fell 2%. Surprisingly, Oil fell despite the EIA beat at 1530 and buoyant equities. The dollar turned up from its low, advancing across the board. Gold and JPY fell in line with equities, but yields followed the dollar.


Thursday September 3
After a quiet morning, markets fell very sharply, in a move reminiscent of Jun 11 (also a Thursday), with SPX down 3.5% and NDX nearly 5%. AAPL fell 8%. Global markets were also down, but by much less. Oil was down in line. There had been trade and PMI misses, but these were not really the trigger. In fact, nobody was surprised after the massive run up in tech stocks recently, and many commentators talked about a ‘healthy’ correction. Other asset classes were not correlated, showing this was not true risk-off. Gold and bonds were both down. The dollar was generally flat with CAD gains balancing GBP losses, and a flat EUR. Notably Bitcoin dropped 10%, its worst day since March.


Friday September 4
With very little regard to NFP (jobs slight miss but a strong beat on unemployment), the carnage momentum continued for a second day, although a late rally pared losses. For example, AAPL at one point was a further 6% down, although it managed to claw all that back and close green. TSLA was a similar story, dropping nearly 9% then recovering to close 2.8% up. Losses were still deeper in tech at the close, although the story for the week was more modest, with NDX underperforming SPX by less than 1%. Oil was down in line, more sharply in a delayed reaction (it closed at lows). This time Gold and Bonds were up in line. USD had another directionless day, closing slightly up, mainly on CAD weakness.

Today Japanese tech investor Softbank was revealed as the ‘whale’ behind the recent huge rises in tech stocks, an options strategy which is now complete.


WEEKLY PRICE MOVEMENT
NDX was the weakest index and biggest mover. AUDCAD made the largest move (1.38%) in forex. BTCUSD finally moved after weeks in the doldrums, although ETH was flat, and FANGS, in the end, roughly tracked the general NDX index.

My NZDCAD short paid off. The pair gapped down (not counted) and ended up 0.41% on the week. running total 6.32%, 15 wins out of 30. This week I am buying AUDNZD.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.

NEXT WEEK (all times are GMT)
(Calendar High volatility items are in bold)
  • Labor day short week
  • Will correction continue
  • ECB and BoC rate decisions
  • US, Germany, China inflation

Monday September 7
Today is Labor Day so US and Canadian markets are closed. A quiet day is expected.

03:00 China Imports/Exports/TB (time approx.)
06:00 Germany Industrial Production
23:50 Japan Q2 Final GDP (QoQ e-8.1% p-7.8%)

Tuesday September 8
A quiet news day in this quiet week. Keep watching election news.

06:00 Germany Imports/Exports/TB
09:00 Eurozone Q2 GDP (QoQ e-12.1% p-12.1%)


Wednesday September 9
A third day without significant US releases, so Canada becomes centre-stage. USDCAD is approaching 1.2950, its January low, so risk is to the upside.

00:30 Aus Westpac Consumer Confidence
01:30 China CPI (YoY e2.4% p2.7%)
14:00 BoC Rate Decision/Statement (e0.25% hold)


Thursday September 10
All eyes today on ECB President Lagarde, and the latest Eurozone stimulus plans.

01:00 Aus Consumer Inflation Expectations(Sep)
11:45 ECB Rate Decision/Statement (e0% hold)
12:30 US PPI/Jobless Claims
12:30 ECB Lagarde Presser
16:30 BoC Governor Macklem speech


Friday September 11
A portentous date, and in data, US and German inflation may be the most significant prints of the week.

06:00 UK Manuf/Industrial Production
06:00 UK GDP (MoM)(Jul)
06:00 Germany CPI (YoY e-0.1% p-0.1%)
12:30 US CPI (Core YoY e1.6% p1.6%)
18:00 Monthly Budget Statement

Sunday, 8 September 2019

Week to Sep 6th


NFP miss after ADP beat, Dollar reversal, Brexit doves win a round

Mon Sep 02
Today was Labor Day, a US holiday, so as you might expect the action was elsewhere. Asian indices fell as the new US tariffs on China came into place, and DAX and US Futures followed suit. The British parliament opened after summer, and immediate Brexit antagonism caused a sharp drop in GBP which allowed FTSE to rise. Other currencies were slightly down and DXY finished 0.24% up on the day. Gold, Oil and Bond futures were flat


Tuesday September 03
Equity markets carried on drifting downwards, after a series of trade release misses, most significantly the ISM Manufacturing PMI at 1400 which move below 50, ie into contraction for the first time in three years. The print of 49.1 from the estimate of 51 is equivalents to a -0.9% after a +1.0% estimate in other statistics. Oil was down, and Gold, JPY and Bonds were up in line. After briefly hitting a two-year high of 99.37, DXY was down 0.08%, with GBP up on hopes of frustrating a no-deal Brexit, and AUD following gold. However with EUR and CAD flat the move was minimal.


Wednesday September 04
The China Caixin Services PMI beat at 0145 set the mood, followed by PMI and Retail Sales beats in Europe. Equities snapped their losing streak, and SPX added 1.1% on the day. The dollar fell steadily all day, giving up 0.57% as Gold and all currencies except risk barometer JPY advanced. CAD was particularly strong after hawkish remarks from the BoC following the rate hold at 1400. Oil was up in line with equities, and 10-year bond yields were flat, but the 10/2 yield curve climbed back into positive territory. The four Fed speakers added little to what we already knew.


Thursday September 05
Today’s announcement of new high-level US-China trade talks, which of course have stalled recently, in addition to successful moves in the UK parliament to block a no-deal Brexit, and a beat on the ISM Non-Manufacturing PMI at 1400, was enough to continue the equities and Oil rally. SPX added 1.3%, its best day in three weeks. A relatively flat DXY (up 0.02%) disguised a rally in most currencies, but the inevitable pullback in JPY (and Gold). CAD gave back a little of Wednesday’s rally. Yields were sharply up on bond-stock rotation.


Friday September 06
Friday’s NFP was a miss (130k vs 158k) and as the rate decision is next week, the ‘bad is good’ effect applied. A low figure makes a rate cut more likely. However, as a 25bp rate cut is already 91.2% priced in, per the CME Fedwatch tool, there was no sudden move in equities, which did nevertheless all gain on the day, as did Oil. DXY was down 0.37% on the same principle, mainly due to a further CAD rally and pullback in JPY. Unusually, 0.3% of this move was in the last three minutes of trading. GBP and EUR gave back some of the week’s rally and yields were down in line with rotation and rate cut hopes.

Surprisingly, there was little reaction to Fed Chair Powell’s speech at 1630, in which he said he does not expect recession and the economy is in a “good place”. He reiterated that the Fed will not be swayed by politics (eg Trump pressure to cut rates).


WEEKLY PRICE MOVEMENT
The top performing index this week was, unusually, DJIA, and our top performing tracked share was AMZN. In currencies, the rarely traded AUDCAD pair, if shorted would have made the best return. Crypto, still quieter than it used to be, returned north.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.


NEXT WEEK (all times are GMT)
(Calendar High volatility items are in bold)

  • ECB dovishness expected
  • Chinese and German inflation
  • British Parliament prorogued
  • Three quiet scheduled news days

Monday September 09
Having passed a law on Friday to force PM Johnson to ask for a Brexit extension, the British Parliament may force further moves to prevent a no deal exit. GBP did not react positively to Friday’s move, volatility may occur today.

07:00 CNY China Imports/Exports/TB (Sunday)
23:50 JPY Japan GDP (Sunday) (QoQ e0.3% p0.4%)
06:00 EUR Germany Trade Balance s.a.
08:00 GBP BoE Vlieghe speech
08:30 GBP UK GDP (MoM)
22:45 NZD NZ Electronic Card Retail Sales (MoM)


Tuesday September 10
The UK parliament is suspended or prorogued this week, although the Brexit saga may continue in the courts. A second day of no significant American news. Markets in India are closed.

01:30 CNY China CPI (YoY e2.6% p2.8%)
07:00 CNY China FDI
08:30 GBP AHE/UnEmp (AHE e3.8% p3.9%, Unemp e3.9% p3.9%)


Wednesday September 11
An ominous date in history, but yet another quiet day on the news front. There is a rate decision on PLN.

12:30 USD US PPI
23:50 JPY Japan Machinery Orders


Thursday September 12
Today's ECB decision and press conference, the penultimate one for outgoing President Draghi is the most important event of the week, especially as the conference is concurrent with the US inflation print. A reduction to the deposit rate (not the base rate) may be on the cards. Watch out to see if President Trump tries to tweet the dollar down. There is a rate decision on TRY where a 3% cut is expected.

06:00 EUR Germany CPI (YoY e1.0% p1.0%)
09:00 EUR Eurozone Industrial Production (MoM)
11:45 EUR ECB Rate Decision/Statement (e0.% hold)
12:30 EUR ECB President Draghi Presser
12:30 USD Jobless Claims
12:30 USD US CPI (YoY e2.3% p2.2%)
18:00 USD US Monthly Budget Statement


Friday September 13
The Michigan Consumer Sentiment Index hit a three-year low last month, and recovery is assumed. Markets in China, Taiwan and Korea are closed.

00:00 EUR Eurogroup Meeting (all day)
12:30 USD US Retail Sales (Control Group Aug e0.3% p1.0%)
14:00 USD Michigan CSI (e90.5 p89.8)


This report is published every week as an email by MatrixTrade.com - you can sign up to receive it here. This blog is supported solely by advertising, so if any of the ads interest you, please click on them. If you want notification when the blog is updated, please follow me on Twitter, Facebook, Stocktwits, TradingView or Linkedin (all open in separate windows). Details of how I compile the report are here.