Showing posts with label Brexit. Show all posts

Saturday, 26 December 2020

Week to Dec 25th

Short Christmas week, New COVID strain, Brexit and US stimulus deals agreed
MY CALL THIS WEEK : SELL EURCAD

Despite the fact that it was the final short week before the holidays, and macro data was unsurprising, there were three big news items: the new more infectious COVID variant, the US stimulus deal finally agreed, and at the very close of the week, the long-awaited Brexit deal. All markets reacted to the first, only currencies to the second, and only GBP to the last as markets closed on Thursday lunchtime, although there was some more movement in currencies on Christmas Day, notable in EURGBP. Nevertheless the net effect was a fairly flat week, with no index moving more than 1%, as neither did any other asset except GBP and Oil.


Next week is the traditional core Santa Rally, and equities are expected to rise in thin trading, as many traders take the week off. London has an extra day off, so low volumes of forex trading plus the digesting of the full Brexit deal may produce some strange moves as seen on Christmas Day. Again macro news is slight. There may also be some year end last minute rebalancing (which means winners go up further and losers fall further)


I hope you have a happy Christmas and prosperous New Year.


Mon Dec 21
Equity and Oil Markets pulled back today on news of a new, more transmissible strain of coronavirus discovered in the UK and South Africa. The sell off held in Europe, but later trading in the US trimmed US losses and DJIA even managed to close slightly positive. After weeks of decline, the dollar perked up and was up across the board against all currencies and Gold. Bonds were flat on the day.


Tuesday December 22

Good news today as Congress finally passed the stimulus package. Also the WHO confirmed that the vaccines would still work against the new COVID variant. Europe recovered some of yesterday’s losses, and there was a slight rotation into NDX (up) from DJI and SPX (down). However Oil was down on the day, bonds were up, and JPY was up against all currencies except USD, which was strong after the stimulus news. Gold fell on dollar strength. So a mixed response really.


Wednesday December 23

Today was flat for SPX, with DJI and NDX reversing Tuesday’s rotation. Europe continued to recover from Monday’s drop, even against currency rises as the dollar gave up its rally and turned south, posting red candles against Gold and all currencies except JPY, which fell with bonds. Oil was also up on this overall positive day.


Thursday December 24

Germany was closed, and London and New York only did half-days today. However, the Brexit deal was confirmed before markets closed, and the notable movement was a rise in GBP and consequent fall in FTSE. Otherwise equity and Oil markets were up as Santa sentiment continued. The dollar was flat overall, as JPY fell to balance the GBP rise. Surprisingly though, Gold and bonds were up.


Friday December 25

Today was Christmas Day and markets everywhere except Japan and China are closed. There were however, notable moves in forex, with EURGBP adding 1.74% as the GBP rally fizzled out.


WEEKLY PRICE MOVEMENT

Indices were flat this week, with the biggest mover FTSE down 0.41% on GBP strength before Friday. Cable was the biggest mover down 1.27% on the week, the entire move being made on Christmas Day. Bitcoin made a new ATH on Christmas Day, and is outperforming Ethereum. FANGS were very mixed, with AAPL outperforming, up 4.19%.


My USDCAD trade worked, up 0.64%, moving my running total to 8.67% and 24/41 wins. This week I am selling EURCAD. Last week’s candle up was much larger than usual and I am looking for reversion to mean.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.


NEXT WEEK (all times are GMT)

(Calendar High volatility items are in bold)


Monday December 28

The US re-opens in what is traditionally a very strong three and half days, the core Santa Rally. The UK, Canada, Hong Kong and Australia are closed for Boxing Day observed.


23:50 Japan Industrial Production (Sun)


Tuesday December 29

The rest of the world markets open, the first day since the Brexit deal announced late on Christmas Eve. This should prove positive to markets, but there may be some sector variance (eg automobiles, the core part of DAX).

14:00 US S&P/Case-Shiller Home Price Indices


Wednesday December 30

Today is the UK Parliamentary Vote on Brexit deal, however it expected to pass easily as the opposition Labour Party have confirmed they will vote with the government.


07:00 Germany Retail Sales

14:45 Chicago PMI

15:00 US Pending Home Sales


Thursday December 31

The final day of 2020 may see some volatility through portfolio rebalancing. However, as most markets close at lunchtime, general trading is expected to be thin. Germany is closed for Silvester (New Year’s Eve)


01:00 China PMIs

13:30 US Jobless Claims


Friday January 1

All markets globally are closed today for New Year’s Day.

Sunday, 13 December 2020

Week to Dec 11th

ECB $500Bn QE, FDA approves vaccine, SPX ATH, GBP Brexit concerns
MY CALL THIS WEEK : SELL AUDJPY


The vaccine rally took a breather this week, disappointed with the failure of both Congress to agree the next stimulus package, and of the UK and EU to agree a Brexit deal. Although SPX eked out another ATH, the mood was more risk-off, as demonstrated by the return to rotation into DJI out of NDX. The dollar came off last week’s low and consolidated in an inside week. As you would expect GBP whipsawed to end to the downside by more than 2c, but EUR was surprisingly stable, despite the $500Bn stimulus announced. EUR and JPY also had inside weeks. Gold had a brief rally which faded to flat, in the absence of a dollar cue. Oil continued its OPEC advance, pushing CAD to a new 31-month high.


Next week is the last ‘normal’ week of the year before the foreshortened Christmas and New Year weeks, and is also triple-witching OpEx when weeklies, monthlies, quarterlies and annuals all expire on the last trading Friday of the year. Quarterlies of course include SPY and QQQ. On the news front, Brexit talks are supposed to end on Sunday, but we would not be surprised if they continued, as no-deal is bad for both sides. Also, there is the key FOMC rate set and report, and of course a similar event in the UK a day later. GBP volatility seems assured, the extent to which it will spread to other markets remains to be seen. SPX fell 2.7% on the original decision in June 2016, although it fully recovered the following week.


Mon Dec 7

Uncertainties about the vaccines meant the rotation today was firmly back into tech, with NDX up 0.54% but DJI down 0.49%. Sensitive financials and energy were the biggest fallers. Even FTSE only managed to stay flat as GBP fell on Brexit no-deal concerns. In general, USD was up, bouncing off last week’s low, but in line with the SPX move, JPY outperformed, as did Gold and bonds. With Oil also down, we can say this was a risk-off day overall.


Tuesday December 8

Although SPX hit a new ATH today, movement was not strong, and there was no noticeable rotation.  All three US indices were up 0.3%, whereas Europe was flat. The dollar was similarly lacklustre, registering a slight increase entirely due to EUR. The other assets classes were similarly flat.


Wednesday December 9

Continued wrangling over the stimulus bill, and concerns about Brexit mean equity markets and Oil fell today, particularly NDX which was sharply down into the close, losing over 2% on the day. USD was up, entirely due to EUR again, being sold off in advance of Thursday’s ECB. Brexit caused a wild day on GBP which was up 1% before the US bell, and then lost it all to close flat. Gold was down on the stronger dollar. Bonds were slightly down.


Thursday December 10

Today the ECB announced further asset purchases, expanding the QE by $500Bn. This pushed European periphery bond yields to all time lows (Spain joined Portugal in slipping into negative territory), and rallied EUR by 0.5%, the ‘feel good’ factor outweighing the natural decline you would expect from loosening. This meant a down day for DXY, despite a Brexit-led drop in GBP. EURGBP was up 1% on the day. The antipodean pair were up over 1%,and CAD added 0.65% on a strong spike up in Oil.


The FDA approved the PFE vaccine for use, and equities rotated into risk, with NDX up against a slightly down SPX and DJIA. But this was after Wednesday’s tech selloff. Nothing has changed, optimism about the vaccine, pessimism about the Congress stimulus package and Brexit, and the bigger picture is a slight pullback from the highs. US Bonds were up today, following the cue from Europe.


Friday December 11

Another down day for indices and Oil as Brexit no-deal came closer, with a slight upturn at the end as the Senate passed legislation to avoid the annual government shutdown threat, one factor at least that we can discount this year. Gold, bonds and JPY were up in line.


Both GBP and EUR fell as the Brexit talks still failed to produce a result, meaning DXY was up sharply as GBP lost 1.5% in a few hours. There was talk of negotiations not continuing past Sunday. The week closed with indices firmly down except for FTSE which tends to run inversely to sterling.


WEEKLY PRICE MOVEMENT

Indices were down this week, with DAX the worst at -1.39%. GBPAUD was the biggest mover, down 3.07%. Crypto volatility has slowed down, and FANGs were similarly less volatile than in the past, with GOOGL down 2.68% the biggest mover.


My NZDCAD buy was up 0.48%, taking my total to 8.49% and 23/40 wins. This week I will sell AUDJPY as it seems to be at resistance, and the AUD move last week seems overdone.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.


NEXT WEEK (all times are GMT)

(Calendar High volatility items are in bold)


  • FOMC Rate Decision
  • UK and Japan Rate Decisions
  • Brexit final deal decision
  • Last full week of the year


Monday December 14

As often happens Monday is quiet on news in this final full week of trading before Christmas.


23:50 Tankan Manufacturing Index (e-15 p-27) (Sunday)

10:00 Eurozone Industrial Production


Tuesday December 15

Another day where news is mostly outside the US. There is a rate decision in Hungary.


00:30 RBA Meeting Minutes

02:00 China Retail Sales (p 4.3%)

07:00 UK Claimant Count/UnEmp/AHE (UnEmp e5.1% p4.8%)

14:15 US Industrial Production (MoM)(Nov)

19:30 BoC Governor Macklem speech

22:00 Aus Commonwealth Bank PMIs

23:50 Japan Imports/Exports/TB


Wednesday December 16

As well as a full day of Markit PMI, Canadian inflation, we have the final FOMC meeting of the year.    Markets are closed in South Africa.


07:00 UK CPI (YoY e0.6% p0.7%)

08:30 Germany Markit PMIs (Mfr e56.5 p57.8)

09:00 Eurozone Markit PMIs (Composite e46.2 p45.3)

09:30 UK Markit PMIs (Services e50.5 p47.6)

12:30 Canada BoC CPI (Core p1%)

13:30 US Retail Sales (MoM e-0.4% p0.3%)

14:45 US Markit PMIs

19:00 FOMC Rate Decision/Statement

19:30 FOMC Press Conference


Thursday December 17

The usual raft of US data at 1330 today. In addition to the BoE, there are also rate decisions in Switzerland, Norway, Czechia and Mexico.


00:30 Aus NFP/UnEmp (NFP e50k p178.8k)

10:00 Eurozone CPI

12:00 BoE Rate Decision/Statement (e0.1% hold)

13:30 US Building Permits/Housing Starts

13:30 US Jobless Claims

13:30 Philly Fed Mfr Survey

23:30 Japan National CPI


Friday December 18

Today is quad-witching option expiration, where weeklies, monthlies, quarterlies (including the important index options ie SPY and QQQ) all expire together. Expect volatility. In addition to Japan there are rate decisions in Russia and Iceland


03:00 BoJ Rate Decision/Statement (e-0.1% hold)

06:00 BoJ Press Conference

07:00 UK Retail Sales

07:00 Germany PPI

09:00 Germany IFO Business Sentiment Indicators

13:30 Canada Retail Sales (MoM e0.2% p1.1%)

Sunday, 27 October 2019

Week to Oct 25th


ECB Draghi leaves, Brexit quick exit frustrated, Trade war green shoots

Mon Oct 21
Hopes of US-China trade talk success pushed SPX up today, adding 0.7% to close above 3,000 for the first time in more than a month. Other indices were also green, although DJIA gains were lower due to weak BA shares, and FTSE was hampered by the rising pound. In general currencies were up, but a fading EUR meant that DXY was flat overall. Haven assets Gold, JPY and bonds all fell. Oil was more or less flat.


Tuesday October 22
The failure of the UK parliament to confirm an accelerated Brexit deal timetable late in the day had a negative effect not only on GBP but on equity markets worldwide, which fell sharply after what until then had been a good day, although a sharp fall in TRV did not help DJIA. The only exception was FTSE which was up on the weaker pound.

It was a Turnaround Tuesday in currency markets as well, with the haven trio up, but other currencies down, so DXY showed a small gain. Oil was up on concerns about Turkey and Syria. CAD spiked down on the Canadian Retail Sales miss and partly recovered by the close.


Wednesday October 23
Stocks recovered again today, although poor earnings reports from BA and CAT capped gains and SPX closed lower than Tuesday’s high. Also TXN fell 7.5% on earnings, and pushed other chipmakers lower. DXY was down again, as the market flipped around for a second day, with all currencies except JPY (and curiously AUD) up. The JPY move was quite strong, and yet Gold was up and bonds were flat. NDX giant MSFT beat on earnings, but the reaction was surprisingly muted, both after hours and the next day. Oil was up after the EIA beat at 1530.


Thursday October 24
Mario Draghi’s final ECB meeting did not tell us anything new, as expected and after a couple of brief spikes, the single currency continued on the downward path it has taken all week. Equity markets were quiet, with SPX and NKY more or less flat, but slight gains in DAX after the ECB presser. FTSE was more sharply up in response to a strong move down in GBP following the failure of PM Johnson to get his Withdrawal bill through. The dollar was up against all currencies except Gold and JPY, reflecting the muted mood. Bonds were flat on the day. Oil carried on rising.


Friday October 25
News that the US and China are close to finalising some parts of the trade deal gave stocks a further boost on Friday, with NDX touching its July record high. Currencies were mixed, with the commodity pair CAD and AUD, and unusually Gold, also up, but others down leading to a stronger DXY. Bonds and JPY were of course down, and Oil rose in line with stocks.


WEEKLY PRICE MOVEMENT
DAX just pipped NDX to take the top spot in indices this week. GBPJPY after several solid weeks up was the weakest pair this week. Cryptos rallied after weeks of falling. Other than AAPL, the FANGs were relatively quiet.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.


NEXT WEEK (all times are GMT)
(Calendar High volatility items are in bold)

  • Fed Rate Cut expected
  • AAPL and FB report
  • Plenty of GDP and inflation data
  • Non-farm payrolls

Monday October 28
The Draghi speech is at a farewell event for the departing ECB President. Markets in New Zealand are closed for Labour Day. GOOGL earnings are released after hours. Note this is the week every fall/autumn where the US and Europe DST change is a week apart, so the US appears to open and close 'early' to European traders.

12:30 USD Chicago Fed National Activity Index 
15:00 EUR ECB President Draghi speech
17:00 GBP BoE Tenreyro speech
23:30 JPY Tokyo CPI (Core YoY e0.7% p0.5%)


Tuesday October 29
Today is the calm before the storm as a low-level set of US data will be overshadowed by rate cut expectations.

06:45 AUD RBA Governor Lowe speech
13:00 USD US S&P/Case-Shiller Home Price Indices
14:00 USD US Consumer Confidence
14:00 USD US Pending Home Sales
23:50 JPY Japan Retail Sales


Wednesday October 30
Easily the most important day of the week, with the long-awaited third rate cut of the year, and before that a CAD rate decision and numerous high-importance economic releases. Also AAPL and FB report earnings after the bell. There is also a rate decision on BRL today.

00:30 AUD Australia CPI (QoQ e0.5% p0.6%)
08:55 EUR Germany Unemployment Rate/Change
10:00 EUR Eurozone Business Climate
11:00 EUR Germany CPI (e0.9% p0.9%)
12:15 USD ADP Employment Change
12:30 USD US 19Q3 Prelim GDP (e1.6% p2.0%)
12:30 USD US PCE
14:00 CAD BoC Rate Decision/Statement (e1.75% hold) 
15:15 CAD BoC Press Conference
17:30 EUR ECB's Lautenschläger speech
18:00 USD Fed Rate Decision/Statement (e1.75% p2.00%)
19:30 USD FOMC Press Conference


Thursday October 31
Today is the Brexit deadline, unless the UK has passed the Withdrawal Act (unlikely) or the EU grants a further extension (likely, France is currently holding out). The last day of the month is also data-rich again.

02:00 CNY China PMIs
02:30 JPY BoJ Rate Decision/Statement (e-0.1% hold)
06:00 JPY BoJ Press Conference
07:00 EUR Germany Retail Sales
08:00 EUR ECB De Guindos speech
10:00 EUR Eurozone 19Q3 Preliminary GDP (YoY e1.1% p1.2%)
10:00 EUR Eurozone Unemployment Rate
10:00 EUR Eurozone CPI (Core YoY e1.0% p1.0%)
12:30 USD US PCE
12:30 USD US Jobless Claims
12:30 CAD Canada GDP (MoM, Aug)
13:45 USD Chicago PMI
23:30 JPY Japan Jobs/Unemployment


Friday November 01
NFP is of course the big event, along with the ISM PMI which is expected to recover from last month’s low. FOMC vice-chair Clarida (centrist, voter) speaks today. Markets in France, Italy and Spain are closed for All Saints’ Day.

01:45 CNY China Caixin Manuf PMI (e51.0 p 51.4)
09:30 GBP UK Markit Manuf PMI
12:30 USD US NFP/AHE/Unemp (NFP e105k p136k, AHE e3.0% p2.9%)
13:30 CAD Canada Markit Manuf PMI
13:45 USD US Markit Manuf PMI
14:00 USD US ISM Manuf PMI (e48.4 p47.8)


This report is published every week as an email by MatrixTrade.com - you can sign up to receive it here. This blog is supported solely by advertising, so if any of the ads interest you, please click on them. If you want notification when the blog is updated, please follow me on Twitter, Facebook, Stocktwits, TradingView or Linkedin (all open in separate windows). Details of how I compile the report are here.

Sunday, 20 October 2019

Week to Oct 18th


Sterling and Euro up on Brexit hopes, Fairly strong open to earnings season


Mon Oct 14
Trading was quiet on Columbus Day, with bond markets closed. Overall equities were slightly down, retreating from Friday’s euphoria.

USD advanced very slightly against most currencies but not haven assets Gold and JPY which were up.


Tue Oct 15
Earnings season opened with a raft of beats on EPS and revenue, with only GS spoiling the party. SPX added 1% and other indices were also green. A beat on the ZEW Sentiment reports at 0830 had already helped DAX earlier. A risk-on mood was clear, JPY, Gold and bonds fell sharply on the earnings reports (which come in around 1100-1200). Otherwise, currencies were mixed, with EUR and GBP rallying on reports of a new Brexit deal agreed with the EU. CAD was also up but the antipodean pair were down, as was Oil.


Wednesday October 16
With only BAC (of note) before the bell today, the Retail Sales miss at 1230 meant that the US rally did not continue, and after a pullback in early futures, SPX was flat all day, as were NKY futures. DAX did a little better, but FTSE had a second down day on GBP strength. In fact, with the exception of beleaguered NZD, all currencies, Gold and bonds were up. Oil had a brief spike up but settled flat on the day. Surprisingly, CAD was up despite the CPI miss at 1230.


Thursday October 17
Wednesday’s after hours earnings from IBM and NFLX were similar, both managed a beat on EPS, but missed on revenue, and subsidiary metrics were poor. Oddly, NFLX rallied after hours opened 6.3% up (unlike IBM which gapped down 5.5%). Such is the sentiment on growth companies versus long-established ones. However by the end of the day, both were red. Nevertheless a definite Brexit agreement announced by UK PM Johnson and the EU lifted all markets for a while, although some of this came off into the close.

The Brexit deal caused a sharp move up in all currencies (and Gold), obviously GBP, but also a sudden and sustained move in all others, even JPY. This may also have been helped by traders exiting USD on the poor Philly Fed (1230) and Industrial Production (1315) prints, the latter reporting -0.4% vs -0.1% estimated. Unusually Oil spiked up at the end of the day despite the Columbus Day-delayed EIA stock print at 1430. Yields were flat after a brief spike in line with the dollar move.


Friday October 18
The Chinese GDP miss at 0200, and start of some EU tariffs set the tone today, and lacklustre earnings from defensive stalwart KO before the bell didn’t help, and markets slid, with SPX down 0.4%. Some of this may have been OpEx related. DXY which had been failing all week, accelerated, and all currencies, although not Gold, were up. After a further rally, oil pared some on its gains, and yields were flat again.


WEEKLY PRICE MOVEMENT
NKY was this week’s best performing index, closely followed by NIFTY. GBPJPY was the top performing forex pair for a second week, adding another 2.56% to last week’s 3.24% gain. Cryptos were quiet again, and FANGS were relatively muted with only NFLX reporting.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.


NEXT WEEK (all times are GMT)
(Calendar High volatility items are in bold)

  • ECB Draghi’s swansong
  • Earnings season continues
  • Brexit saga rolls on
  • Trade war still at the fore


Monday October 21
Further talks between US TreasSec Mnuchin and USTR Lighthizer and Chinese Vice-Premier Liu He are planned this week. Also after Saturday’s defeat, further Brexit fireworks are expected in the UK parliament.

23:50 JPY Japan Trade Balance
01:30 CNY PBoC Interest Rate Decision (e4.2% hold)
06:00 EUR Germany PPI
15:00 GBP BoE Haldane speech


Tuesday October 22
Major earnings reports today are PG, TRV and UTX (together making 10% of DJIA). There is a general election in Canada. The Turkish-Kurd ceasefire agreed with the US ends. Markets are closed in Japan for a Bank Holiday. There is a rate decision on HUF, hold expected.

08:00 EUR ECB Bank Lending Survey
08:30 GBP UK PSBR
12:30 CAD Canada Retail Sales (p0.4%)
14:00 USD US Existing Home Sales (MoM)
14:30 CAD BoC Business Outlook Survey
21:45 NZD NZ Trade Balance
22:20 AUD RBA Kent speech


Wednesday October 23
Earnings are the main focus today with BA and CAT (12% of DJIA combined reporting before the bell, and MSFT and PYPL after hours. MSFT alone is is 11.26% of NDX. Markets are closed in Hungary for Republic Day

09:40 EUR DE10Y Bond Auction
13:00 USD US Housing Price Index (MoM)
22:00 AUD Aus Commonwealth Bank Manuf PMI


Thursday October 24
The main event today is Mario Draghi’s final session as ECB President, he is replaced by Christine Lagarde on Nov 1st. Another important earnings day with MCD and TWTR before the bell, and AMZN, INTC and GILD (together 13% of NDX) and V after hours. VP Mike Pence is due to speak today on US-China relations. There are also rate decisions on SEK, NOK and TRY. Turkey is expected to hike from 16.5% to 17.25%.

08:30 EUR Germany Markit PMIs
09:00 EUR Eurozone Markit PMIs
11:45 EUR ECB Rate Decision/Statement
12:30 EUR ECB Draghi Final Presser
12:30 USD US Jobless Claims
12:30 USD Capital/Durable Goods
13:45 USD US Markit PMIs
14:00 USD New Home Sales (MoM)


Friday October 25
Today sees only sentiment indicators from both Germany and the US. DJIA defensive MMM reports before the bell.

06:00 EUR Germany Gfk Consumer Confidence
08:00 EUR Germany IFO Business Expectations
14:00 USD US Michigan Consumer Sentiment Index


This report is published every week as an email by MatrixTrade.com - you can sign up to receive it here. This blog is supported solely by advertising, so if any of the ads interest you, please click on them. If you want notification when the blog is updated, please follow me on Twitter, Facebook, Stocktwits, TradingView or Linkedin (all open in separate windows). Details of how I compile the report are here.


Sunday, 13 October 2019

Week to Oct 11th


Trade war hopes at end of week, GBP soars on UK/Ireland progress


Mon Oct 07
Trade tensions continued to keep equity markets flat, or slightly down today. DAX suffered from yet another poor German Factory Orders print, although it did beat estimates.

The dollar was slightly up, but it was not even, with a flat EUR, and a slight advance on CAD. Other currencies and Gold were down. Oil and yields were slightly up.


Tuesday October 08
A US move to restrict visas for Chinese officials connected to the Muslim Uighur detentions in Western China, although not a trade move itself, was seen as a bad sign in US-China relations, and markets fell This was despite an announcement from Fed Char Powell that the Fed would recommence some QE operations. SPX was down 1.6% and other markets were similarly red. Risk assets Gold, JPY and bonds rose, and Oil fell in line with equities. DXY also ignored Powell, and was up across the board, with only NZD joining JPY in going green.


Wednesday October 09
Today’s trade war news was China’s offer to increase purchases of US agricultural goods and equity markets (and Oil) rose during the day, only to collapse over 1% suddenly after hours on a report that the US has added 28 Chinese entities to a trade blacklist. The FOMC minutes gave us nothing new, but mixed trade messages produce choppy markets, also seen in a flat DXY. All currencies (and Gold) were down except EUR, but the single currency is nearly 60% of the basket. Yields did not whipsaw, and rose gently all day.


Thursday October 10
The scheduled resumption of China trade talks, and a tweet from Trump saying he would meet Chinese VP Liu He on Friday was seen as positive, and equity markets (and Oil) were up again, and Gold, Bonds and JPY were down. Otherwise DXY was firmly down, especially after sterling rose nearly 2%, its best day for seven months, as progress appeared to be happening on the Irish border question, which is the sticking point for a Brexit deal. FTSE was therefore the only red index. US CPI printed in line with estimates and had little market effect. 


Friday October 11
All positive today on both sides of the Atlantic today. The US agreed to defer some tariffs which start next week, and described it as a ‘limited deal’. Optimism was high, and SPX ended 1.1% up after being 1.9% higher earlier in the day (ie some traders took profits).

After the British and Irish Prime Ministers said there is a “pathway to a possible deal”, the UK was even better. GBP added another 1.75% and FTSE was up 1.84%. FTSE expressed in USD (ie FTSE x GBPUSD) rose 4.76% in two days, the best two-day performance since the recovery immediately after the Brexit referendum. DOil was up in line. XY was down 0.38%, following the GBP ramp (which EUR the other player in Brexit joined). Only Gold, JPY and bonds (inverse to yields) were red against the dollar, as you would expect. CAD was particularly strong on a blowout (53.7k vs 10.0k) jobs report.


WEEKLY PRICE MOVEMENT
DAX outperformed this week adding 500 points, double the gains on other indices. We rarely see 2% weekly moves, never mind 3.24%, which was GBPJPY’s gain. Cryptos were fairly flat, and FANGs were variable, with AAPL outperforming.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.


NEXT WEEK (all times are GMT)
(Calendar High volatility items are in bold)

  • Earnings season opens
  • Trade war still in focus
  • Last chance for Brexit deal
  • China, UK, EU, Canada and NZ inflation

Monday October 14
US Bond markets are closed for Columbus Day (although the ZN future continues to trade). At some point this week, the US Treasury may release their ‘currency manipulation’ report. Canada is closed for Canadian Thanksgiving. There were local elections in New Zealand this weekend.

07:00 CNY Imports/Exports/Trade Balance
09:00 EUR Eurozone Industrial Production
12:10 GBP BoE Cunliffe speech


Tuesday October 15
Earnings season kicks off properly today, with a raft of reports from major players between 1040 and 1315, before the opening bell. The expected order is JNJ first, then UNH, JPM, GS, WFC and C. JNJ, UNH, JPM and GS together make up 17% of DJIA. As well as Bullard, we have Fed Bostic, George and Daly speaking today. Some US tariffs on China increase today.

00:30 AUD RBA Meeting Minutes
01:30 CNY China CPI (YoY e2.9% p2.8%)
08:30 GBP UK AHE/Unemployment (UE e3.9% p3.8%)
09:00 EUR Germany ZEW Economic Sentiment (e-33.4 p-22.5)
09:25 USD Fed Bullard speech
12:10 GBP BoE Vlieghe speech
14:30 NZD NZ GDT Milk Index
21:45 NZD NZ CPI (YoY e1.7% p1.7%)


Wednesday October 16
BAC report at 1045, before the bell today. After the bell we have NFLX and IBM. Fed Evans and Brainard speak today. There is a rate decision on KRW (25bp cut expected).

08:30 GBP UK CPI (e1.6% p1.7%)
09:00 EUR Eurozone CPI
12:30 USD US Retail Sales (Control Group MoM e0.4% p0.3%)
12:30 CAD Canada CPI (BoC Core YoY e1.9% p1.9%)
22:10 AUD RBA Debelle speech


Thursday October 17
Today and tomorrow sees the long-awaited EU Summit which is the UK’s last chance to do a Brexit deal, or ask for another extension, which PM Johnson does not want to do. If a deal is made, he then needs to secure a parliamentary majority to confirm it, and the UK parliament has a special session this coming Saturday to confirm or reject it. Earnings today from large but low-volatility players such as HON and PM before the bell. Fed Evans (again), Bowman and Williams speak today.

00:30 AUD Australia Jobs/Unemployment (Jobs e10.0k p34.7k)
08:30 GBP UK Retail Sales
12:30 USD US Jobless Claims
12:30 USD Philly Fed Manufacturing Survey
13:15 USD US Industrial Production
23:30 JPY Japan National CPI


Friday October 18
Today is monthly options expiration date, so expect additional volatility. DJIA components KO and AXP report before the bell, AMD report after the close. Some US tariffs on EU goods kick in today. Fed George (again), Kaplan, and vice-chair Clarida speak today.

02:00 CNY China Retail Sales
02:00 CNY NBS Press Conference
02:00 CNY China GDP
15:00 USD Fed Kaplan speech


This report is published every week as an email by MatrixTrade.com - you can sign up to receive it here. This blog is supported solely by advertising, so if any of the ads interest you, please click on them. If you want notification when the blog is updated, please follow me on Twitter, Facebook, Stocktwits, TradingView or Linkedin (all open in separate windows). Details of how I compile the report are here.


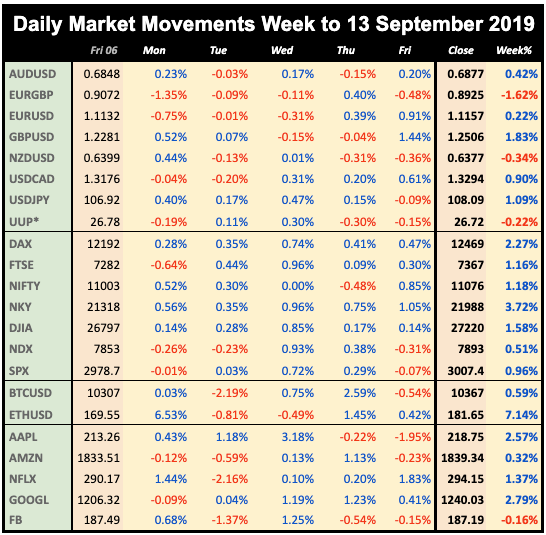
Sunday, 15 September 2019

Week to Sep 13th


ECB rate cut and QE2, Sterling rallies on Brexit deal hopes, Trump postpones tariffs

Mon Sep 09
In the absence of news, there was little action globally today, with indices more or less flat, although other markets showed a risk-on profile, with Gold, JPY and bonds firmly down, and Oil up. The exception was in the UK, where GBP rallied and of course FTSE fell, following last Friday’s success for the anti-no-deal Brexit doves, and the (accurately) predicted failure of British PM Johnson to get agreement for an election before the Brexit deadline of Oct 31. Yields were up following the Powell ’recession unlikely speech’ on Friday, a trend which continued all week.


Tuesday September 10
Another flat day in the US covering mixed action as tech fell and energy rose sharply, the latter despite a slight Oil decline. Also DJIA outperformed due to strong moves from BA and CAT. However non-US indices all rose, and Gold and JPY were slightly down in line. Other currencies were fairly flat, for once, and the real story in the US was bonds, with yields rising 11.8bp.


Wednesday September 11
A rally finally kicked in today with all markets up as investors anticipated easing in both the ECB tomorrow and the Fed next week. SPX crossed the 3,000 line, helped by a positive reception to AAPLs new cheaper iPhone and Apple TV+. Oil was up in line, helped by the EIA beat at 1530. In forex, the dollar  basket was up 0.3% with all currencies (except AUD, not part of the basket) down. Yields rose more slowly today.


Thursday September 12
Today’s bold ECB moves, cutting the deposit rate and reintroducing QE caused a huge move in EUR. It initially dipped 0.88%, but as the easing moves were less than anticipated from there added 1.47%. Notably Gold, bonds and JPY spiked up and faded more in line (to the minute) with the EUR movement, as did DAX the other way (spiked down and recovered). The US inflation beat concurrent with the ECB presser was lost in the noise. As we predicted last week, President Trump tried to tweet the dollar down by contrasting today’s ECB action with the Fed next week. Overall on the day, DXY was down 0.29%.

This was enough to fade DXY by 0.29% overall, despite JPY being slightly down, the only currency to go in that direction. Indices had received a boost the night before as President Trump postponed some Chinese tariffs as a ‘gesture of goodwill’ and were comfortably up.


Friday September 13
US indices closed flat today after an early rally, whereas DAX continued up, reflecting the ECB easing, as did NKY. FTSE was down following a very strong (1.5%) rally in GBP following a reported breakthrough in the Brexit deal talks, in that the coalition Northern Irish DUP may shift their position on the Irish backstop. A further rise in EUR meant a down day for the dollar. Gold was down and Oil flat, and yields continued upwards as they have done all week.


WEEKLY PRICE MOVEMENT
NKY came out top this week in a positive week for indices, helped of course by the 1.09% fall in the yen, which also resulted in GBPJPY being the biggest forex mover, up nearly 3%. Crypto was quiet, with ETH catching up with BTC’s gain last week. FANGs were quieter than usual, but still managed to outperform the NDX index.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.


NEXT WEEK (all times are GMT)
(Calendar High volatility items are in bold)

  • Fed rate cut expected
  • Six more rate decisions on Thursday
  • Quad-witching OpEx
  • British and Canadian inflation

Monday September 16
The weekend attack on Saudi oilfields, possibly cutting their production in half may well affect Oil, and its proxies CAD and FTSE today. Markets are closed in Japan and Mexico.

02:00 CNY Retail Sales/Industrial Production
02:00 CNY NBS Press Conference


Tuesday September 17
The important German and Eurozone sentiment indicators were surveyed before Thursday’s ECB action. ECB Coeuré speaks at 1710.

01:30 AUD RBA Meeting Minutes
09:00 EUR Eurozone ZEW Economic Sentiment
09:00 EUR Germany ZEW Survey Economic Sentiment (e-38.0 p-44.1)
13:15 USD US Industrial Production (MoM)
14:00 NZD NZ GDT Milk Index
23:50 JPY Japan Imports/Exports/TB


Wednesday September 18
Today is the big day, the US rate decision. Note that the recent bond fade has pushed back the ‘priced in’ level on a 25bp cut from 90% last week to only 80%, meaning a potential stock rally to new all-time highs if the cut is delivered, unless of course Powell accompanies it with hawkish rhetoric. Also today GOOGL, FB and TWTR testify before the senate about content control. There is also a rate decision on BRL.


08:30 GBP UK CPI (YoY e1.9% p2.1%)
09:00 EUR Eurozone CPI
12:30 USD US Housing Starts/Building Permits
12:30 CAD Canada CPI (BoC Core p 2.0%)
18:00 USD Fed Rate Decision (e2.0% p2.25%)
18:30 USD Fed Chair Powell Presser
22:45 NZD NZ19Q2 Final GDP (QoQ e0.4% p0.6%)


Thursday September 19
After the Fed have made their decision, there are six more rate decisions today, as there are also decisions on NOK, IDR and ZAR. The most important is GBP, not so much for the hold, but the committee vote (the UK version of ‘dot-plot’) and its effect on the now volatile sterling. Markets are closed in Chile today.

01:30 AUD Aus NFP/UnEmp (e10k/5.3% p41.1k/5.2%)
02:00 JPY BoJ Rate Decision/Statement (e-0.1% hold)
06:00 JPY BoJ Presser
07:30 CHF SNB Rate Decision/Statement (e-0.75% hold)
08:30 GBP UK Retail Sales
11:00 GBP BoE Rate Decision/Statement (e0.75% hold)
12:30 USD US Jobless Claims
12:30 USD Philly Fed Manufacturing Survey
14:00 USD Existing Home Sales (MoM)
23:30 JPY Japan National CPI


Friday September 20
Markets will still probably be reacting to the interest rate moves but today is monthly and quarterly Opex, sometimes called quad-witching (the daily, weekly, monthly and quarterly options all expire). It’s quite important, as index future options are mainly traded quarterly. For example SPX December 19 open interest is over double that of October and November monthlies. Note also an opportunity on CAD, their rate decision was last week, but if Wednesday’s inflation moves CAD hard, Friday’s retail sales (if one is a beat and the other a miss) may well exactly reverse it.

06:00 EUR Germany PPI
08:30 GBP UK PSBR
12:30 CAD Canada Retail Sales (MoM e0.8% p0.0%)


This report is published every week as an email by MatrixTrade.com - you can sign up to receive it here. This blog is supported solely by advertising, so if any of the ads interest you, please click on them. If you want notification when the blog is updated, please follow me on Twitter, Facebook, Stocktwits, TradingView or Linkedin (all open in separate windows). Details of how I compile the report are here.