Showing posts with label COVID. Show all posts

Sunday, 28 November 2021

Week to Nov 26th

Omicron scare means worst day of year on Black Friday for equities and Oil
MY CALL THIS WEEK : BUY NZDJPY

LAST WEEK


After a quiet three days in the run-up to Thanksgiving, market, markets showed how extended they were by a strong collapse on Friday, the worst one day drop of 2021 for equities and Oil. Gold once again showed its unreliability as a safe haven. A flat week for copper showed how the NDX drop (more than DJI) may have been more to do with their relative overbought conditions than the COVID news. The dollar had a flat week, although JPY and bonds rallied on the equity drop. 


WEEKLY PRICE MOVEMENT


The biggest index mover was DAX, down 5.59%. The top forex mover was NZDJPY this week, down 3.37%. Bitcoin and Ethereum were down again, and FANGs reflected general NDX movement.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.


NEXT WEEK


As markets were still depressed on Friday, the COVID omicron variant is likely to depress markets as long it stays in the news. However, it is a new month and therefore NFP week. The mid-range estimate of 550k is close to the ADP figure which may change the mood, depending on course on further Omicron information. The week is heavy with Central Bank speeches including Fed Chair Powell's testimony to the Senate COVID committee on Tuesday.


Other than that, we have a raft of PMIs, including the most important ISM pair, German and European inflation, the latter's core still not exceeding 2%, and GDP from commodity pair Australian and Canada.


CALENDAR  (all times are GMT)


Monday November 29

23:50 Japan Retail Sales (Sun)

08:30 BoJ's Governor Kuroda speech

10:00 Eurozone Confidence Indicators

13:00 Germany CPI (e5.4% p4.6%)

13:30 Canada Current Account

15:00 US Pending Home Sales

19:00 BoC Governor Macklem speech

19:00 BoC Schembri speech

20:05 Fed Chair Powell speech

22:05 Fed Bowman speech

22:05 RBA Debelle speech

23:30 Japan Jobs/Unemployment

23:50 Japan Industrial Production


Tuesday November 30

00:30 Aus Building Permits (MoM)(Oct)

01:00 China PMIs (Mfr 49.6 p49.2)

08:55 Germany UnEmp Rate/Change

10:00 Eurozone CPI (Core YoY e1.9% p2.0%)

10:15 ECB Weidmann speech

13:30 Canada Q3 GDP (QoQ e2.5% p-1.1%)

14:00 US Housing/Home Price Indices

14:45 Chicago PMI

15:00 US Consumer Confidence

15:00 Fed Chair Powell testimony

18:00 Fed Clarida speech

21:30 Aus AiG Performance of Mfg Index


Wednesday December 1

00:30 Aus Q3 GDP (QoQ e-2.7% p0.7%)

01:45 China Caixin Mfr PMI

07:00 Germany Retail Sales (YoY e-2% p-0.9%)

08:55 Germany Markit Mfr PMI

09:30 UK Markit Mfr PMI

12:00 BoE Governor Bailey speech (time approx.)

13:15 US ADP (e525k p571k)

14:30 Canada Markit Mfr PMI

14:45 US Markit Mfr PMI

15:00 US ISM Mfr PMI (e61 p60.8)

19:00 Fed Beige Book


Thursday December 2

00:30 Aus Imports/Exports/TB (TB e11Bn,p12.2Bn)

10:00 Eurozone Unemployment Rate

13:30 US Jobless Claims

21:30 Aus AiG Performance of Construction

22:00 Aus Commonwealth Bank Svcs PMI


Friday December 3

01:45 China Caixin Services PMI

08:55 Germany Markit PMI Comp

09:00 Eurozone Markit PMI Comp

10:00 Eurozone Retail Sales (YoY e1.5% p2.5%)

13:30 US NFP/AHE/UnEmp (NFP e550k p531k)

13:30 Canada NFP/UnEmp (UnEmp p6.7%)

14:45 US Markit Svcs/Comp PMIs

15:00 US ISM Svcs PMI (e65.5 p66.7)

Sunday, 21 November 2021

Week to Nov 19th

NDX ATH, Sterling rallies, Austria lockdown
MY CALL THIS WEEK : SELL EURAUD


THIS WEEK


This week saw beats (not necessarily good) on US Retail Sales and UK inflation. The latter buoyed sterling, the only currency to beat the dollar. This made FTSE the week's worst performing index. News of rising continental European COVID cases and a full lockdown in Austria made EURGBP the largest forex mover, hitting 2020 lows.

Increased volatility led to extremes in the NDX and the dollar. The tech index hit new all-time highs, and also the NDX/DJI ratio reached its highest level since 2000. At 0.465, the ratio is only 1% below the 0.47 spike on Mar 13, 2000, a level it only held for half a day. (The low was 0.11 on 24 Sep 2002). DXY had its strongest week for five months, and hit a 16 month high, with EUR recording the same periods for lows. Gold had its best week in two months, and made new 5-month high, before fading as the dollar rallied mid-week. Yields and Gold largely followed the dollar.


WEEKLY PRICE MOVEMENT

The biggest mover for a third week was FTSE, down 1.69% on a strong pound. The top forex mover was EURGBP this week, down 1.71%. Bitcoin and Ethereum were down sharply, whereas FANGs performed well, in line with NDX.

Last week’s EURGBP short made 1.71%, taking my year to date profit to 7.90% and 31/45 wins. This week I am selling EURAUD.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.


NEXT WEEK

The week ahead is foreshortened to three and half days in the US, with Thanksgiving and the half-day on Black Friday which opens the holiday season. The minutes of the last FOMC meeting are published and there are interest rate decisions in China and New Zealand. Otherwise it is a fairly quiet week for important data.


CALENDAR  (all times are GMT)

Monday November 22
01:30 PBoC Interest Rate Decision (e3.85% hold)
13:30 Chicago Fed National Activity Index
15:00 Eurozone Consumer Confidence
22:00 Aus Commonwealth Bank PMIs

Tuesday November 23
08:30 Germany Markit PMIs (Mfr e56.7 p57.8)
09:00 Eurozone Markit PMIs (Comp e53.1 p54.2)
09:30 UK Markit Mfr/Svcs PMIs (Svcs 58.5 p59.1)
11:00 BoE Haskel speech
14:45 US Markit PMIs
18:00 BoC Beaudry speech
22:15 RBA Bullock speech

Wednesday November 24
00:40 RBA Bullock speech
01:00 RBNZ Rate Decision/Statement (e0.75% p0.5%)
02:00 RBNZ Press Conference
09:00 Germany IFO Sentiment Indicators
12:45 UK Autumn Budget
13:30 US Durable/ND Capital Goods (NDC Oct e0.6% p0.8%)
13:30 US Jobless Claims
13:30 US Q3 GDP Annualized (e2.1% p2.0%)
15:00 US PCE QoQ
15:00 Michigan CSI
15:00 US New Home Sales (MoM)(Oct)
19:00 FOMC Minutes

Thursday November 25
07:00 Germany GDP
12:30 ECB MPC Accounts
23:30 Tokyo CPI

Friday November 26
00:30 Aus Retail Sales (MoM e2.5% p1.3%)

Monday, 26 April 2021

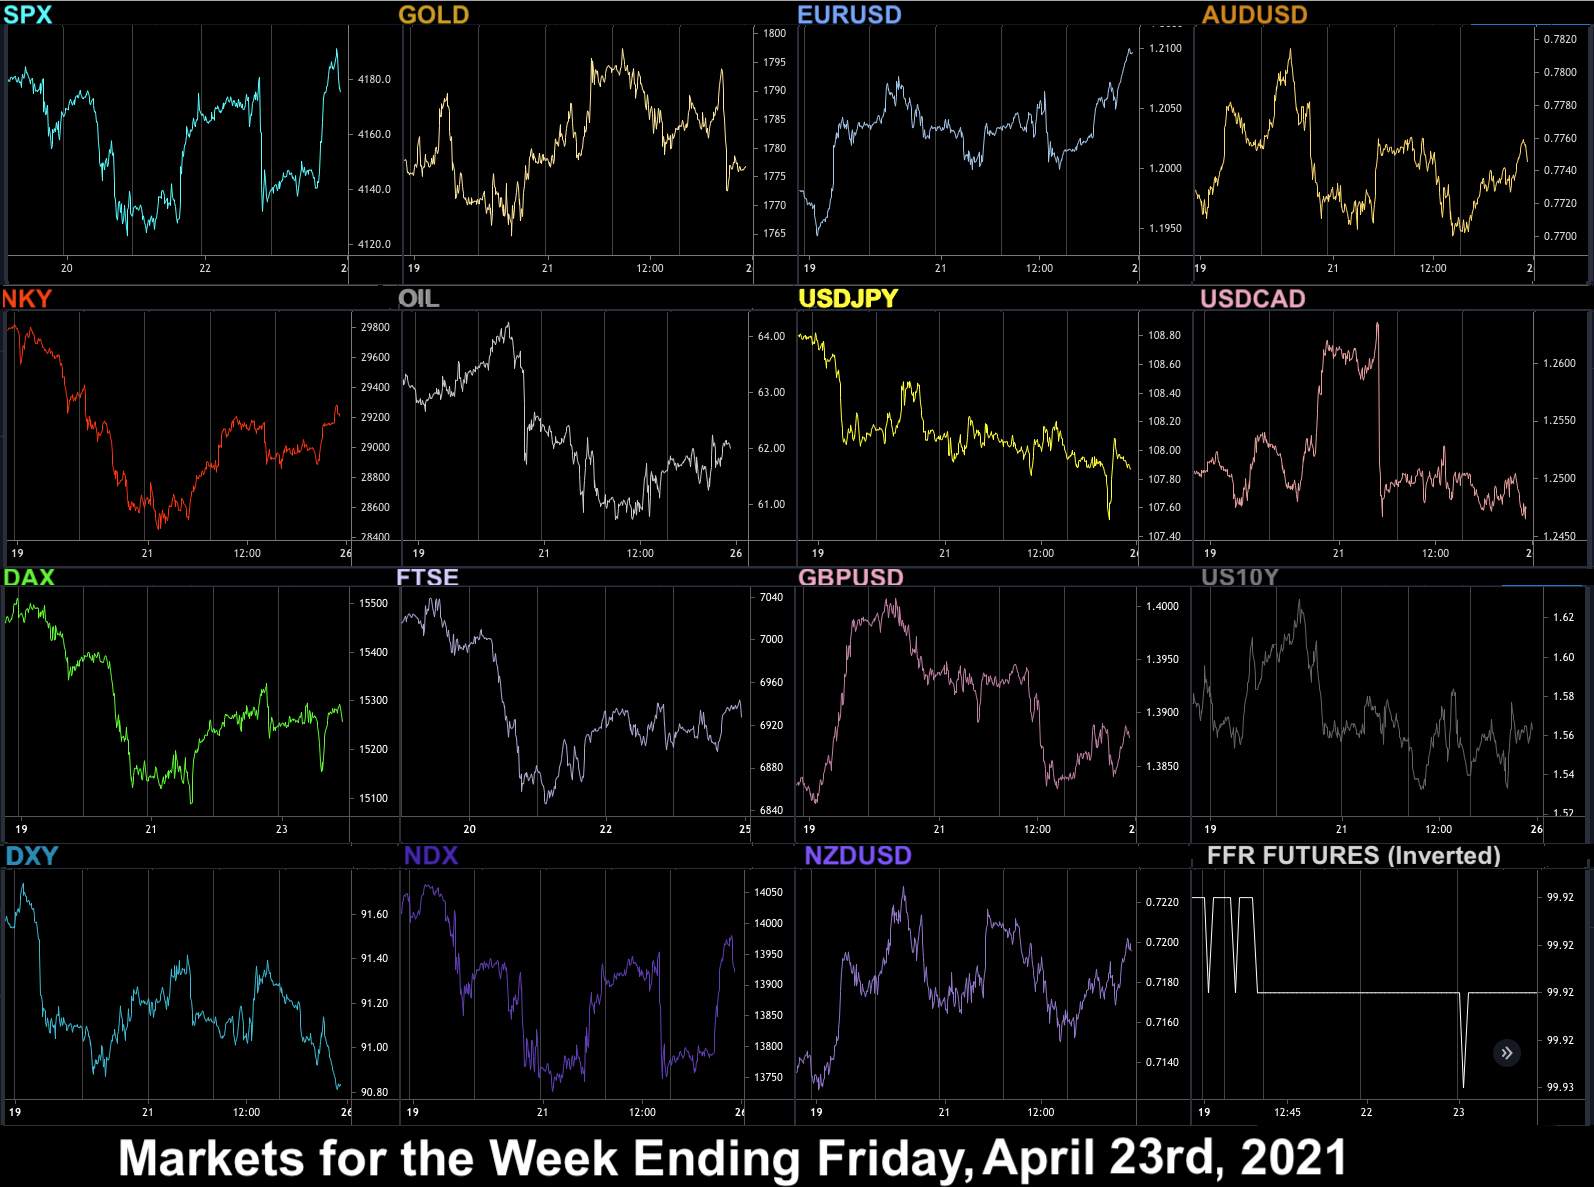
Week to Apr 23rd

Earnings season falters slightly, Surprise BoC QE cut and hike hint, Biden CGT hike shocks traders

MY CALL THIS WEEK : SELL AUDUSD


This week saw an early two-day 1.2% pullback on the continuing rise in COVID-19 in emerging market countries, particularly India, and overall global deaths reaching the psychological 3M level. US companies are active everywhere in the world, and so vaccine and re-opening progress at home is not the whole story. For many companies, recovery and consequent fiscal tightening at home, coupled with depressed international markets is a lose-lose situation. India, a country with four times the population of the US is particularly hard hit with a third wave.


News of the Biden capital gains tax hikes on Thursday, which will particularly hit the trading community, caused an instant 1% drop in US equities. NFLX failed to meet subscriber estimates and fell 7.5%. Nevertheless, and even despite a slight uptick in volume, the week was generally a V-shaped consolidation, even briefly eking out a new SPX intraday high on Friday. FTSE, DJIA and yields posted inside weeks, and most other instruments ended with extremely small candle bodies.


Next week sees an important Fed meeting, with a strong vaccine rollout, and re-openings continuing, with there be any hint of QE taper, or even more extreme, a rate hike. Also we see companies comprising over 40% of NDX reporting, which could have a noticeable effect on the DJI/NDX ratio. These two factor will undoubtedly overshadow most other data, except perhaps PCE, the Fed’s preferred method of inflation measurement.


Given that there is a slight risk of a hike, the ‘dovish message’ bar is set fairly low this month, and traditionally, there is one more week before the traditional seasonal selloff.


Mon Apr 19

The coronavirus death toll passed a symbolic three million at weekend, and markets fell today, with NDX underperforming. The SPX drop of 0.53% was the worst for a month, and NDX fell 0.96%. As developing nations suffer a larger third wave, international company sales suffer, whereas fiscal policy is led by the US recovery. The dollar also fell to a six-week low. Surprisingly Gold also fell, and Oil rose slightly.


Tue Apr 20

Market did their second red day in a row for the first time since late March today, after only mild beats on major earnings and a downbeat ECB Bank Lending survey. A textbook risk-off day, with NDX underperforming and Gold, bonds and the safe-haven dollar up, and Oil down. The theme was continued after the bell with NFLX falling 7% on lacklustre new subscriber numbers.


Wednesday April 21

After a two-day 1.2% pullback, market snapped back today with RUT leading the way, up 2%. NDX underperformed, and Gold rose 1% and Oil dropped again, so it was only a reaction to the earlier part of the week, rather than a change in mood. The dollar would have risen except for a 1.46% appreciation in an hour in CAD, after the BoC announced something unheard of at the moment, a reduction in QE (although this was only correcting a large drop on Tuesday). Bond yields were flat on the day.


Thursday April 22

As markets were starting to recover, the news of President Biden’s potential doubling of capital gains tax to 40% for millionaires hit the mood of traders (the ones who would pay it) hard. SPX dropped 1% instantly and stayed down until the close. The news came after Europe closed, leaving DAX and FTSE green. The safe-haven dollar rose, and this time Gold fell and Oil rose, following the dollar. Bonds were once again flat.


Friday April 23

Today, markets realised that values are not linked to traders’ tax bills. The 1% drop was recovered in the morning session, and SPX briefly touched a new high of 4196.20. NDX outperformed. USD reversed back down as did Gold and Bonds. Oil was up, so all in line, just like Tuesday in reverse.


WEEKLY PRICE MOVEMENT

Markets down this week, with NKY showing the biggest loss. The top mover was EURAUD up 0.98%. BTC fell sharply by $10,000 although ETC did not. FANGS were flat, pre-earnings, except of course NFLX.


My strategy of reversing the most extreme pair worked for a third week, but only by a lousy 0.01%, taking the total to -0.79%, 11/15 wins. I will try the same pair for another week, selling AUDUSD.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.


NEXT WEEK (all times are GMT)

(Calendar High volatility items are in bold)


  • Key NDX earnings week
  • FOMC Rate Set meeting
  • Rate decisions in Japan and Sweden
  • End of month before May


Monday April 26

The final week before ‘Sell in May’ starts, so watch out all week for front-running given that SPX is at all time highs. Not much during the daytime, but cult stock TSLA (4.35% of NDX) reports after the bell. Markets are closed in Australia for ANZAC day observed.


05:00 Japan Leading Economic Index(Feb)

08:00 German IFO Business Sentiment

12:00 ECB Panetta speech

12:30 US Durable/ND Capital Goods (Durable e2.5% p-1.2%)

13:00 ECB Lane speech


Tuesday April 27

Key earnings today after the bell are NDX giants MSFT and GOOGL (together 13.64% of NDX). As well as Japan, there are rate decisions in Sweden and Hungary today. SEK is  4.2% of the DXY basket. Markets are closed in South Africa and The Netherlands.


05:00 BoJ Rate Decision/Statement (e-0.1% p-0.1%)

08:00 BoJ Press Conference

15:00 US Housing/Home Price Indices

16:00 US Consumer Confidence(Apr)

22:00 BoC Macklem speech

23:50 Japan Retail Sales


Wednesday April 28

Today is FOMC day, and for the first time in months, a hold is not 100% priced in, there is a 2.8% chance of a hike, according to the CME FedWatch tool. Traders will be looking for any hint of QE taper, now the vaccine program is well established. The largest company in the world AAPL reports after the bell, along with FB make up 14.9% of NDX. So a big day, near the end.


01:30 Australia CPI (RBA Trimmed Mean QoQ e0.5% p0.4%)

06:00 Germany Gfk Consumer Confidence Survey(May)

10:00 OPEC Meeting

12:30 Canada Retail Sales (e-3%, p-1.1%)

14:00 ECB President Lagarde speech

18:00 Fed Rate Decision/Statement (e0.25% hold)

18:30 FOMC Press Conference


Thursday April 29

A lot of data, but most of it low-level. Markets are more likely to be influenced by the Fed and AAPL. Today it is the turn of AMZN (8.47% of NDX) to report after the bell. There is a rate decision in Egypt. Markets are closed in Japan for Showa Day.


07:30 ECB De Guindos speech

07:55 Germany UnEmp Rate/Change

08:00 Eurozone Economic Bulletin

09:00 Eurozone Consumer Confidence/Business Climate

11:30 ECB Weidmann speech

12:00 Germany CPI (e2% p2%)

12:30 US PCE QoQ

12:30 US Jobless Claims

12:30 US Q1 GDP Prelim (e6.5% p4.3%)

14:00 US Pending Home Sales (MoM)(Mar)

18:00 Fed Williams speech

23:30 Tokyo CPI

23:30 Japan Jobs to Applicants/Unemployment

23:50 Japan Industrial Production


Friday April 30

Oil earnings today, with the two halves of Rockefeller’s empire CVX and XOM reporting, along with PSX. XOM left the Dow last year, despite once being the biggest company in the world. There may be end of month volatility, including front running a May sell-off. There is a rate decision in Colombia. Markets are closed in Greece and Romania for Orthodox Good Friday, and Denmark.


01:00 China NBS PMIs (Mfr e51.4 p51.9)

06:00 Germany Q1 GDP Prelim (p0.3%)

09:00 Eurozone CPI (Core e0.9% p0.9%)

09:00 Eurozone Q1 GDP (QoQ e-0.8%  p-0.7%)

09:00 Eurozone Unemployment Rate(Mar)

12:30 US PCE MoM/YoY

12:30 US GDP MoM

13:45 Chicago PMI

14:00 Michigan CSI

Sunday, 3 January 2021

Review of 2020

 The year of COVID, New US President, Interest Rates to zero, Bitcoin triples


The China trade war took a back seat as the year was dominated by the effect of COVID-19 on the economy, the degree of lockdown, and the stimulus measures used to keep markets and confidence afloat. Against this, what would normally be the principal event of the year, the presidential election, almost seemed like a sideshow. Markets saw their fastest deep crash since 1987 or even 1929, but rebounded fairly quickly, particularly in the tech sector, where a move on online work and life produced COVID winners old (AMZN, NFLX) and new (ZM). European indices fared much worse, not helped by currency appreciation, with DAX only flat for the year and FTSE down. The dollar was down on the year, and the yen even more reflecting the strong equity rally. AUD was the top currency, reflecting its lighter COVID burden, but the outstanding performer was Bitcoin, whose value tripled, in a rally reminiscent in season and scale of 2017.


January 2020

The year started with the China Phase 1 trade agreement in place and strong earnings, and new all-time highs were reached on the 13th. However we then got the first inklings of COVID-19 from Wuhan, China at the end of the month, and the market pulled back to close slightly down. The Iranian assassination incident on the 3rd initially spiked Oil, which then pulled back sharply when the Iranians didn’t retaliate, and the black stuff was down 15%. In line with the negative moves in equities and Oil, we saw Gold, bonds and yen all appreciated materially. Of course much more was to come …


February 2020

News that would normally substantially move markets, such as the Trump impeachment acquittal and Joe Biden losing the Iowa Caucus (leaving the possibility of left-wing Bernie Sanders as the Dem candidate) was all ignored as the world woke up to the seriousness of COVID-19. South Korea declared an emergency, Italy suspended China flights, and companies started to revise their guidance. Equity and Oil markets tumbled (SPX -8.41%, CL -12.28%) mostly in the final week which was the worst in decades. Bonds soared as a safe haven, but against a flat dollar, Gold was up less than 5%, an early inkling of its reduced value as a risk indicator.


March 2020

This was the worst month in decades, and the quickest drop in history, as the seriousness of COVID was shown in Italy. On 3rd, the Fed made a 50bp emergency cut, which has little effect, so on 16th, cut the rate to zero, which arrested the drop. The low point for SPX was 35.2% below the February high, only 23 days earlier. Oil’s drop was even more momentous, over 50% down in the same period. Further QE stimulus was announced on the 20th. The final week’s bounce back up (+12%) was the best week for SPX since 1938. Also this month (4th) Joe Biden won Super Tuesday, confirming his nomination for the Presidential race, and virtually the entire western world went into lockdown. As you would expect, bonds soared again, with the 10-year rate dropping 48.4bp to 0.668%.


April 2020

Strong lockdowns inevitably arrested the rise in COVID cases, and markets did not return to the March lows. The first week posted the worst initial jobless claims number in history, and the worst NFP since 2009 (-1.373M). Earnings estimates had all been revised down sharply in February and March, and although many companies reported earnings between a third and two thirds lower than Q4/19, stocks steadily rose throughout the month, helped by even more QE stimulus on 9th. Also seen this month was noticeable lockdown rotation, stocks such as NFLX recovered extremely quickly (it had beaten its March low by Apr 14), whereas aviation and travel stocks languished at around a quarter of their pre-lockdown highs. SPX closed up 12.68%, although failing to recover all of March’s fall.


The dollar was stable, ending the month flat. However, the contagion spread to other assets, with Gold up 7%, and the amazing story of Crude Oil. After the momentous drop in March, so much pressure was put on the near (May-20) contract that on the day before expiration, it actually moved into negative territory for a few hours, as low as minus $37.63 a barrel. The next day, the June contract fell 70% to $6.50, prices not seen for decades.


May 2020

There was no ‘Sell in May’ this year, except for the first day, as markets were still largely oversold after the March crash. This despite the worst NFP report, by an order of magnitude, over 20 million jobs lost in April. Warren Buffett exited the airline sector, a sign that he doesn’t see even a medium-term recovery. Markets fell in Hong Kong, not on COVID, which they were handling well, but on the new Beijing-inspired security laws. However there was a glimmer of hope, as MRNA reported successful vaccine trials. Overall SPX was up a modest 4.5%, but Oil made a much faster recovery, up 73% on the month. Once again the dollar (-0.75%) was flat and Gold (+2.61%) was up.


June 2020

After two months of lockdown with the inevitable fall in COVID cases, markets were cautiously optimistic, especially with a reversal in the NFP situation. The print of +2.725 million was the best since records began in 1939, and other macro metrics had improved. Also the ECB added €600Bn of QE, and crucially the White House did not escalate the trade war due to the Hong Kong situation. Nevertheless there were setbacks, for example a spike in Texas and California cases caused a 7% market drop on 12th, and SPX only added a modest 1.84% for the month, but 19.95% for the quarter, the best quarter for decades. Lockdown equals online, and online equals tech, and NDX added 6.29% fully covering the March dip and posting new all-time highs. Other assets were similar to May, the dollar again fell only slightly (-0.93%), Gold was up 3.07%, and Oil continued its fast recovery adding 12.4%.


July 2020

Further good news this month led to a smooth rise in equity markets. BNTX announced successful vaccine trials (we now know this as the PFE vaccine), and MRNA confirmed further success. Shares in both these companies soared. Also the NFP print made yet a new record, adding 4.8M jobs, and the Fed made more dovish noises. Markets continued to rotate into COVID-proof tech stocks, with NDX adding 7.37% vs 5.51% for SPX. The Fed policy did however finally trigger a large drop in USD, with DXY falling 4.03%. The underlying fragility of the recovery, plus the dollar move meant that Gold added 10.83% and made new all-time highs after 11 years.


August 2020

August saw the inflation rules changed at the virtual Jackson Hole conference, a dovish move, more stimulus was discussed in Congress, and Russia announced a working vaccine. The Democrats selected Joe Biden as their candidate, not the left-wing Bernie Sanders. All positive and SPX duly rose again up 7.42% with considerable outperformance from NDX up 13.58%, as good as April, the first recovery month. SPX recovered the COVID drop on 21st making a new ATH. Oil rose 5.19%. Gold consolidated, as did the dollar, only dropping 1.39% after the large fade in July.


September 2020

In September, a ‘whale’ buyer (Softbank) was discovered as part of the reason for the substantial NDX outperformance over summer, and there was a sharp pullback in the first three weeks of the month, but mostly the days into and after Labor Day. A lot of this was a ‘healthy correction’, as NDX had reached an RSI level of 81, the highest since Dec 2019, and the DJI/NDX ratio fell to 2.32 on Aug 31, the lowest since March 2000, and the second only time since NDX was created in 1986. AAPL and TSLA had performed splits, which distorted DJIA, and the Fed was insufficiently dovish at their meeting on the 16th. SPX was down over 10% and NDX 14% by the 21st, and only a statement to Congress by Chair Powell saying that further stimulus was needed, a point unusually echoed by a raft of Fed speakers that week, and supported by Speaker Pelosi, reversed the decline and SPX ended the month 4% down. NDX was down 6.5% and the DJI/NDX ratio rose 3.65%, the highest since October 2018, setting the stage for a bottom in that ratio and the COVID-driven almost daily rotation we have seen since. The only other good news was successful trials of the AZN/Oxford vaccine. The equity drop caused a slight dollar recovery, up 1.79%, and Gold followed that with a 4% drop. Oil followed equities and declined 6.32%


October 2020

This was of course the month before the election, and when not pre-challenging the election result in advance, the President caught and quickly recovered from COVID, mentioned stimulus being delayed post-election, but then came up with a figure ($1,200 for every American). The Biden lead did not advance, but COVID cases most certainly did. However there was positive news in that PFE, then MRNA, then AZN announced on consecutive Mondays that their vaccine was very (ie 90% or more) effective, and also we had Thanksgiving, and the rally that usually accompanies it, which finally made a new ATH for DJI. Nevertheless, this good news balanced uncertainly about COVID cases, the stimulus and the election, and led to a stalemate, ie a consolidating month in both SPX (-2.77%), the dollar (0.25%), and Gold (-0.42%). Only Oil collapsed, down 10%.


November 2020

Joe Biden won the election, eventually, although the Senate remained undecided until Georgia run-off elections on Jan 5. The election was called for Biden over the weekend 7/8, although President Trump refused to concede (and still has at the time of writing). Of more importance, PFE announced before the 9th Monday bell that their vaccine (formerly the BNTC vaccine) trials were complete and was over 90% effective. DJIA futures rose 4% in seconds (finally hit a new ATH), and most notably NDX dropped sharply, the quickest rotation every seen. This happened twice on the following two Mondays for the MRNA and then the AZN vaccines, with similar effects. This was enough to drive optimism into Thanksgiving at which point seasonal sentiment took over. History may well show a Biden election rally but careful examination of timing on Mon 9th show that was not the cause. The month end shows a rare situation where SPX was up 10.75%, its best month since April, but NDX was down, as money moved out of COVID-immune tech back into the battered and underpriced defensive sectors. The dollar and Gold continued to consolidate in their 3% (dollar) and 6% (Gold) ranges, although following the vaccine rally, Oil was up 25%.


December 2020

The Santa Rally took over, with a healthy gap up on the first day and with the vaccine program underway, equity markets rose in waves throughout the month. The finalisation of the Brexit deal also helped. However, set backs such as the new more virulent strain of coronavirus on 21st, created pullbacks and SPX only managed to add 3.71% for the month, although NDX did better, both making new highs, a sign that seasonal sentiment was more important than COVID. On 17th, Bitcoin broke through its 2017 high, also co-incidentally on 17th Dec. It carried on, ending up at triple its 2019 closing value. Oil added 7.04% although it still ended 21% down on the year. The dollar continued to make new 30-month lows, ending the year 6.85% down, with all currencies up. Gold continued to fall on the weaker dollar, adding 5.74%, and ending up a better investment than SPX (although not NDX) for the year.


Saturday, 26 December 2020

Week to Dec 25th

Short Christmas week, New COVID strain, Brexit and US stimulus deals agreed
MY CALL THIS WEEK : SELL EURCAD

Despite the fact that it was the final short week before the holidays, and macro data was unsurprising, there were three big news items: the new more infectious COVID variant, the US stimulus deal finally agreed, and at the very close of the week, the long-awaited Brexit deal. All markets reacted to the first, only currencies to the second, and only GBP to the last as markets closed on Thursday lunchtime, although there was some more movement in currencies on Christmas Day, notable in EURGBP. Nevertheless the net effect was a fairly flat week, with no index moving more than 1%, as neither did any other asset except GBP and Oil.


Next week is the traditional core Santa Rally, and equities are expected to rise in thin trading, as many traders take the week off. London has an extra day off, so low volumes of forex trading plus the digesting of the full Brexit deal may produce some strange moves as seen on Christmas Day. Again macro news is slight. There may also be some year end last minute rebalancing (which means winners go up further and losers fall further)


I hope you have a happy Christmas and prosperous New Year.


Mon Dec 21
Equity and Oil Markets pulled back today on news of a new, more transmissible strain of coronavirus discovered in the UK and South Africa. The sell off held in Europe, but later trading in the US trimmed US losses and DJIA even managed to close slightly positive. After weeks of decline, the dollar perked up and was up across the board against all currencies and Gold. Bonds were flat on the day.


Tuesday December 22

Good news today as Congress finally passed the stimulus package. Also the WHO confirmed that the vaccines would still work against the new COVID variant. Europe recovered some of yesterday’s losses, and there was a slight rotation into NDX (up) from DJI and SPX (down). However Oil was down on the day, bonds were up, and JPY was up against all currencies except USD, which was strong after the stimulus news. Gold fell on dollar strength. So a mixed response really.


Wednesday December 23

Today was flat for SPX, with DJI and NDX reversing Tuesday’s rotation. Europe continued to recover from Monday’s drop, even against currency rises as the dollar gave up its rally and turned south, posting red candles against Gold and all currencies except JPY, which fell with bonds. Oil was also up on this overall positive day.


Thursday December 24

Germany was closed, and London and New York only did half-days today. However, the Brexit deal was confirmed before markets closed, and the notable movement was a rise in GBP and consequent fall in FTSE. Otherwise equity and Oil markets were up as Santa sentiment continued. The dollar was flat overall, as JPY fell to balance the GBP rise. Surprisingly though, Gold and bonds were up.


Friday December 25

Today was Christmas Day and markets everywhere except Japan and China are closed. There were however, notable moves in forex, with EURGBP adding 1.74% as the GBP rally fizzled out.


WEEKLY PRICE MOVEMENT

Indices were flat this week, with the biggest mover FTSE down 0.41% on GBP strength before Friday. Cable was the biggest mover down 1.27% on the week, the entire move being made on Christmas Day. Bitcoin made a new ATH on Christmas Day, and is outperforming Ethereum. FANGS were very mixed, with AAPL outperforming, up 4.19%.


My USDCAD trade worked, up 0.64%, moving my running total to 8.67% and 24/41 wins. This week I am selling EURCAD. Last week’s candle up was much larger than usual and I am looking for reversion to mean.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.


NEXT WEEK (all times are GMT)

(Calendar High volatility items are in bold)


Monday December 28

The US re-opens in what is traditionally a very strong three and half days, the core Santa Rally. The UK, Canada, Hong Kong and Australia are closed for Boxing Day observed.


23:50 Japan Industrial Production (Sun)


Tuesday December 29

The rest of the world markets open, the first day since the Brexit deal announced late on Christmas Eve. This should prove positive to markets, but there may be some sector variance (eg automobiles, the core part of DAX).

14:00 US S&P/Case-Shiller Home Price Indices


Wednesday December 30

Today is the UK Parliamentary Vote on Brexit deal, however it expected to pass easily as the opposition Labour Party have confirmed they will vote with the government.


07:00 Germany Retail Sales

14:45 Chicago PMI

15:00 US Pending Home Sales


Thursday December 31

The final day of 2020 may see some volatility through portfolio rebalancing. However, as most markets close at lunchtime, general trading is expected to be thin. Germany is closed for Silvester (New Year’s Eve)


01:00 China PMIs

13:30 US Jobless Claims


Friday January 1

All markets globally are closed today for New Year’s Day.