Showing posts with label EURCAD. Show all posts

Sunday, 3 July 2022

Week to Jul 1st

Markets back down again
MY CALL THIS WEEK : BUY EURCAD


LAST WEEK

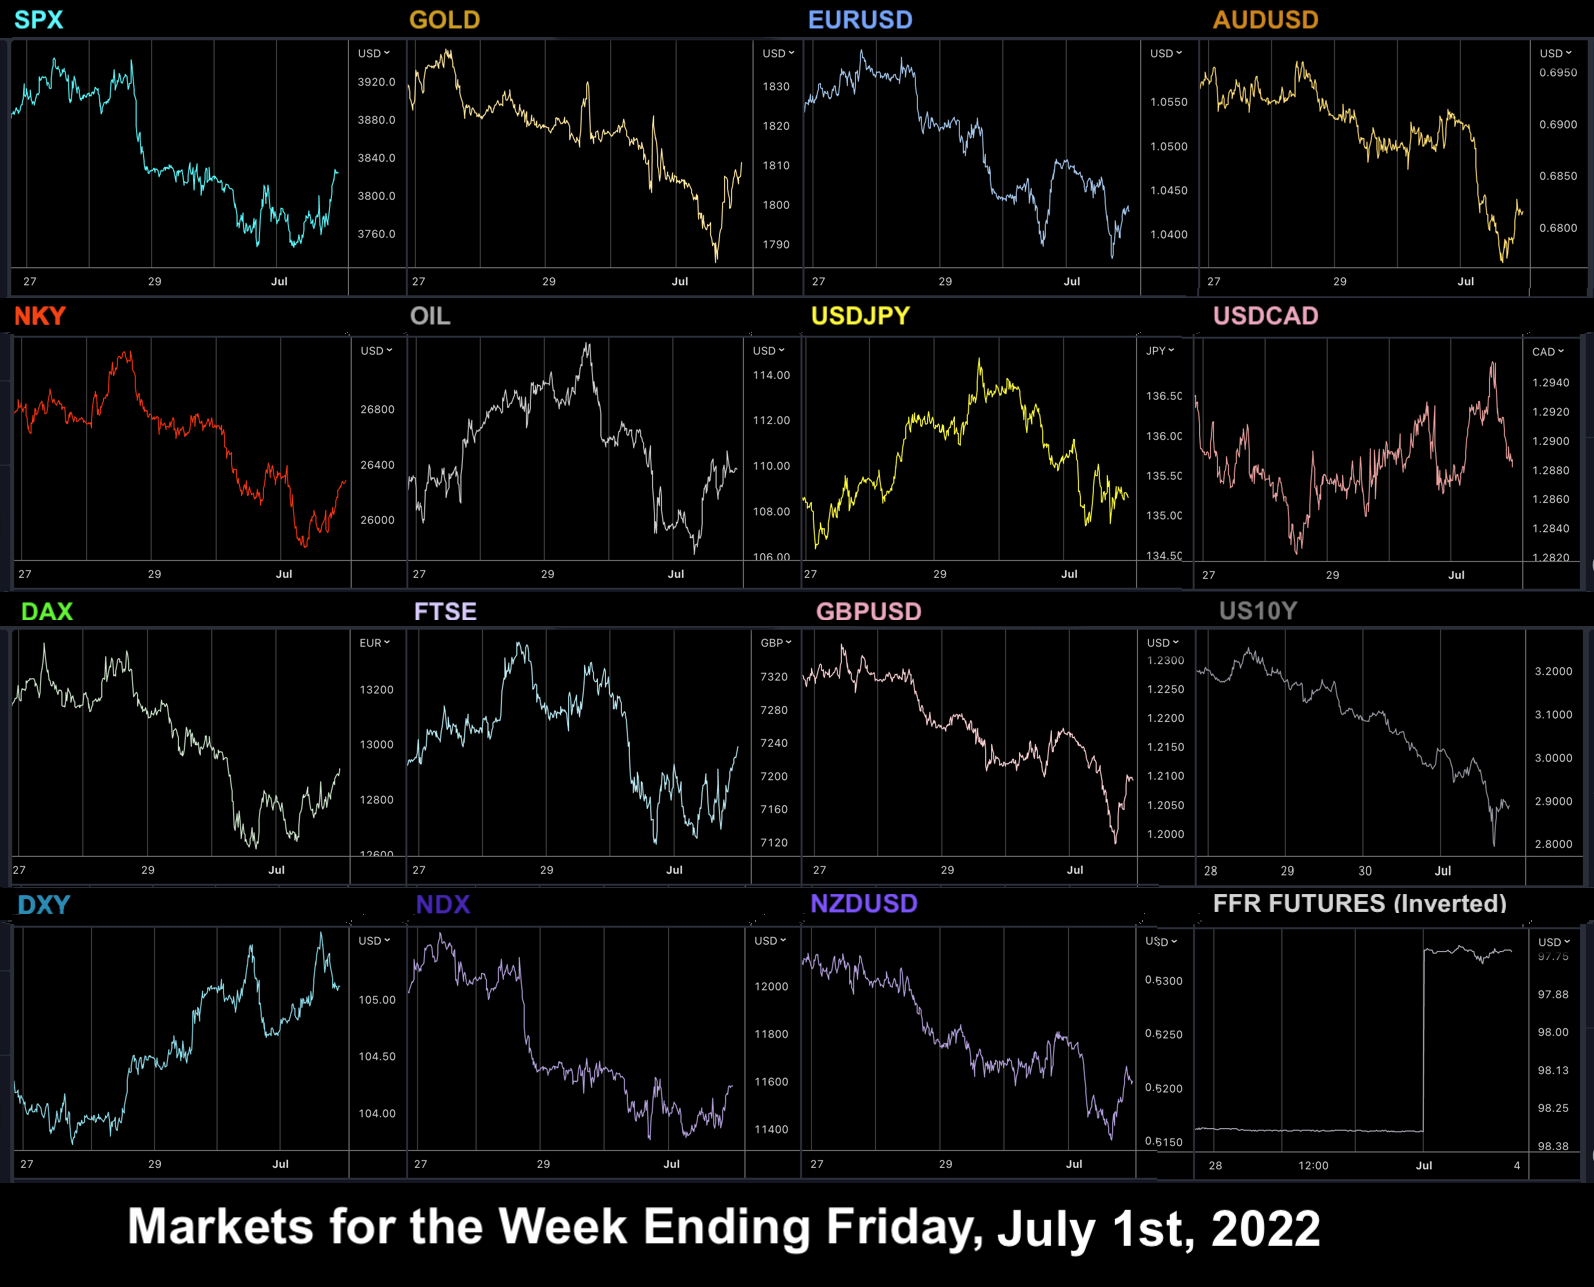
In a week where inflation concerns mixed with recession fears, the net effect was negative on stock markets as SPX and NDX retraced the late June rally and DAX maintained its relative weakness with further June lows. Currencies were mixed, but the general theme was one of USD strength as it made four higher highs and higher lows after bottoming on Monday. EURUSD re-tested the 1.035 low and looks on shaky ground as the annual central bank summit at Sintra underlined the ECB’s lack of options. ECB President Lagarde tried to strike a hawkish tone by saying that they could “move faster” depending on the data, which looked especially toothless when Spain’s CPI came in at 10.2% soon after, beating expectations by 1.4%. It begs the question: if not now, then when? Note the loose EU tone is not helping European stocks.

Inflation now looks more of a European problem than a US one as the Fed’s hiking cycle appears to be working. Long-term yields fell in the US and the 5-year forward inflation expectation rate fell to 2.08%, down from a high of 2.67% in April. Meanwhile, the 10s3s fell to 1.15% and the fall is accelerating – as inflation concerns fade, recession fears are picking up.


WEEKLY PRICE MOVEMENT

The biggest index mover this week was NDX, down 4.30%. The top forex mover was NZDUSD or NZDCAD down 3.21%. Crypto fell sharply again, and FANG underperformed NDX.

My EURAUD long made 1.12% this week, meaning I am now ahead 4.80% with 13/24 (54%) wins. This week I will carry on the theme but switch to buying EUR against the biggest riser CAD, which I think may pull back, so I will be long EURCAD.
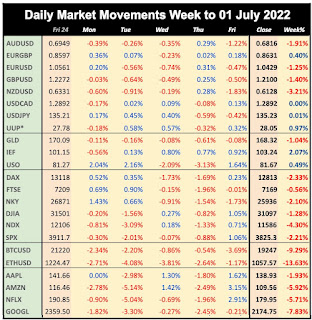


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.


NEXT WEEK

A new month, quarter and half year, and of course the main event is NFP. Although inflation is the primary driver of expectations of Fed action (and thus SPX pricing), the jobs report still has some effect. Traders are looking for signs that the tightening will be slowed down, and a poor report could therefore boost markets.

The week is of course foreshortened in the US (only) for Independence Day, hence why the ADP report is a day late. The only other significant event is the RBA rate decision, where a 50bp hike is expected, and may reverse the AUD trend, which is now trading at a one-year low. There are several trade balance and PMI reports but as you know, these have much less effect on markets than central bank actions.


CALENDAR  (all times are GMT, volatile items in bold)

Monday, July 4
01:00 Aus TD Securities Inflation
01:30 Aus Building Permits
06:00 Germany Trade Balance
13:30 Canada S&P Mfr PMI
14:30 BoC Business Outlook Survey
22:30 Aus AiG Construction Index
23:00 Aus S&P Svcs PMI

Tuesday, July 5
01:45 China Caixin Svcs PMI
04:30 RBA Rate Decision/Statement (e1.35% p0.85%)
07:55 Germany S&P Comp PMI
08:00 Eurozone S&P Comp PMI
08:30 UK S&P Comp PMI
09:30 UK Financial Stability Report
14:00 US Factory Orders
16:30 BoE Tenreyro speech

Wednesday, July 6
06:00 Germany Factory Orders
08:10 BoE Pill speech
09:00 EC Growth Forecasts
09:00 Eurozone Retail Sales (e5.4% p3.9%)
09:30 DE10Y Bond Auction
13:45 US S&P Comp & Svcs PMI
14:00 ISM Svcs PMI (e55.7 p55.9)
18:00 FOMC Minutes

Thursday, July 7
01:30 Aus Imports/Exports/TB
11:30 ECB MPC Minutes
12:15 US ADP (e200k p128k)
12:30 US Trade Balance
12:30 US Jobless Claims
12:30 Canada Trade Balance
14:00 Canada Ivey PMI
23:50 Japan Current Account

Friday, July 8
12:30 US NFP/AHE/UnEmp (NFP e250k p390k)
12:30 Canada NFP/AHE/UnEmp (UE e5.2% p5.1%)

Sunday, 20 March 2022

Week to Mar 18th

First rate hike since 2019, but priced in. Markets rally, JPY 6-year low.
MY CALL THIS WEEK : BUY EURCAD


LAST WEEK


In the best week for over a year, markets recovered, as the Ukraine situation didn't get any worse. The rally was halted by the widely predicted 0.25% rate hike on Wednesday, but didn't really fade, despite an dotplot suggest 11 hikes by the end of 2023. Chinese stocks had a V-shaped week, falling on COVID fears then rising on pro-business government announcements. EEM ETFs followed. The BoE raised rates as expected, but with one dissenting MPC member, and the 'rumor' rally stalled. In general though, all currencies beat the inside week dollar, except JPY, which made new six year highs. Yields hit their highest level since May 2019 on the rate hike. Gold and Oil continued to slide from their recent peaks.


WEEKLY PRICE MOVEMENT

The biggest index mover was oversold NDX, up 8.41%. The top forex mover was AUDJPY UP 3.34%. Bitcoin and Ethereum rallied. Tech outperformed with NFLX and FB making up for last weeks underperformance.

Last week's GBPJPY short position lost 2.69%, which means I am ahead 5.56% this year, with 6/10 (60%) wins. This week I am buying EURCAD, as Eurozone recovers and oil falls


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.


NEXT WEEK

There is little US news next week, the biggest prints are PMIs (still all expanding). UK inflation is expected to edge up to 6%. It is the two year anniversary of COVID bottom on Wed, and we are a similar situation. Once again, the markets are probably going to be dominated by Ukraine, and perhaps China.


CALENDAR  (all times are GMT, volatile items in bold)

Monday March 21
01:15 PBoC Rate Decision/Statement (e3.7% hold)
07:00 Germany PPI
12:30 Chicago Fed National Activity Index

Tuesday March 22
01:00 RBA Governor Lowe speech

Wednesday March 23
07:00 UK CPI (e6.0% p5.5%)
12:30 UK Budget Report (time approx.)
14:00 US New Home Sales
15:00 Eurozone Consumer Confidence
22:00 Aus Commonwealth Bank PMIs
23:50 BoJ MPC Minutes

Thursday March 24
08:30 Germany Markit PMIs (Mfr e58.5 p58.4)
09:00 Eurozone Economic Bulletin
09:00 Eurozone Markit PMIs (Comp e55.7 p55.5)
09:30 UK Markit PMIs (Svcs e60.7 p60.5)
12:30 US Durable Goods (e-0.6% p1.6%)
12:30 US Jobless Claims
13:45 US Markit PMIs
23:30 Tokyo CPI

Friday March 25
07:00 UK Retail Sales
09:00 Germany IFO Sentiment
14:00 Michigan CSI
14:00 US Pending Home Sales
16:45 BoC Gravelle speech

Saturday, 26 December 2020

Week to Dec 25th

Short Christmas week, New COVID strain, Brexit and US stimulus deals agreed
MY CALL THIS WEEK : SELL EURCAD

Despite the fact that it was the final short week before the holidays, and macro data was unsurprising, there were three big news items: the new more infectious COVID variant, the US stimulus deal finally agreed, and at the very close of the week, the long-awaited Brexit deal. All markets reacted to the first, only currencies to the second, and only GBP to the last as markets closed on Thursday lunchtime, although there was some more movement in currencies on Christmas Day, notable in EURGBP. Nevertheless the net effect was a fairly flat week, with no index moving more than 1%, as neither did any other asset except GBP and Oil.


Next week is the traditional core Santa Rally, and equities are expected to rise in thin trading, as many traders take the week off. London has an extra day off, so low volumes of forex trading plus the digesting of the full Brexit deal may produce some strange moves as seen on Christmas Day. Again macro news is slight. There may also be some year end last minute rebalancing (which means winners go up further and losers fall further)


I hope you have a happy Christmas and prosperous New Year.


Mon Dec 21
Equity and Oil Markets pulled back today on news of a new, more transmissible strain of coronavirus discovered in the UK and South Africa. The sell off held in Europe, but later trading in the US trimmed US losses and DJIA even managed to close slightly positive. After weeks of decline, the dollar perked up and was up across the board against all currencies and Gold. Bonds were flat on the day.


Tuesday December 22

Good news today as Congress finally passed the stimulus package. Also the WHO confirmed that the vaccines would still work against the new COVID variant. Europe recovered some of yesterday’s losses, and there was a slight rotation into NDX (up) from DJI and SPX (down). However Oil was down on the day, bonds were up, and JPY was up against all currencies except USD, which was strong after the stimulus news. Gold fell on dollar strength. So a mixed response really.


Wednesday December 23

Today was flat for SPX, with DJI and NDX reversing Tuesday’s rotation. Europe continued to recover from Monday’s drop, even against currency rises as the dollar gave up its rally and turned south, posting red candles against Gold and all currencies except JPY, which fell with bonds. Oil was also up on this overall positive day.


Thursday December 24

Germany was closed, and London and New York only did half-days today. However, the Brexit deal was confirmed before markets closed, and the notable movement was a rise in GBP and consequent fall in FTSE. Otherwise equity and Oil markets were up as Santa sentiment continued. The dollar was flat overall, as JPY fell to balance the GBP rise. Surprisingly though, Gold and bonds were up.


Friday December 25

Today was Christmas Day and markets everywhere except Japan and China are closed. There were however, notable moves in forex, with EURGBP adding 1.74% as the GBP rally fizzled out.


WEEKLY PRICE MOVEMENT

Indices were flat this week, with the biggest mover FTSE down 0.41% on GBP strength before Friday. Cable was the biggest mover down 1.27% on the week, the entire move being made on Christmas Day. Bitcoin made a new ATH on Christmas Day, and is outperforming Ethereum. FANGS were very mixed, with AAPL outperforming, up 4.19%.


My USDCAD trade worked, up 0.64%, moving my running total to 8.67% and 24/41 wins. This week I am selling EURCAD. Last week’s candle up was much larger than usual and I am looking for reversion to mean.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.


NEXT WEEK (all times are GMT)

(Calendar High volatility items are in bold)


Monday December 28

The US re-opens in what is traditionally a very strong three and half days, the core Santa Rally. The UK, Canada, Hong Kong and Australia are closed for Boxing Day observed.


23:50 Japan Industrial Production (Sun)


Tuesday December 29

The rest of the world markets open, the first day since the Brexit deal announced late on Christmas Eve. This should prove positive to markets, but there may be some sector variance (eg automobiles, the core part of DAX).

14:00 US S&P/Case-Shiller Home Price Indices


Wednesday December 30

Today is the UK Parliamentary Vote on Brexit deal, however it expected to pass easily as the opposition Labour Party have confirmed they will vote with the government.


07:00 Germany Retail Sales

14:45 Chicago PMI

15:00 US Pending Home Sales


Thursday December 31

The final day of 2020 may see some volatility through portfolio rebalancing. However, as most markets close at lunchtime, general trading is expected to be thin. Germany is closed for Silvester (New Year’s Eve)


01:00 China PMIs

13:30 US Jobless Claims


Friday January 1

All markets globally are closed today for New Year’s Day.

Saturday, 3 October 2020

Week to Oct 2nd

Acrimonious Presidential debate, Trump in hospital with COVID, Sharp drop in oil
MY CALL THIS WEEK : BUY EURCAD

In a gloomy week for markets, which first saw President Trump in debate fail to say he would respect the election result, and then late in the week announce that he has succumbed to COVID-19 himself, we saw a Monday rally fail to break out. DAX and AUD last weeks weakest performers outperformed on Monday, suggest this was only part of a the wider consolidation we have seen for weeks, perhaps driven by month and quarter end window-dressing.


The week also an extremely shallow dollar decline, with DXY and EURUSD both posting inside weeks. In commodities, Gold rose in an inside week, in line with the weaker dollar, but we saw sharp declines in Oil and Copper.


Mon Sep 28
Indices surged today, with European stocks posting their best day since June, and DAX adding 3.2%. Financials led, the sure sign of a risk-on day, and Oil was up in line


The dollar fell sharply, which appreciated Gold. Bonds were down in line with the equity move.


Tue Sep 29

Turnaround Tuesday with indices, Oil, Gold and Bonds all reversing Monday’s direction, without any particular new push. In currencies, some clearly reversed (such as GBP) whereas a further fall in EUR meant a flat dollar overall.


Wednesday September 30

Lots of action in the final day of the month and quarter, after an acrimonious Presidential debate, SPX initially plunged, but rallied in the afternoon session, which may well have been end of month and quarter portfolio rebalancing. SPX fell 3.9% on the month, NDX 5%. The dollar runs to a slower trend, and was down again today. Gold and bonds were down and Oil was up, all in line with the equity rally.


Thursday October 1

A flatter, but still upward trend in stocks faded late in the day, although all US indices were still up. The dollar was more or less flat as were bonds, and Gold was only slightly up, although Oil continued down.


Friday October 2

More bad news today on news that President Trump had contracted COVID and was moved to hospital as a precaution. Together with a miss on NFP (even below the ADP figure), stocks fell again, with NDX hit particularly hard down 2.83% to close a mere 0.94% on the week. Oil similarly fell hard, down over 4%. A mixed day in currencies resulted in a slight uptick in DXY (with Gold down in line) and another flat day in bonds.


WEEKLY PRICE MOVEMENT

Another consolidation week in indices, with less volatility saw last weeks loser DAX come out on top, but up only 1.76%. Similarly, the top forex mover up AUDUSD was last weeks biggest loser. Another flat week for crypto, and FANGS were mixed but generally subdued.


Buying EURCAD for a second week worked with a gain of 0.15% (more than covering last week’s 0.08% loss) and at one point I was 1.12% ahead. I still believe in this cup-and-handle, so I will buy EURCAD for a third week running. The running profit total is 8.23% with 18 wins out of 33.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.


NEXT WEEK (all times are GMT)

(Calendar High volatility items are in bold)


  • Election four weeks away
  • President’s health concern
  • Australian Rate Decision
  • FOMC Minutes

Monday October 5 

The main focus this week will be on the President’s condition in hospital, the election campaign and COVID. Markets are closed all week in China for the National Day holiday.


07:55 Germany Markit PMI Composite

08:00 Eurozone Markit PMI Composite

08:30 BoE Haldane speech

09:00 Eurozone Retail Sales (YoY e0.6% p0.4%)

13:45 USD Markit Services/Composite PMI

14:00 ISM Services PMI (e56 p56.9)


Tuesday October 6 

Today Jay Powell gives a webcast speech on the Economic Outlook at the National Association for Business Economics Annual Meeting


00:30 Aus Imports/Exports/TB

03:30 RBA Rate Decision/Statement (e0.25% hold)

06:00 Germany Factory Orders

12:30 US Trade Balance

14:40 Fed Chair Powell speech


Wednesday October 7 

Today’s speech by ECB President Lagarde at the Paris Europlace Online International Financial Forum is pre-recorded, so more attention will be given the the FOMC minutes.


06:00 Germany Industrial Production

12:10 ECB's President Lagarde speech

14:00 Canada Ivey PMI

18:00 FOMC Minutes

19:00 Fed Williams speech


Thursday October 8

Another day heavy on CB speakers and relatively light on news, a pattern we have seen all week.


06:00 Germany Trade Balance

10:15 ECB Mersch speech

11:30 ECB MPC Minutes

12:30 US Jobless Claims

12:30 BoC Gov Macklem speech


Friday October 9 

As often happens when the US NFP is on the 1st or 2nd of the month, the Canadian equivalent is a week later. As well as China, markets are also closed in South Korea today.


01:45 China Caixin Services PMI

06:00 UK Manuf/Industrial Production

06:00 UK GDP

12:30 Canada NFP/AHE/UnEmp (NFP e230k p246k)

15:15 BoE Haldane speech