Showing posts with label Ukraine. Show all posts

Saturday, 9 April 2022

Week to Apr 8th

Dollar and yields surge on hawkish Fed marks. FTSE outperforms
MY CALL THIS WEEK : BUY EURAUD


LAST WEEK


Most equity markets fell this week on hawkish comments from Fed Brainard and also the FOMC minutes where it was reported that 50bp rate hikes “could be appropriate”. The exception was the oil and bank heavy UK FTSE which came within a whisker of a 44-month high. There was little scheduled data, and as the Ukraine stalemate continues, the war fades from traders’ minds (SPX underperformed DAX), and focus is on rate hikes, and inflation which is driving them (see next week). The same factors drove the dollar to a new 11-month high, and yields to a 3-year high, whilst the yield curve retraced last week's move back into positive territory. JPY, gold and silver had inside weeks. Other metals and oil had reduced volatilty as they consolidate off the highs.


WEEKLY PRICE MOVEMENT

The biggest index mover was rate-sentitive NDX which was down 3.59%. The top forex mover EURUSD down 1.59%. Bitcoin and Ethereum pulled back. FANGs underperformed NDX as a whole..

Last week's EURJPY long position lost 0.10%, which means I am ahead 3.84% this year, with 6/13 (46%) wins. This week I am buying the oversold EURAUD


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.


NEXT WEEK

Earnings season starts next week, with as always JPM first out of the door on Wednesday, followed by WFC, C and GS the next day. Also Thursday sees the ECB rate decision meeting and press conference. We have inflation from the UK and China as well as the all-important US, which are all forecast to rise, a miss on this print would be positive for stocks short-term. Finally, this is Easter week, and markets are closed for Good Friday (UK and Germany have a four day break with Monday off as well)


CALENDAR  (all times are GMT, volatile items in bold)

Monday April 11
01:00 BoJ's Governor Kuroda speech
01:30 China CPI (e1.2% p0.9%)
06:00 UK GDP MoM
06:00 UK Ind/Mfr Production
11:00 UK NIESR GDP Est (time approx.)
13:30 Fed Bowman speech
16:00 Fed Williams speech

Tuesday April 12
06:00 UK Claimant Count/AHE/UnEmp (UE e3.8% p3.9%)
06:00 Germany CPI (e7.6% p7.6%)
08:00 ECB Bank Lending Survey
09:00 Germany ZEW Sentiment
12:30 US CPI (Core e6.6% p6.4%)
16:10 Fed Brainard speech
18:00 US Monthly Budget Statement

Wednesday April 13
00:30 Aus Westpac Consumer Confidence
02:00 China Imports/Exports/TB
06:00 UK CPI (e6.6% p6.2%)
06:15 BoJ Governor Kuroda speech
09:30 DE10Y Bond Auction
12:30 US PPI
14:00 BoC Rate Decision/Statement (e0.5% hold)
15:15 BoC Press Conference

Thursday April 14
01:00 Aus Consumer Inflation Expectations
01:30 Aus Jobs/Unemp (UE p4.0%)
04:30 Japan Ind Production
05:00 China FDI (time approx.)
11:45 ECB Rate Decision/Statement (e0% hold)
12:30 US Jobless Claims
12:30 US Retail Sales
12:30 ECB Pres Lagarde Presser
14:00 Michigan CSI (e60.6 p59.4)

Friday April 15
No significant news, markets closed

Saturday, 2 April 2022

Week to Apr 1st

Recovery continues with ruble up and oil down
MY CALL THIS WEEK : BUY EURJPY


LAST WEEK

Following a slight thaw in Ukraine/Russia talks, equity markets made new post-invasion highs this week but could not hold them, falling back into last week’s range, with a V-shaped after the slight NFP miss. NDX outperformed for the third week after months of underperformance. The quarter ended badly, the worst Q1 since 2020.

Oil fell heavily on news that the US is releasing some of its strategic reserve. The ruble appreciated 38% (70% from last weeks low of 0.6c), news that Putin is insisting on ruble payments from “unfriendly countries” for energy. Apparently this does not apply to EUR, the week’s strongest currency. AUD and NZD fell back after strong runs. Bond yields fell back from the highs, as did Oil. Gold is in it’s third week off the highs, and retraced last week’s gain. The yen hit a new six year low, prompting BoJ buying action.


WEEKLY PRICE MOVEMENT

The biggest index mover was NKY which rallied last week, down 1.72%. The top forex mover EURGBP up 0.99%. Bitcoin and Ethereum rallied again. Tech outperformed although FANGs were fairly flat.

Last week's AUDJPY short position lost 0.14%, which means I am ahead 3.94% this year, with 6/12 (50%) wins. This week I am banking on a further move down in JPY, and recovering EUR, and buying EURJPY


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.


NEXT WEEK

Next week is light on US Data, with the key events Wednesday’s FOMC Minutes, and Tuesday’s ISM Services. CB speakers are heavy next week with four BoE and four Fed speeches. There is also the RBA Rate Decision, and trade balance figures from Germany, the US and Canada. Earnings season doesn’t start until next week with JPM on 13 Apr.


CALENDAR  (all times are GMT, volatile items in bold)

Monday April 4
06:00 Germany Trade Balance
08:30 BoE Mann speech
09:05 BoE Governor Bailey speech
14:00 US Factory Orders
14:00 BoE Cunliffe speech
14:30 BoC Business Outlook Survey
22:30 Aus AiG Perf of Construction
23:00 Aus S&P Global Services PMI
23:30 Japan Overall Household Spending

Tuesday April 5
00:30 Aus TD Securities Inflation (time approx.)
04:30 RBA Rate Decision/Statement (e0.1% hold)
07:55 Germany Composite PMI
08:00 Eurozone Composite PMI
12:30 US Trade Balance
12:30 Canada Trade Balance
13:45 US Composite/Svcs PMI
14:00 ISM Services PMI (e57.7 p56.5)
15:05 Fed Brainard speech
18:00 Fed Williams speech

Wednesday April 6
01:45 China Caixin Services PMI
06:00 Germany Factory Orders
14:00 Canada Ivey PMI
18:00 FOMC Minutes

Thursday April 7
01:30 Aus Imports/Exports/TB (TB p1.29B)
09:00 Eurozone Retail Sales (e4.2% p7.8%)
11:30 ECB MPC Minutes
12:15 BoE Pill speech
12:30 US Jobless Claims
13:00 Fed Bullard speech
20:05 Fed Williams speech
23:50 Japan Current Account

Friday April 8
12:30 Canada NFP/AHE/UnEmp (UnEmp e6.0% p5.5%)

Saturday, 26 March 2022

Week to Mar 25th

New multi-year highs for USDJPY and yields. Tech recovers.

MY CALL THIS WEEK : SELL AUDJPY


LAST WEEK


With a stalemate in Ukraine, this week’s moves were much more muted, although US indices made post-invasion highs, although DAX did not, despite the EU PMI beats, although European consumer confidence dropped by the second largest amount on record. The dollar (DXY) had an inside week, as did the euro and Gold. The yen continued to fall with USDJPY making highs not seen since Dec 2015. AUDJPY hit highs last seen in August 2015, and both AUD and NZD made new 2021 highs against the dollar. Yields broke 2.4%, a new three year high, after Fed Powell's remarks preparing markets for 50bp increases. Oil continued to consolidate after the high two weeks ago, still managed to post an 8% weekly gain, such is the current volatility.


WEEKLY PRICE MOVEMENT


The biggest index mover was oversold NKY, up 4.93%. The top forex mover was again AUDJPY up 3.59%. The pair has risen 6.93% in two weeks. Bitcoin and Ethereum rallied again although less than last week. Tech outperformed again with all FANGs except NFLX up in line.

\

Last week's EURCAD long position lost 1.48%, which means I am ahead 4.08% this year, with 6/11 (54.5%) wins. This week I am banking on AUDJPY reversing and shorting it.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.


NEXT WEEK


A new month and quarter, so the main event is NFP on Friday. Give the Ukrainian stalemate, this event may have more significance than last month. Fed Williams speaks this week, and traders will be alert to rate hike clues before earnings takes over next week. Germany and the Eurozone report inflation this week, both estimating a small increase. We also have US GDP (equal to inflation so zero real growth), and also UK GDP (well below inflation).


CALENDAR  (all times are GMT, volatile items in bold)


Monday March 28

11:00 BoE Governor Bailey speech

23:30 Japan Jobs/UnEmp


Tuesday March 29

00:30 Aus Retail Sales

06:00 Germany Gfk Consumer Confidence

13:00 Fed Williams speech

13:00 Housing/Home Price Indices

23:50 Japan Retail Sales


Wednesday March 30

08:10 BoE Broadbent speech

09:00 Eurozone Business Climate/Consumer Confidence

12:00 Germany CPI (e5.4% p5.5%)

12:15 US ADP (e400k p475k)

12:30 US PCE QoQ

12:30 US Q4 GDP (YoY e7.1% p7.0%)

23:50 Japan Ind Production


Thursday March 31

00:30 Aus Building Permits

01:00 China PMIs (Mfr e49.8 p50.2)

06:00 UK Q4 GDP (QoQ e1.0% p1.0%)

06:00 Germany Retail Sales (e2.4% p10.3%)

07:55 Germany Unemployment

08:00 OPEC Meeting

09:00 Eurozone Unemployment

12:30 US PCE MoM & YoY

12:30 US Jobless Claims

12:30 US Personal Income/Spending

12:30 Canada GDP

13:00 Fed Williams speech

13:45 Chicago PMI

21:30 Aus AiG Mfg Index

23:50 Japan Tankan Mfr Indices


Friday April 1

01:45 China Caixin Mfr PMI

07:55 Germany Markit Mfr PMI

08:30 UK Markit Mfr PMI

09:00 Eurozone CPI (Core 2.8% p2.7%)

12:30 US NFP/AHE/UnEmp (NFP e450k p678k)

13:30 Canada Markit Mfr PMI

13:45 US Markit Mfr PMI

14:00 US ISM PMI (e58.5 p58.6)

Sunday, 20 March 2022

Week to Mar 18th

First rate hike since 2019, but priced in. Markets rally, JPY 6-year low.
MY CALL THIS WEEK : BUY EURCAD


LAST WEEK


In the best week for over a year, markets recovered, as the Ukraine situation didn't get any worse. The rally was halted by the widely predicted 0.25% rate hike on Wednesday, but didn't really fade, despite an dotplot suggest 11 hikes by the end of 2023. Chinese stocks had a V-shaped week, falling on COVID fears then rising on pro-business government announcements. EEM ETFs followed. The BoE raised rates as expected, but with one dissenting MPC member, and the 'rumor' rally stalled. In general though, all currencies beat the inside week dollar, except JPY, which made new six year highs. Yields hit their highest level since May 2019 on the rate hike. Gold and Oil continued to slide from their recent peaks.


WEEKLY PRICE MOVEMENT

The biggest index mover was oversold NDX, up 8.41%. The top forex mover was AUDJPY UP 3.34%. Bitcoin and Ethereum rallied. Tech outperformed with NFLX and FB making up for last weeks underperformance.

Last week's GBPJPY short position lost 2.69%, which means I am ahead 5.56% this year, with 6/10 (60%) wins. This week I am buying EURCAD, as Eurozone recovers and oil falls


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.


NEXT WEEK

There is little US news next week, the biggest prints are PMIs (still all expanding). UK inflation is expected to edge up to 6%. It is the two year anniversary of COVID bottom on Wed, and we are a similar situation. Once again, the markets are probably going to be dominated by Ukraine, and perhaps China.


CALENDAR  (all times are GMT, volatile items in bold)

Monday March 21
01:15 PBoC Rate Decision/Statement (e3.7% hold)
07:00 Germany PPI
12:30 Chicago Fed National Activity Index

Tuesday March 22
01:00 RBA Governor Lowe speech

Wednesday March 23
07:00 UK CPI (e6.0% p5.5%)
12:30 UK Budget Report (time approx.)
14:00 US New Home Sales
15:00 Eurozone Consumer Confidence
22:00 Aus Commonwealth Bank PMIs
23:50 BoJ MPC Minutes

Thursday March 24
08:30 Germany Markit PMIs (Mfr e58.5 p58.4)
09:00 Eurozone Economic Bulletin
09:00 Eurozone Markit PMIs (Comp e55.7 p55.5)
09:30 UK Markit PMIs (Svcs e60.7 p60.5)
12:30 US Durable Goods (e-0.6% p1.6%)
12:30 US Jobless Claims
13:45 US Markit PMIs
23:30 Tokyo CPI

Friday March 25
07:00 UK Retail Sales
09:00 Germany IFO Sentiment
14:00 Michigan CSI
14:00 US Pending Home Sales
16:45 BoC Gravelle speech

Saturday, 12 March 2022

Week to Mar 11th

Gold and Oil hit and retreat from highs
MY CALL THIS WEEK : SELL GBPJPY


LAST WEEK

The war in Ukraine continues with no clear progress by either side, and this is keeping markets depressed, but hugely volatile. US markets fell but held the Feb 24th invasion low, however European markets, which dipped below last week recovered, with a particularly strong showing from oversold DAX. The main news item, US CPI, was in line with estimates, and had little effect on markets.


The dollar (DXY) hit a new two-year high, and all currencies were down. EUR rose into the ECB meeting, and then fell away despite a relatively hawkish stance from President Lagarde, paving the way for rate hikes. GBP was sharply down, making a 16-month low. Notably, and unusually JPY fell sharply all week, unlike its fellow safe haven Gold, which shot up to $2,070, within a whisker of its all-time high, before falling back sharply. Similarly, Oil spiked up to highs not seen since 2008, before pulling back sharply. 10-year yields followed the dollar and reversed last week's drop.


WEEKLY PRICE MOVEMENT


The biggest index mover was oversold DAX, up 4.07%. The top forex mover was USDJPY down 2.18%. Bitcoin and Ethereum were flat again. Tech underperformed generally as the rate hike looms. We are seeing notable divergence by the weaker FANGs NFLX and FB.


Last week's EURNZD long position made 0.66%, which means I am ahead 8.25% this year, with 6/9 (66.7%) wins. This week I am expecting the BoE will not raise rates and selling GBPJPY.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.


NEXT WEEK


Although Ukraine is still dominating the headlines, all eyes will be on the Fed on Wednesday for their anticipated first rate hike (25bp to 0.50%) since 2019. This is 97% likely (and priced in) according to the CME Fedwatch tool. Also notable is the BoE decision. They raised rates by 25bp last month, so a further hike is less likely. The US, China and Canada all report Retail Sales, expected to be sluggish. And finally, next week is the two week period we get every March where the US enters DST two weeks before Europe, meaning US markets open and close an hour earlier for Europeans.


CALENDAR  (all times are GMT, volatile items in bold)


Monday March 14

02:00 China FDI (time approx.)


Tuesday March 15

00:30 Aus House Price Index

00:30 RBA MPC Minutes

02:00 China Retail Sales (e2.8% p1.7%)

07:00 UK AHE/UnEmp (UnEmp e4.0% p4.1%)

10:00 Eurozone Ind Production

10:00 Eurozone ZEW Economic Sentiment

10:00 Germany ZEW Economic Sentiment

12:30 US PPI

23:50 Japan Import/Exports/TB


Wednesday March 16

04:30 Japan Industrial Production

10:30 Germany 10Y Bond Auction (time approx.)

12:30 US Retail Sales (MoM e0.6% p3.8%)

12:30 Canada BoC CPI (Core e4.8% p4.3%)

18:00 Fed Rate Decision/Statement (e0.5% p0.25%)

18:30 FOMC Press Conference


Thursday March 17

00:30 Aus Jobs/UnEmp (UnEMp e4.1% p4.2%)

10:00 Eurozone CPI

12:00 BoE Rate Decision/Statement (e0.5% hold)

12:30 US Building Permits/Housing Starts

12:30 US Jobless Claims

12:30 Philly Fed Mfr Survey

23:30 Japan National CPI


Friday March 18

03:00 BoJ Rate Decision/Statement (0.1% hold)

06:00 BoJ Press Conference

10:00 Eurozone Labor Cost

12:30 Canada Retail Sales (e-2.1% p-1.8%)

Saturday, 5 March 2022

Week to Mar 4th

Ukraine war causes DAX and EUR collapse. Oil at record highs.
MY CALL THIS WEEK : BUY EURNZD


LAST WEEK

Whereas US markets only slipped slightly in an inside week, mostly on the Ukraine nuclear power plant attack, DAX had its worst week since the pandemic crash in Mar 2020, and FTSE fared little better, with its Russian components falling more than its oil components rose. Markets more or less ignored the otherwise important NFP beat, which gives the Fed little room to delay their tightening.

Oil hit 116.52, its highest price ever except for the summer of 2008, and easily its highest price ever expressed in GBP or EUR. The Brent/WTI spread varied by 10c in the week, the widest since the negative WTI crisis during COVID. 10-year yields dropped sharply, back to October 2021 levels, and EUR had its worst week since the start of the COVID crisis, propelling DXY up to levels not seen since 2020. Notably Asian currencies were not affected, JPY retraced last weeks' gains in an inside week, and AUD and NZD outperformed the dollar, the former on rate hike hints. An actual rate hike in Canada was already priced and the currency hardly moved.


WEEKLY PRICE MOVEMENT

The biggest index mover was Ukraine-sensitive DAX, down 10.11%. The top forex mover was EURAUD down 5.11%. Bitcoin and Ethereum were fairly flat. Some of the FANGs performed a lot worse than NDX, although in general tech underperformed.

Last week's EURNZD short position made 4.68%, which means I am ahead 7.59% this year, with 5/8 (62.5%) wins. I will now reverse that position and buy EURNZD, as the rate hike hint may drive AUD up more.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.


NEXT WEEK

Although Ukraine is likely to dominate markets, the key day for schedule news is Thursday with the ECB simultaneous with US core inflation (ie without Ukraine factor-oil) which is estimated to make a new high. We also have inflation from Germany and China, US, Canada, China trade figures and GDP from Eurozone, UK and Japan.


CALENDAR  (all times are GMT, volatile items in bold)

Monday March 7
02:00 China Imports/Exports/TB
07:00 Germany Factory Orders
09:00 Germany Retail Sales (time approx.) (e9.5% p0%)
23:50 Japan Current Account

Tuesday March 8
10:00 Eurozone GDP (QoQ e0.3% p0.3%)
13:30 US Trade Balance
13:30 Canada Trade Balance
22:15 RBA Governor Lowe speech
23:30 Aus Westpac Consumer Confidence
23:50 Japan GDP (e1.4% p1.3%)

Wednesday March 9
01:30 China CPI/PPI
08:00 RBA Debelle speech

Thursday March 10
00:00 Aus Consumer Inflation Expectations
12:45 ECB Rate Decision/Statement (e0% hold)
13:30 ECB Press Conference
13:30 US CPI (Core e6.4% p6.0%)
13:30 US Jobless Claims
19:00 US Monthly Budget Statement
22:15 RBA Governor Lowe speech
23:30 Japan Overall Household Spending

Friday March 11
07:00 UK GDP
07:00 UK Ind/Mfr Production
07:00 Germany CPI (e5.5% p5.5%)
13:30 Canada NFP/AHE/UnEmp (UE e6.2% p6.5%)
15:00 Michigan CSI (e61.3 p62.8)

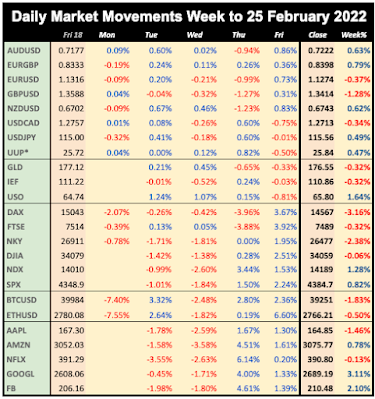
Sunday, 27 February 2022

Week to Feb 25th

Russia invades Ukraine. Markets recover in hours.
MY CALL THIS WEEK : SELL EURNZD


LAST WEEK

As we mentioned last week, the primary driver of markets this week was the invasion of Ukraine by Russia, the first war on European soil since the Kosovo in 1999. Markets fell hard on Thursday morning and gold, oil and the dollar surged in classic form. However, the moves were quickly reversed, and SPX and NDX both ended the week up, and DJIA was flat. The dollar and yields were up overall, the latter not really reacting to the Ukraine issue. The RBNZ rate hike was priced in, and had no effect on NZD. Gold and oil both tracked the dollar.


WEEKLY PRICE MOVEMENT

The biggest index mover was Ukraine-sensitive DAX, down 3.16%. The top forex mover was GBPAUD up 1.91%. Bitcoin and Ethereum were flat, as was FANG.

Last week's AUDNZD long position made 0.08%, which means I am ahead 2.91% this year, with 4/7 (57%) wins. I think EUR is going to react to Ukraine, and so sell it against NZD. I am avoiding AUD as there is a rate decision statement.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.

NEXT WEEK
Next week sees a new month, and therefore NFP, which at 400k estimate is similar to last month's print. Ukraine is still expected to dominate the general headlines, although Australian and Canadian rate decisions and Aussie and Canadian inflation will have an effect in the forex area.

CALENDAR  (all times are GMT, volatile items in bold)

Monday February 28
23:50 Japan Ind Production (Sun)
23:50 Japan Retail Sales (Sun)
00:00 Aus TD Securities Inflation
00:30 Aus Retail Sales (p-4.4%)
13:30 Canada Current Account
14:45 Chicago PMI
21:30 Aus AiG Mfg Index

Tuesday March 1
01:00 China PMIs
01:45 China Caixin Mfr PMI
03:30 RBA Rate Decision/Statement (e0.1% hold)
07:00 Germany Retail Sales (p0%)
08:55 Germany Markit Mfr PMI
09:30 UK Markit Mfr PMI
13:00 Germany CPI (e5.3% p5.1%)
13:30 Canada Q4 GDP (p5.4%)
14:30 Canada Markit Mfr PMI
14:45 US Markit Mfr PMI
15:00 ISM Mfr PMI (e58.0 p57.6)
18:30 BoE Saunders speech

Wednesday March 2
00:30 Australia Q4 GDP (e0.5% p-1.9%)
08:55 Germany UnEmp Change/Rate
10:00 Eurozone HICP (CPI) (Core p2.3%)
10:30 DE10Y Bond Auction
13:15 US ADP (e328k p-301k)
15:00 BoC Rate Decision/Statement (e0.25% hold)
19:00 Fed Beige Book
20:00 BoE Cunliffe speech
21:30 Aus AiG Construction Index
22:00 Aus Commonwealth Bank Services PMI

Thursday March 3
00:30 Aus Imports/Exports/TB (TB p8.36B)
01:45 China Caixin Services PMI
08:55 Germany Markit Comp PMI
09:00 Eurozone Markit Comp PMI
10:00 Eurozone UnEmp Rate
12:30 ECB MPC Minutes
13:30 US Jobless Claims
14:45 US Markit Comp/Svcs PMIs
15:00 US Factory Orders
15:00 ISM Svcs PMI (e 61 p59.9)
23:30 Japan Jobs/UnEmp

Friday March 4
07:00 Germany Trade Balance
10:00 Eurozone Retail Sales (p2%)
13:30 US NFP/AHE/UnEmp (NFP e400k p467k)
15:00 Canada Ivey PMI

Sunday, 20 February 2022

Week to Feb 18th

Ukraine uncertainty abounds. Gold makes 9-month high
MY CALL THIS WEEK : BUY AUDNZD


LAST WEEK

Markets wobbled this week on Ukraine fears and but only ended up slightly down in inverted V-shaped pattern. USD made a V-shape but ultimately consolidated. The dollar consolidated and ended the week flat. After weeks of rising, 10-year yields pulled back in an inside week. Oil, affected by Ukraine tensions, was slightly more volatile and made a brief new high a few cents shy of $94 before pulling back. The only notable risk-off move was Gold which broke $1,900 for the first time since May 2021. The FOMC minutes did not reveal anything new, and there was no reaction from traders.


WEEKLY PRICE MOVEMENT

The biggest index mover was Ukraine-sensitive DAX, down 2.48%. The top forex mover was EURNZD down 1.07%. Bitcoin and Ethereum fell moderately, and FANG was fairly flat, except for beleaguer FB, down 6.1% and now at May 2020 lows, 46% off its September 2021 high.

Last week's EURGBP long position lost 0.48%, which means I am ahead 2.83% this year, with 3/6 (50%) wins. The trend is difficult to read this week, so I will fall back on my reserve AUDNZD, as a buy. It's won't make much, but it's safe.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.


NEXT WEEK

Next week is a foreshortened four day week after Presidents Day on Monday when the markets are closed. There is little significant scheduled news, most important print is US GDP on Thu estimated at 7%, equal to the inflation figure which indicates no growth. With that, the primary focus will be on the tensions in Ukraine.


CALENDAR  (all times are GMT, volatile items in bold)

Monday February 21
22:00 Commonwealth Bank PMIs (Sun)
01:15 PBoC Rate Decision/Statement (e3.7% hold)
07:00 Germany PPI
08:30 Germany Markit PMIs (Mfr e59.4 p59.8)
09:00 Eurozone Markit PMIs (Comp e52.7 p53.8)
09:30 UK Markit Svcs PMI (e55.2 p54.1)

Tuesday February 22
09:00 Germany IFO Sentiment Indicators
10:45 BoE Ramsden speech
14:00 US Housing/Home Price Indices
14:45 US Markit PMIs
15:00 US Consumer Confidence

Wednesday February 23
07:00 Germany Gfk Consumer Confidence
10:00 Eurozone HICP (CPI)

Thursday February 24
13:30 Chicago Fed National Activity Index
13:30 US PCE (QoQ)
13:30 US Q4 GDP (e7.0% p6.9%)
13:30 US Jobless Claims
15:00 US New Home Sales
23:30 Tokyo CPI

Friday February 25
07:00 Germany Q4 GDP
10:00 Eurozone Business Climate
10:00 Eurozone Consumer Confidence
13:30 US PCE (MoM & YoY)
13:30 US Durable/ND Capital Goods (DG e0.6% p-0.7%)
15:00 US Pending Home Sales
15:00 Michigan CSI