Showing posts with label EURNZD. Show all posts

Sunday, 19 June 2022

Week to Jun 17th

Record rate hike causes market plunge
MY CALL THIS WEEK : BUY EURNZD


LAST WEEK


This week saw the Fed raise rates by 75bp, the first hike of this magnitude since 1994. The market was expecting a 50bp hike, but, during the blackout period on Monday, a WSJ journalist reported that the Fed are likely to "consider surprising markets" with the higher figure. SPX was off nearly 4% that day, and fell all week, other than a slight relief rally on the day itself. SPX is now 22.5% off the high and therefore 'officially' a bear market. Note that DJIA is still only 17.75% from its ATH. The UK and German markets pretty much followed suit, although DAX is still above its post-Ukraine March low, and FTSE, now the strongest of major indices is only 8.5% off, helped by its oil weighting.

The UK also raised rates on Thursday, but 'only' by 0.25% which held up GBP, although this may have also been dollar-driven, as EUR also rose. The BoJ continued with their loose policy (no rate hike, tightening of QE). DXY and USDJPY made their highest weekly close for 20 years, as 10-year yields rose 32bp and touched a new 11-year high, although notably pulled back to close the week only 5bp up.

Oil had its worst week since March, leading to a 18-month low for CAD, and gold pulled back, both more than you would expect for just the dollar movement. Bitcoin broke through June support to post its worst week since the March 2020 pandemic crash.

Next week we are expecting some SPX and DAX recovery, as shown in our subscriber analysis charts. This may however be followed by further lows. We have a similar view on EURUSD, some upside for now. The doji spike on 10-year yields is significant, which leads on to our view on USDJPY


WEEKLY PRICE MOVEMENT

The biggest index mover this week was SPX, down 5.79%. The top forex mover was USDCAD up 2.12%. Crypto collapsed hard, and FANG fell in line with SPX.

My EURGBP short lost 0.62% this week, meaning I am now ahead 3.09% with 11/22 (50% wins). This week I am reversing course and buying EURNZD. I feel EUR must rally, and NZD is the most overextended.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.


NEXT WEEK

The main event in the four-day week in the US is probably Fed Chair Powell's Humphrey-Hawkins testimony, where Congress will no doubt be focused on inflation and the Fed's plan to combat it. Monday is the Juneteenth holiday in the US only. There are no major US releases. Elsewhere we have further rising inflation expected in the UK and Canada, and a batch of PMIs, all looking fairly stable. Volatility is therefore likely to damp down, compared to last week's rate hike moves. Equity markets will probably move slightly upwards, now the rate hike has been digested. The dollar has come off the highs, but as we have said previously, may not be done yet.


CALENDAR  (all times are GMT, volatile items in bold)

Monday June 20
01:30 PBoC Interest Rate Decision (e3.7% hold)
06:00 Germany PPI
08:00 BoE Haskel speech
12:30 Chicago Fed National Activity Index
13:00 BoE Mann speech

Tuesday June 21
00:00 RBA Governor Lowe speech
01:30 RBA MPC Minutes
07:15 BoE Pill speech
12:15 BoE Tenreyro speech
12:30 Canada Retail Sales (e1.8% p0.0%)
23:50 BoJ MPC Minutes

Wednesday June 22
06:00 UK CPI/PPI/RPI (CPI 9.8% p9.0%)
08:40 BoE Cunliffe speech
12:30 Canada CPI (BoC Core e5.9% p5.7%)
13:30 Fed Chair Powell HH Senate Testimony
14:00 Eurozone Consumer Confidence
14:40 BoC Rogers speech
22:00 Aus S&P Svcs PMI
23:00 Aus S&P Mfr PMI

Thursday June 23
07:30 Germany S&P PMIs (Mfr e54.8 p54.8)
08:00 Eurozone Economic Bulletin
08:00 Eurozone S&P PMIs (Comp e54.2 p54.8)
08:30 UK S&P PMIs (Svcs e52.6 p53.4)
12:30 US Jobless Claims
13:45 US S&P PMIs
14:00 Fed Chair Powell HH House Testimony
20:30 US Bank Stress Test Info
23:30 Japan National CPI

Friday June 24
06:00 US Retail Sales
08:00 Germany IFO Business Sentiment
11:30 RBA Governor Lowe speech
12:30 BoE Pill speech
13:45 BoE Haskel speech
14:00 Michigan CSI
14:00 US New Home Sales

Saturday, 5 March 2022

Week to Mar 4th

Ukraine war causes DAX and EUR collapse. Oil at record highs.
MY CALL THIS WEEK : BUY EURNZD


LAST WEEK

Whereas US markets only slipped slightly in an inside week, mostly on the Ukraine nuclear power plant attack, DAX had its worst week since the pandemic crash in Mar 2020, and FTSE fared little better, with its Russian components falling more than its oil components rose. Markets more or less ignored the otherwise important NFP beat, which gives the Fed little room to delay their tightening.

Oil hit 116.52, its highest price ever except for the summer of 2008, and easily its highest price ever expressed in GBP or EUR. The Brent/WTI spread varied by 10c in the week, the widest since the negative WTI crisis during COVID. 10-year yields dropped sharply, back to October 2021 levels, and EUR had its worst week since the start of the COVID crisis, propelling DXY up to levels not seen since 2020. Notably Asian currencies were not affected, JPY retraced last weeks' gains in an inside week, and AUD and NZD outperformed the dollar, the former on rate hike hints. An actual rate hike in Canada was already priced and the currency hardly moved.


WEEKLY PRICE MOVEMENT

The biggest index mover was Ukraine-sensitive DAX, down 10.11%. The top forex mover was EURAUD down 5.11%. Bitcoin and Ethereum were fairly flat. Some of the FANGs performed a lot worse than NDX, although in general tech underperformed.

Last week's EURNZD short position made 4.68%, which means I am ahead 7.59% this year, with 5/8 (62.5%) wins. I will now reverse that position and buy EURNZD, as the rate hike hint may drive AUD up more.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.


NEXT WEEK

Although Ukraine is likely to dominate markets, the key day for schedule news is Thursday with the ECB simultaneous with US core inflation (ie without Ukraine factor-oil) which is estimated to make a new high. We also have inflation from Germany and China, US, Canada, China trade figures and GDP from Eurozone, UK and Japan.


CALENDAR  (all times are GMT, volatile items in bold)

Monday March 7
02:00 China Imports/Exports/TB
07:00 Germany Factory Orders
09:00 Germany Retail Sales (time approx.) (e9.5% p0%)
23:50 Japan Current Account

Tuesday March 8
10:00 Eurozone GDP (QoQ e0.3% p0.3%)
13:30 US Trade Balance
13:30 Canada Trade Balance
22:15 RBA Governor Lowe speech
23:30 Aus Westpac Consumer Confidence
23:50 Japan GDP (e1.4% p1.3%)

Wednesday March 9
01:30 China CPI/PPI
08:00 RBA Debelle speech

Thursday March 10
00:00 Aus Consumer Inflation Expectations
12:45 ECB Rate Decision/Statement (e0% hold)
13:30 ECB Press Conference
13:30 US CPI (Core e6.4% p6.0%)
13:30 US Jobless Claims
19:00 US Monthly Budget Statement
22:15 RBA Governor Lowe speech
23:30 Japan Overall Household Spending

Friday March 11
07:00 UK GDP
07:00 UK Ind/Mfr Production
07:00 Germany CPI (e5.5% p5.5%)
13:30 Canada NFP/AHE/UnEmp (UE e6.2% p6.5%)
15:00 Michigan CSI (e61.3 p62.8)

Sunday, 27 February 2022

Week to Feb 25th

Russia invades Ukraine. Markets recover in hours.
MY CALL THIS WEEK : SELL EURNZD


LAST WEEK

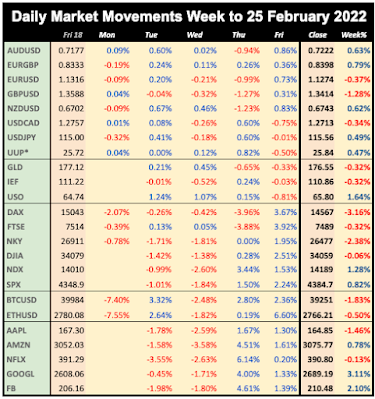
As we mentioned last week, the primary driver of markets this week was the invasion of Ukraine by Russia, the first war on European soil since the Kosovo in 1999. Markets fell hard on Thursday morning and gold, oil and the dollar surged in classic form. However, the moves were quickly reversed, and SPX and NDX both ended the week up, and DJIA was flat. The dollar and yields were up overall, the latter not really reacting to the Ukraine issue. The RBNZ rate hike was priced in, and had no effect on NZD. Gold and oil both tracked the dollar.


WEEKLY PRICE MOVEMENT

The biggest index mover was Ukraine-sensitive DAX, down 3.16%. The top forex mover was GBPAUD up 1.91%. Bitcoin and Ethereum were flat, as was FANG.

Last week's AUDNZD long position made 0.08%, which means I am ahead 2.91% this year, with 4/7 (57%) wins. I think EUR is going to react to Ukraine, and so sell it against NZD. I am avoiding AUD as there is a rate decision statement.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.

NEXT WEEK
Next week sees a new month, and therefore NFP, which at 400k estimate is similar to last month's print. Ukraine is still expected to dominate the general headlines, although Australian and Canadian rate decisions and Aussie and Canadian inflation will have an effect in the forex area.

CALENDAR  (all times are GMT, volatile items in bold)

Monday February 28
23:50 Japan Ind Production (Sun)
23:50 Japan Retail Sales (Sun)
00:00 Aus TD Securities Inflation
00:30 Aus Retail Sales (p-4.4%)
13:30 Canada Current Account
14:45 Chicago PMI
21:30 Aus AiG Mfg Index

Tuesday March 1
01:00 China PMIs
01:45 China Caixin Mfr PMI
03:30 RBA Rate Decision/Statement (e0.1% hold)
07:00 Germany Retail Sales (p0%)
08:55 Germany Markit Mfr PMI
09:30 UK Markit Mfr PMI
13:00 Germany CPI (e5.3% p5.1%)
13:30 Canada Q4 GDP (p5.4%)
14:30 Canada Markit Mfr PMI
14:45 US Markit Mfr PMI
15:00 ISM Mfr PMI (e58.0 p57.6)
18:30 BoE Saunders speech

Wednesday March 2
00:30 Australia Q4 GDP (e0.5% p-1.9%)
08:55 Germany UnEmp Change/Rate
10:00 Eurozone HICP (CPI) (Core p2.3%)
10:30 DE10Y Bond Auction
13:15 US ADP (e328k p-301k)
15:00 BoC Rate Decision/Statement (e0.25% hold)
19:00 Fed Beige Book
20:00 BoE Cunliffe speech
21:30 Aus AiG Construction Index
22:00 Aus Commonwealth Bank Services PMI

Thursday March 3
00:30 Aus Imports/Exports/TB (TB p8.36B)
01:45 China Caixin Services PMI
08:55 Germany Markit Comp PMI
09:00 Eurozone Markit Comp PMI
10:00 Eurozone UnEmp Rate
12:30 ECB MPC Minutes
13:30 US Jobless Claims
14:45 US Markit Comp/Svcs PMIs
15:00 US Factory Orders
15:00 ISM Svcs PMI (e 61 p59.9)
23:30 Japan Jobs/UnEmp

Friday March 4
07:00 Germany Trade Balance
10:00 Eurozone Retail Sales (p2%)
13:30 US NFP/AHE/UnEmp (NFP e400k p467k)
15:00 Canada Ivey PMI

Sunday, 19 September 2021

Week to Sep 17th

Equities down, dollar up into OpEx, Oil bucks trend
MY CALL THIS WEEK : BUY EURNZD


LAST WEEK

Equity markets were weak across the board, with notably DJI outperforming NDX by 0.71%, and only recent star NKY posting a green candle to a new eight month high. The fade was exacerbated by OpEx on Friday, with indices closing at lows. After several moribund days, the dollar rose sharply on Thursday’s blowout Retail Sales figure, where the monthly ‘Control Group’ ie core printed +2.5% vs a -0.1% estimate (raw figure was +0.7% vs -0.8%). USDJPY rose 0.27% in 10 minutes, and 0.41% in an hour. DXY closed the week at a four-week high. Gold tracked the dollar to touch five-week lows. 10-year yields (and the 10-2 curve) stayed range bound, although notably the long curve (30-10) touched 0.536%, an 18-month low. It was a good week for oil bulls (and thus XLE +3.20% against -0.57% SPX), but of course, adding fuel to the fire (excuse the pun) of the global transport supply and cost crisis. (Notably DJT -0.67%) fell further than SPX.


WEEKLY PRICE MOVEMENT

The biggest mover this week was FTSE, down 0.93%, making an 8-week low and back under 7,000. The top forex mover was AUDUSD this week, down 1.02%. Bitcoin and ETH were slightly up. FANGs generally followed NDX.

My EURNZD buy made 0.32% taking my year to date profit to 7.20% and 26/36 wins. I will stay with buying EURNZD as this move does not appear to be done yet.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.


NEXT WEEK (all times are GMT)

The key event in the penultimate week of September is the FOMC meeting. A rate hold is 100% priced in, but traders will be looking for firm hints, or possibly even a calendar for the taper program, although this is hampered by the poor jobs print this month. There are also three other rate decisions, in China, Japan and UK. Other than that, only PMI data is of any significance.


CALENDAR (High volatility items in bold)

Monday September 20
06:00 Germany PPI

Tuesday September 21
01:30 RBA Meeting Minutes
12:30 US Building Permits/Housing Starts

Wednesday September 22
00:30 Aus Westpac Leading Index
01:30 PBoC Interest Rate Decision (e3.85% hold)
02:00 RBA Bullock speech
03:00 BoJ Rate Decision/Statement (e-0.1% hold)
06:00 BoJ Press Conference
14:00 Eurozone Consumer Confidence
18:00 Fed Rate Decision/Statement (e0.25% hold)
18:30 FOMC Press Conference
23:00 Aus Commonwealth Bank PMIs

Thursday September 23
07:30 Germany Markit PMIs (Mfr e65.0 p62.6)
08:00 Eurozone Markit PMIs (Comp e59.7 p59.0)
08:30 UK Markit Mfr/Svcs PMI (Svcs p55.0)
11:00 BoE Rate Decision/Statement (e0.1% hold)
12:30 US Jobless Claims
12:30 Canada Retail Sales (e4.4% p4.2%)
13:45 US Markit PMIs

Friday September 24
08:00 Germany IFO Sentiment Indicators
14:00 New Home Sales (MoM)(Aug)

Saturday, 11 September 2021

Week to Sep 10th

NDX outperforms, NKY rally continues, Currencies flat
MY CALL THIS WEEK : BUY EURNZD


LAST WEEK

In a week of continued heavy rotation, the NDX was the only stock market to make new all-time while the NKY rally continued unabated. Central bank tapering once more dominated the narrative, with the RBA, the BoC and the ECB all taking turns in the spotlight. In a small but potentially significant hawkish shift, the ECB lowered its asset purchases if only to restore them to previous levels. This did little to shift a sluggish Euro and EU yields actually dropped sharply following the meeting. Meanwhile, the USD traded an inside week while US 10-year yields made a new recovery high only to fade again.


WEEKLY PRICE MOVEMENT

The biggest mover this week was again NKY, up 4.30% bucking the trend elsewhere. The top forex mover was AUDUSD this week, up 1.38%. Bitcoin and ETH fell sharply. FANGs were very mixed.

My GBPCAD buy made 1.14%, reversing last week's loss, and taking my year to date profit to 6.88% and 25/35 wins. This week I am buying EURNZD, it seems to be at support. This NKY rally will end and JPY will rally, but not yet.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.


NEXT WEEK (all times are GMT)

Next week is lighter than usual on data, with inflation the main focus, as the US, UK, Canada and Eurozone report. However, as inflation has already reached 'the target' for taper everywhere except Eurozone, the prints assume less significance than in previous months. Friday is quarterly OpEx, the so-called triple witching, which includes the important index options (SPY, QQQ etc.). Markets will probably spend the whole week looking for clues to the Fed 22 September meeting.


CALENDAR (High volatility items in bold)

Monday September 13
18:00 US Monthly Budget

Tuesday September 14
01:30 Aus House Price Index
04:30 Japan Industrial Production
06:00 UK Claimant Count/AHE/UnEmp (UnEmp e4.8% p4.7%)
12:30 US CPI (MoM e0.3% p0.3%)

Wednesday September 15
00:30 Aus Westpac Consumer Confidence
02:00 China Retail Sales (YoY e11.5% p8.5%)
06:00 UK CPI (YoY e2.3% p2.0%)
09:00 Eurozone Labor Cost/Ind Production
12:30 Canada BoC CPI (p3.3%)
23:50 Japan Imports/Exports/TB

Thursday September 16 
01:00 Aus Consumer Inflation Expectations
01:30 Aus NFP/UnEmp (UnEmp e5.0% p4.6%)
12:30 US Retail Sales (Control Group Aug e-0.1% p-1%)
12:30 Philly Fed Manufacturing Survey
12:30 US Jobless Claims

Friday September 17
06:00 UK Retail Sales
09:00 Eurozone CPI
14:00 Michigan CSI

Monday, 29 March 2021

Week to Mar 26th

Powell/Yellen Testimony to Congress, Dollar breakout, Indices Consolidate
MY CALL THIS WEEK : SELL EURNZD


The Powell/Yellen testimony was considered hawkish (by current standards) pushing stocks down and the dollar up. Otherwise, another consolidation week, except for the dollar. Other asset classes either posted a true inside week (US10Y, Gold, DAX) or closed in last week’s range (all indices, Oil). DXY however hit new five-month highs. News-wise, there were few shocks, other than a wild unsustained spike in Gold on Thursday.


Next week sees the end of the month and first quarter, and of course another Non-Farm payrolls, this time with the highest estimate since November. It is Easter week, with four days trading into a four day holiday in many territories. An OPEC meeting on Thursday may break the current Oil consolidation. Other than that, a raft of PMIs, and European inflation (showing Germany breaking apart from the zone as a whole) complete a generally busy week.


Mon Mar 22

Markets rose today although only later in the day after yields had fallen. Slight concern about vaccinations meant COVID-immune NDX outperformed. There is also a notable correlation between bonds and NDX. The dollar continued the rally it started last week, pushing currencies and Gold down. Oil tends to run with industrials, as with DJI the weakest index today, it fell very slightly. Bonds were up.


Tuesday March 23

TreasSec Yellen’s hawkish assessment today, where she expected the US to return to full employment in 2022, which of course indicates an unwinding of QE. Stocks fell, NDX less so, as it is less affected by this. The dollar of course liked it, and was sharply up, meaning Gold, Oil and yields fell both in line with the dollar and equities.


Wednesday March 24

Upbeat PMI data pushed up traditional value stocks today, at the expense of tech, with energy stocks (and Oil) both up on the Suez Canal closure. Simple supply and demand. Less of the former, latter is constant. However everything fell again into the close after another day’s testimony from Powell and Yellen. The dollar continued upwards, and Gold was down in line. Bonds were up for a third day.


Thursday March 25

A weak auction of 7-year paper caused a reversal back down in bonds today. The equity market was up (SPX +0.52%) but again NDX notably underperformed (-0.14%). The dollar rallied for a third day, hitting a five-month high after two weeks of consolidation, pushing Gold and Oil down. When equities are only mildly positive, and the dollar moves strongly, Oil reflects the latter.


Friday March 26

The day was positive, but most of the rally was in the last hour, putting the indices in positive territory for the week. The dollar reversed after three strong days, and this was reflected in Gold and Oil, the latter being assisted by the Suez issue. Bonds were down in line with the equity rally.


WEEKLY PRICE MOVEMENT

Yet another consolidating week for all assets except the dollar. The top index mover was NKY, down 2.07% although 0.63% of this can be attributed to JPY’s move. The top forex mover was NZDUSD down 2.08%. Crypto pulled back slightly, and FANGs slightly underperformed NDX.

I wish I’d stuck with JPY for a third week, but my short of GBPUSD was up 0.57%. Total to date -1.78%, with 7/12 win. This week I think the NZD drop is overdone, and will sell EURNZD


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.


Next week sees the end of the month and first quarter, and of course another Non-Farm payrolls, this time with the highest estimate since November. An OPEC meeting on Thursday may break the current Oil consolidation. Other than that, a raft of PMIs, and European inflation (showing Germany breaking apart from the zone as a whole) complete a generally busy week.


NEXT WEEK (all times are GMT)

(Calendar High volatility items are in bold)


  • Four day Easter week
  • Non-Farm Payrolls
  • UK and Germany inflation
  • OPEC and PMIs


Monday March 29


FTSE Russell should confirm that Chinese government bonds are included in their World Index today. If so, this is bullish for an already extended CNY.


23:30 Japan Jobs/Unemployment

23:50 Japan Retail Sales


Tuesday March 30

Two Fed speakers today, as we move into the close of the quarter.


09:00 Eurozone Consumer Confidence/Business Climate

12:00 Germany CPI (e2.0% p1.6%)

13:00 US Housing/Home Price Indices

13:00 Fed Quarles speech

14:00 US Consumer Confidence(Mar)

18:30 Fed Williams speech

23:50 Japan Industrial Production


Wednesday March 31

The final day of Q1 sees a speech from President Biden. There is a rate decision in Colombia. There is plenty of news, so expect EOQ volatility.


00:30 Aus Building Permits

01:00 China PMIs (Mfr e51.0 p50.6)

06:00 UK Q4 Final GDP (e1.0% prelim1.0%)

07:55 Germany Unemployment Rate/Change

09:00 Eurozone CPI (YoY e0.9% p0.9%)

12:15 US ADP Employment Change (e550k p117k)

12:30 Canada Q4 GDP (MoM)

13:45 Chicago PMI

14:00 US Pending Home Sales

21:30 Aus AiG Performance of Mfg Index

23:50 Tankan Large Manufacturing Index (e0 p-10)


Thursday April 1

The new month and quarter being. There is an OPEC meeting today, and production cuts are expected to be maintained. Look out for any news on the Ever Given, which has effectively closed the Suez Canal. Norway and Denmark are closed for Maundy Thursday.


00:30 Aus Imports/Exports/TB (TB e9.5B p1.01B)

00:30 Aus Retail Sales (e-1.1%, p-1.1%)

01:45 Caixin Mfr PMI

06:00 Germany Retail Sales (e1.3% p-8.7%)

07:55 Germany Markit Mfr PMI

08:00 Eurozone Economic Bulletin

08:30 UK Markit Mfr PMI

12:30 US Jobless Claims

13:30 Canada Markit Mfr PMI

13:45 US Markit Mfr PMI

14:00 US ISM Mfr PMI (e61.2 p60.8)


Friday April 2

Markets are closed in most countries including the US and all of Europe for Good Friday. Markets will be closed for four days (Easter Monday) in many countries. Today is NFP, with the highest jobs estimate since November.


12:30 US NFP/AHE/UnEmp (NFP e655k p379k)

Monday, 25 January 2021

Week to Jan 21st

Biden inauguration, Generally strong earnings, Yellen supports stimulus
MY CALL FOR THIS WEEK : BUY EURNZD


Good data out China gave the MLK holiday futures and non-US markets a kick-start. Then, the four-day trading week saw Joe Biden inaugurated as the 46th President of the USA and immediately rejoin WHO and the Paris Accord. John Roe of L&G said “The concept of a United States that isolates itself … is being reversed very rapidly and that is good for international co-operation, international law and international trade.”. Also TreasSec nominee Janet Yellen support the call for Biden’s $1.9Tr stimulus package. All this, plus strong earnings, resulted in a strong risk-on week, with all indices up, and risk index NDX outperforming, although with early technical signs of fragility.


Oil, Gold, the yen and the Dollar continued to range, either repeating or reversing last week’s move. They were joined this week by yields, as the US10 posted an inside week. Bitcoin continued to retreat, now 23% down in two weeks.


Earnings season steps up for the final week of January, as the two largest (free-float) companies in the world, AAPL and MSFT, ’cult’ stock TSLA, and Dow giants BA, V, JNJ, MMM and AXP all report. The tone of the season should be set by the end of the week. The Fed rate decision meeting is on Wednesday, and all eyes will be looking to see how close Chair Powell is aligned to his predecessor who spoke last week. First readings of US and German GDP for Q4 will show the extent of the COVID economic recovery. And don’t forget end-of-month sentiment positioning moves. February does not have the same magic cachet, and traders may try to front-run a pullback.


Monday January 18

MLK Day opened with strong Chinese data, which pushed European indices and US futures up. Unlike FTSE, DAX was firmly up, but in the absence of US money, other asset classes such as USD, Oil and Gold were generally flat. Bond markets were closed.


Tue Jan 19

Today Treasury Secretary nominee, and former Fed Chair Janet Yellen voiced strong support for the Biden $1.9Trn relief package. GS reported blowout earnings, however their shares fell slightly. Nevertheless the general trend was upwards with SPX up 0.8% and NDX outperforming adding 1.5%. Oil was also up, and Bonds and Gold were down in line, although not by much.


Wednesday January 20

Today was pure inauguration enthusiasm, with a gap-up rally, with SPX and NDX at new highs, helped enormously by a 17% rise in NFLX after beating on subscriber estimates and hinting at buybacks (the engine of rallies). The SPX inauguration rally was the biggest since Ronald Reagan’s in 1985. All the FANG stocks outperformed. Surprisingly Oil was flat, and Gold, after a sharp dip around inauguration time ended up on the day, as did Bonds and the yen. The dollar overall was more or less flat after a choppy day.


Thursday January 21

President Biden moved immediately today to rejoin WHO and the Paris Accord, and to scrap the Muslim travel ban. John Roe of L&G said “The concept of a United States that isolates itself … is being reversed very rapidly and that is good for international co-operation, international law and international trade.”. Markets made new highs, but only just, given the strength of the rally to date. Bonds were down in line, and Gold was flat. However Oil was slightly down. The dollar continued downwards, with no significant change on the ECB press conference.


Friday January 22

After rallying all week, markets took a breather and pulled back slightly today, with some scepticism about the speed of the stimulus package. SPX was down 0.3%. Oil was down and Bonds were up in line. A safe haven dollar once again rose, more than yen, for once, and of course Gold was up in line with both the dollar and the mood.


WEEKLY PRICE MOVEMENT

NDX substantially outperformed this week, up 4.39%, more than twice that of any other index. The top forex mover was NZDCAD up 1.0%. Bitcoin fell again, down nearly 10%. FANGs were superb, all outperforming even NDX.


Last time, I was right about EURGBP, however it only made 0.11%, totalling 1.23% (3/3 wins). This week I'll go back to buying EURNZD


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.


NEXT WEEK (all times are GMT)

(Calendar High volatility items are in bold)


Monday January 25

As is often on Mondays, a quiet start to the week.


09:00 Germany IFO – Business Sentiment Reports

13:30 Chicago Fed National Activity Index

23:50 BoJ MPC Minutes


Tuesday January 26

The first big earnings day of the week with JNJ, MMM and AXP (together 9.74% of DJIA) all reporting before the bell, and MSFT (8.95% of NDX) reporting after the close. Macro data on the day is light.


07:00 UK UnEmp/AHE (UnEmp e5.1% p4.9%)

14:00 US Housing/Home Price Indices

15:00 US Consumer Confidence

23:30 Aus Westpac Leading Index


Wednesday January 27

Troubled Dow giant BA reports before the bell, but all the action today comes towards the end. At 1900 the Fed will indicate where they stand on COVID and stimulus, and then after the bell we have reporting from AAPL, TSLA and FB, together 21% of NDX by weight.


00:30 Australia CPI (e1.5% p1.6%)

07:00 Germany Gfk Consumer Confidence Survey

10:00 DE10Y Bond Auction (time approx.)

13:30 US Durable/ND Capital Goods (Durables e0.9% p1.0%)

19:00 Fed Rate Decision/Statement/Presser (e0.25% hold)

23:50 Japan Retail Sales


Thursday January 28

The first reading of US Q4 GDP today will give a feel for normal growth, as the previous quarter (33.4%) was based on the extremely low March base. Dow regulars report today; MCD before the bell, and V after the close.


10:00 Eurozone Consumer Confidence/Business Climate

13:00 Germany CPI (e-0.6% p-0.7%)

13:30 US PCE (QoQ)

13:30 US Jobless Claims

13:30 US Q4 GDP Prelim (e4.4% p33.4%) 

15:00 US New Home Sales

23:30 Japan Tokyo CPI

23:30 Japan Jobs/Unemployment

23:50 Japan Industrial Production


Friday January 29

More Dow components CAT, CVX and HON report today before the bell. In macro news, the Canadian GDP and Michigan Consumer Sentiment are important.


08:55 Germany Unemployment Rate/Change

09:00 Germany Q4 Prelim GDP (p8.5%)

13:30 US PCE (MoM and YoY)

13:30 Canada Q4 GDP (MoM)

14:45 Chicago PMI

15:00 Michigan CSI