Showing posts with label NDX. Show all posts

Saturday, 30 April 2022

Week to Apr 29th

                                           NDX worst YTD ever, DXY at 5yr highs
MY CALL THIS WEEK : BUY GBPAUD


LAST WEEK

In the last week of April, continued volatility created some ominous monthly candles. NDX was down –13.3%, its largest monthly decline since 2008 and the worst start to the year ever, helped along by poor earnings from the likes of GOOGL and AMZN. A close at the low of the week and month suggests May should start off weak (more on this later) but there will then be a window to reverse from further lows. Indeed, the intra-week pattern next week could follow the same general pattern as last week, and the week before; that is early weakness leads to a mid-week bounce followed by a late sell off into Friday’s close.


WEEKLY PRICE MOVEMENT

The biggest index mover was rate-sensitive NDX for the third week, down 3.76%, nearly 14% in four weeks. The huge weight of AMZN, who missed on earnings, also affected SPX. The top forex mover was EURUSD down 2.67%. Bitcoin and Ethereum fell again, and FANGs severely underperformed, with NFLX now down 73% in six months. Once again AAPL was relatively unscathed.

Last week's EURUSD short position gained 2.67%, which means I am ahead 8.80% this year, with 9/15 (60%) wins. This week I am betting the BoE will be more hawkish than the RBA and buying GBPAUD.
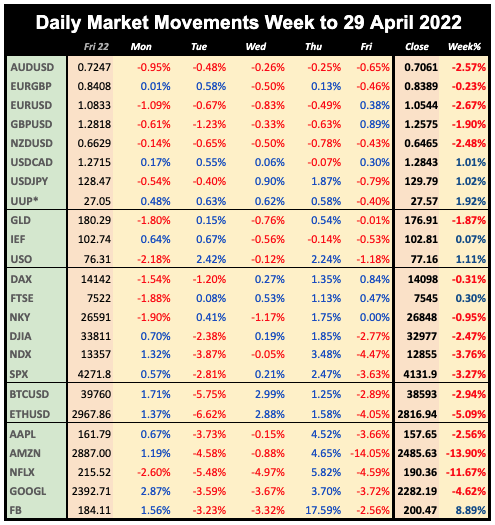


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.


NEXT WEEK

The big index names have now reported, so the focus moves back to macro, and the key event of the week is the Fed, now expected to raise rates by 50bp on Wednesday. This is 99% priced in at CME Fedwatch, and so there ought to be a small relief rally (sell the rumor, buy the news) because it is not 75bp. As previously stated, the problem area of the Fed's dual mandate is inflation, not jobs, which are recovering steadily, meaning that NFP is not the primary focus, although there will no doubt be a short-term reaction to the upside on either a big miss or a strong beat.

Elsewhere rate hikes are also expected in Australia and the UK. The two currencies have had rather difference recent history, with AUD strong and GBP weak. Certainty on the rate hike path may normalise things. Other news is less important, with a raft of PMIs from S&P (replacing Markit) only ISM PMIs really stand out, and would have to be well wide of estimates to make a difference.

Japan is closed Monday to Thursday, and the UK is closed on Monday, meaning forex will be low volume.


CALENDAR  (all times are GMT, volatile items in bold)

Monday May 2
06:00 Germany Retail Sales (p7%)
07:55 Germany S&P Mfr PMI
09:00 Eurozone Business/Consumer Confidence
13:30 Canada S&P Mfr PMI
13:45 US S&P Mfr PMI
14:00 US ISM Mfr PMI (e58.0 p57.1)
23:30 RBA Ellis speech

Tuesday May 3
01:00 Aus TD Securities CPI
04:30 RBA Rate Decision/Statement (e0.25% p0.10%)
07:55 Germany Unemp
08:30 UK S&P Mfr PMI
09:00 Eurozone Unemp
13:00 ECB President Lagarde speech
14:00 US Factory Orders
16:30 BoC Rogers speech
22:30 Aus AiG Construction Index
23:00 Aus S&P Services PMI

Wednesday May 4
01:30 Aus Retail Sales (e0.5% p1.8%)
06:00 Germany Trade Balance
07:55 Germany Composite PMI
08:00 Eurozone Composite PMI
09:00 Eurozone Retail Sales (e1% p5%)
09:30 DE10Y Bond Auction
12:15 US ADP (e370k p455k)
12:30 US Trade Balance
12:30 Canada Trade Balance
13:45 US S&P Comp/Svcs PMI
14:00 US ISM Services PMI (e59.0 p58.3)
18:00 Fed Rate Decision/Statement (e1.0% p0.5%)
18:30 FOMC Press Conference

Thursday May 5
01:30 Aus Building Permits
01:30 Aus Trade Balance
01:45 China Caixin Svcs PMI
06:00 Germany Factory Orders
08:00 OPEC Meeting
10:30 ECB Lane speech
11:00 BoE Rate Decision/Statement
11:30 BoE Governor Bailey speech
12:30 US Jobless Claims
13:40 BoC Schembri speech
23:30 Tokyo CPI

Friday May 6
01:30 RBA MPC Minutes
12:30 US NFP/AHE/UnEmp (NFP e400k p431k)
12:30 Canada NFP/AHE/UnEmp (UnEmp e5.4% p5.3%)
14:00 Canada Ivey PMI

Sunday, 24 April 2022

Week to Apr 22nd

Markets hit by Fed comments. 50bp hike looms.
MY CALL THIS WEEK : SELL EURUSD


LAST WEEK

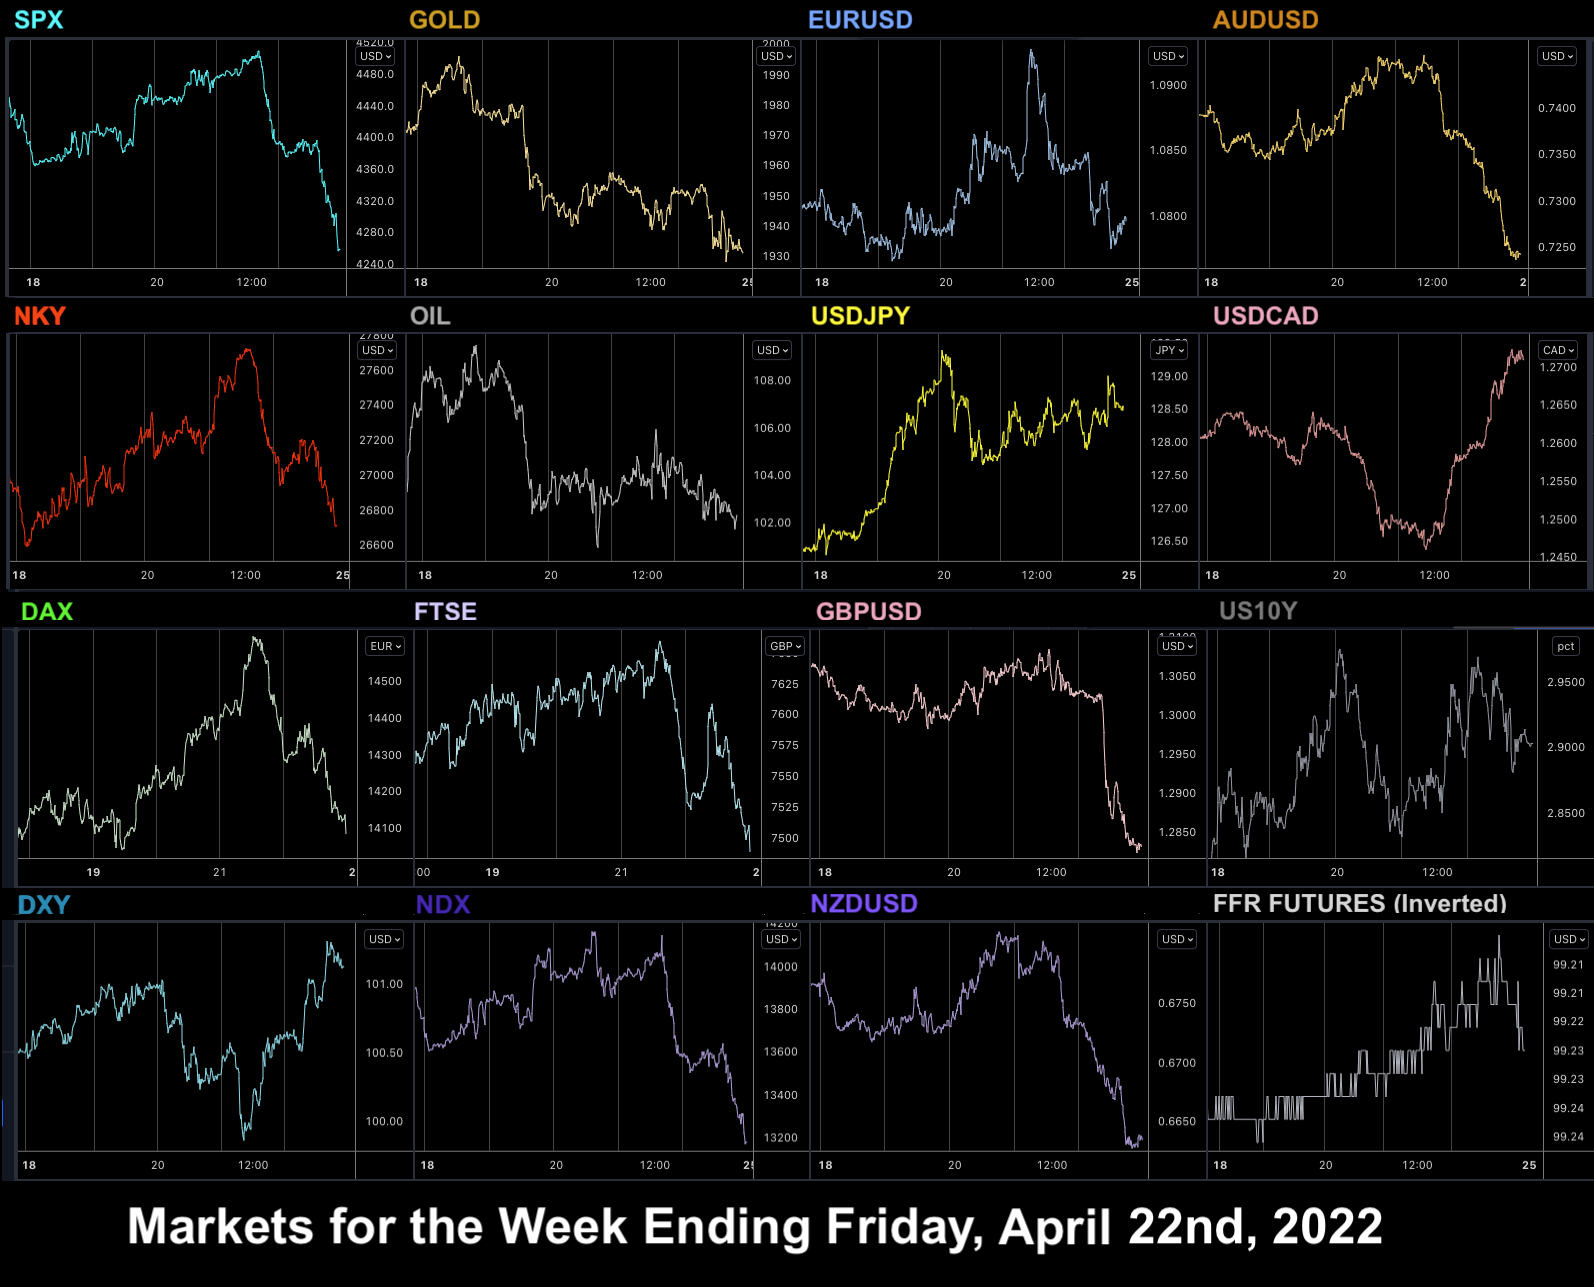
Stock markets managed a few strong sessions but faded following more hawkish Fed signals indicating the May rate hike would be 50bp not 25bp. DAX and NKY were relatively unscathed, but US markets dropped to new April lows by the end of the week and the weak close presents a similar situation to last week—continuation is likely on Monday and Tuesday.


WEEKLY PRICE MOVEMENT


The biggest index mover was rate-sensitive NDX which was down 3.98%, over 7% in two weeks. Clearly rates are still the issue, as other indices moved much less. The top forex mover was EURNZD up 2.19%. Bitcoin and Ethereum pulled back again, and FANGs severely underperformed, after NFLX reported the first reduction in subscribers for a decade. Only AAPL was relatively unscathed.


Last week's EURAUD long position gained 2.17%, which means I am ahead 6.13% this year, with 8/15 (53%) wins. This week I am selling EURUSD.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.


NEXT WEEK


Next week is the big week for earnings, in particular for NDX, with over 42% by weight of the index (including AAPL MSFT GOOGL INTC FB) reporting. These companies are also 22% of SPX. NDX has been severely hit by the rate hike narrative, and entered bear market territory last week. Focus will be in all cases on unit metrics rather than just earnings and revenue. News from the US is again light, with only Durable Goods and GDP of note. Inflation is reported from Australia, Eurozone and Germany, and again estimates show it is still increasing.


CALENDAR  (all times are GMT, volatile items in bold)


Monday April 25

08:00 Germany IFO Sentiment

15:00 BoC Governor Macklem speech

15:00 BoC Rogers speech


Tuesday April 26

12:30 US Durable/ND Capital Goods (DG e1.0% p-2.1%)

12:55 BoC Lane speech

13:00 US Housing/Home Price Indices

14:00 US Consumer Confidence

14:00 US New Home Sales


Wednesday April 27

01:30 Australia CPI (RBA Mean e1.2% p1.0%)

14:00 US Pending Home Sales

23:50 Japan Retail Sales


Thursday April 28

03:00 BoJ Rate Decision/Statement (e-0.1% hold)

06:00 BoJ Press Conference

09:00 Eurozone Consumer Confidence

12:00 Germany CPI (e7.6% p7.6%)

12:30 US Q1 GDP (e1.0% p6.9%)

12:30 US Jobless Claims

12:30 US PCE QoQ


Friday April 29

01:45 China Caixin Mfr PMI

06:00 Germany Q1 GDP (QoQ e0.2% p-0.3%)

09:00 Eurozone GDP (YoY e5.1% p4.6%)

09:00 Eurozone CPI (Core e3.1% p2.9%)

12:30 US PCE MoM & YoY

12:30 Canada GDP

13:45 Chicago PMI

14:00 Michigan CSI

Sunday, 26 December 2021

Week to Dec 24th

Christmas 4-day week, Santa brings new SPX ATH
MY CALL THIS WEEK : SELL AUDNZD


THIS WEEK

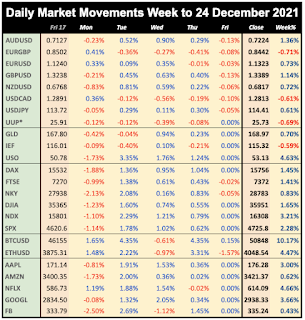
In this shortened Christmas week, markets dropped hard on Monday on Omicron fears and tighter restrictions including a lockdown in the Netherlands. However, news that omicron, whereas more transmissible is less serious, plus a lack of any bad news and of course the Santa effect drove markets up, with SPX making a closing ATH. Oil was up in line with equities, whereas DXY (and EURUSD) and Gold consolidated with inside weeks. Yields recovered most of last week's drop. Happy Christmas to all my readers.


WEEKLY PRICE MOVEMENT

The biggest index mover was NDX, up 3.21%, recovering last week's drop. The top forex mover was AUDJPY up 1.97%. Bitcoin and Ethereum were well up, and FANG outperformed NDX, except for AMZN.


Last week’s USDCAD short made 0.61%, taking my year to date profit to 6.44% and 34/51 wins. This week I will take the NZD catchup trade and short AUDNZD.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.


NEXT WEEK


The fact that the biggest releases in the final week of 2021 are housing stats and Chinese PMIs indicates how holidays are in full swing. US Markets are open all week, but volume is expected to be low. Germany is closed on Friday.


CALENDAR  (all times are GMT)


Monday December 27

23:30 Japan Jobs/Unemployment

23:50 Japan Industrial Production


Tuesday December 28

14:00 US Housing/Home Price Indices


Wednesday December 29

15:00 US Pending Home Sales


Thursday December 30

13:30 US Jobless Claims

14:45 Chicago PMI


Friday December 31

01:00 NBS Manufacturing PMI

01:00 Non-Manufacturing PMI

Saturday, 11 September 2021

Week to Sep 10th

NDX outperforms, NKY rally continues, Currencies flat
MY CALL THIS WEEK : BUY EURNZD


LAST WEEK

In a week of continued heavy rotation, the NDX was the only stock market to make new all-time while the NKY rally continued unabated. Central bank tapering once more dominated the narrative, with the RBA, the BoC and the ECB all taking turns in the spotlight. In a small but potentially significant hawkish shift, the ECB lowered its asset purchases if only to restore them to previous levels. This did little to shift a sluggish Euro and EU yields actually dropped sharply following the meeting. Meanwhile, the USD traded an inside week while US 10-year yields made a new recovery high only to fade again.


WEEKLY PRICE MOVEMENT

The biggest mover this week was again NKY, up 4.30% bucking the trend elsewhere. The top forex mover was AUDUSD this week, up 1.38%. Bitcoin and ETH fell sharply. FANGs were very mixed.

My GBPCAD buy made 1.14%, reversing last week's loss, and taking my year to date profit to 6.88% and 25/35 wins. This week I am buying EURNZD, it seems to be at support. This NKY rally will end and JPY will rally, but not yet.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.


NEXT WEEK (all times are GMT)

Next week is lighter than usual on data, with inflation the main focus, as the US, UK, Canada and Eurozone report. However, as inflation has already reached 'the target' for taper everywhere except Eurozone, the prints assume less significance than in previous months. Friday is quarterly OpEx, the so-called triple witching, which includes the important index options (SPY, QQQ etc.). Markets will probably spend the whole week looking for clues to the Fed 22 September meeting.


CALENDAR (High volatility items in bold)

Monday September 13
18:00 US Monthly Budget

Tuesday September 14
01:30 Aus House Price Index
04:30 Japan Industrial Production
06:00 UK Claimant Count/AHE/UnEmp (UnEmp e4.8% p4.7%)
12:30 US CPI (MoM e0.3% p0.3%)

Wednesday September 15
00:30 Aus Westpac Consumer Confidence
02:00 China Retail Sales (YoY e11.5% p8.5%)
06:00 UK CPI (YoY e2.3% p2.0%)
09:00 Eurozone Labor Cost/Ind Production
12:30 Canada BoC CPI (p3.3%)
23:50 Japan Imports/Exports/TB

Thursday September 16 
01:00 Aus Consumer Inflation Expectations
01:30 Aus NFP/UnEmp (UnEmp e5.0% p4.6%)
12:30 US Retail Sales (Control Group Aug e-0.1% p-1%)
12:30 Philly Fed Manufacturing Survey
12:30 US Jobless Claims

Friday September 17
06:00 UK Retail Sales
09:00 Eurozone CPI
14:00 Michigan CSI

Sunday, 19 July 2020

Week to Jul 17th

Earnings season opens, Shift out of tech, Gently declining dollar
MY CALL THIS WEEK : SELL GBPCAD


This week saw positive news, both on the vaccine front, and in comments from Fed Governor Brainard (admittedly a known dove) suggest even further stimulus. However, the COVID cases keep rising, and the net result was a fairly flat week with SPX attempting and failing to break 3235 twice, and NDX down. The pullback in the tech/industrial ratio is the most noticeable feature of this week’s market, and it was accelerated by NFLX missing on earnings, against beats by JPM, C and GS, the latter very strongly. The ratio has recently overshot the 2000 bubble level, had to happen at some point, although there is no reason it cannot go higher, as the NDX/SPX PE differential is nowhere near 2000 levels, indeed if anything it has fallen.

The ECB said nothing news, and the dollar chart was extremely similar to last week, slow and slight classic waves to the downside, and bonds and Gold were in consolidation at their current elevated level. JPY also consolidated and posted a flat week, as did Oil.

Next week sees more of earnings season, with the main event being MSFT and TSLA reporting late on Wednesday. The fact that Canadian inflation and a PMI batch on Friday are the main events tells you how light the week is. Earnings and COVID news should therefore set the tone.


Mon Jul 13
After rallying earlier in the day on vaccine hopes from BNTX (up 20%) and DJIA stock PFE, markets sold off sharply in the US afternoon session, possibly on news of a new closedown in California, but also a rejection of the previous post-COVID high of 3235 from Jun 8th. Oil fell in line. Gold and bonds were up, but not JPY which was down, despite a general flat dollar (the JPY move was matched by a GBP fade).


Tuesday July 14
Indices rebounded with DJIA outperforming NDX, as JPM and C beat estimates. But banks themselves were not in favour, it was the archetypal industrial CAT that was the best mega-cap performer, up 4.83%. The dollar fell some more, down across the board, and yields and Oil were up in line, although Gold was up slightly.


Wednesday July 15
Markets were up again today after a strong earnings beat by GS, more positive vaccine news from MRNA (up 7% and 16% at one point), There was a call by Fed Brainard for more stimulus, although Lael Brainard is a known dove, this was still a positive mover. Once again there was strong divergence against tech, with NDX only up 0.11%. Oil was up in line. Gold and Bonds were flat, and the dollar once again fell across the board.


Thursday July 16
We had a reversal today after a sharp pullback in the China 300 index (4.75% its worst day since February), and a  miss in the Initial Jobless Claims figure, but also linked to the 3235 post-COVID high, which was reached on Jun 8, and again yesterday. Despite earnings beats from JNJ and BAC, SPX was down 0.34%, and for a fourth day NDX underperformed, down 0.70%. NFLX missed on earnings after the bell, was was down 10% in after-hours trading, although the stock is not heavily weighted on NDX, so the index move was modest.

And for a fourth day, yields and Oil were up in line, and Gold wasn’t! The dollar also bounced back up (evenly across all currencies), meaning for a fourth day, the yen did not move inversely to indices. This is interesting in a rare week where industrials outperform tech, perhaps those industrials can be seen as the safe haven.


Friday July 17
In the absence of significant earnings releases, the final day of the week was fairly flat, but again with SPX outperforming NDX. Both indices failed to advance even 1%, and DJIA posted a red candle. Haven assets were mixed, with JPY and Gold up, but bonds slipping slightly. The dollar gave up Thursday’s gains, and Oil was slightly down. A directionless day to end a fairly directionless week, as seen in the total flat Fed Funds Rate chart. The only major trend was the shift away from tech.


WEEKLY PRICE MOVEMENT
Europe outperformed this week, with DAX the strongest index. The top forex mover was EURGBP up 1.68%. Cryptos continued to stay flat, BTC now only moves like any currency, and FANGS noticeably underperformed, even more so than NDX as a whole. with NFLX and AMZN (the two with sky-high P/E ratios) hit the hardest.

A better week for my forex call. I managed to pick the best mover EURGBP, adding the 1.68% to my running total gives gains of 7.16% (24wks 11 wins). This week, the picture is not much clearer, but CAD looks the strongest and GBP the weakest, so I will sell GBPCAD.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.


NEXT WEEK (all times are GMT)
(Calendar High volatility items are in bold)

  • Second week of earnings
  • Emphasis on tech
  • Canada inflation
  • PMIs on Friday

Monday July 20
As is often the case, news is light today. Traditional DJIA bellwether IBM (although less so these days) reports after the bell. Markets are closed in Colombia.

23:50 BoJ MPC Minutes (Sun)
23:50 Japan Imports/Exports/TB
01:30 PBoC Interest Rate Decision (e3.85% hold)
06:00 Germany PPI
15:10 BoE Haldane speech
15:10 BoE Tenreyro speech
23:30 Japan National CPI


Tuesday July 21
Again, little scheduled news in this holiday season. DJIA heavyweight KO reports before the bell.

01:30 RBA Meeting Minutes
02:30 RBA Governor Lowe speech
08:30 UK PSBR
12:30 Chicago Fed National Activity Index (Jun)
12:30 Canada Retail Sales (MoM May e21% p19.1%)


Wednesday July 22
A third day of uneventful news, means the key event comes after the bell, with NDX stalwart and 11.1% weight MSFT and recent market darling TSLA (now no 7 and 2.58% weight) reporting. TSLAs recent price moves have been quite amazing, rising 320% in four months.

00:30 Aus Westpac Leading Index (MoM)(Jun)
01:30 Australia Retail Sales
12:30 Canada CPI (BoC Core YoY e0.9% p0.7%)
13:00 US Housing Price Index (MoM)(May)
14:00 US Existing Home Sales (MoM)(Jun)


Thursday July 23
Jobless Claims is the first important US macro print in this quiet week, and another large NDX component (no 8 by weight) INTC reports after the bell. Markets are closed in Japan for Marine Day.

01:30 Aus NAB Business Confidence
06:00 Germany Gfk Consumer Confidence Survey(Aug)
11:00 BoE Haskel speech
12:30 US Jobless Claims
22:45 NZ Imports/Exports/TB (Jun)
23:00 Aus Commonwealth Bank Mfr PMI


Friday July 24
The Eurozone and German PMIs are expected to cross 50 today, the line between expansion and contraction. The US is already there of course. AXP reports before the bell. Markets are closed in Japan for Sports Day, which would have been the date of the Olympic opening.

06:00 UK Retail Sales
07:30 Germany Markit Mfr Prel PMI (e48.3 p45.2)
07:30 Germany Markit Composite Prel PMI (e50.3 p47.0)
07:30 Eurozone Markit Composite Prel PMI (e51.1 p48.5)
08:30 UK Markit Services Prel PMI (e51.0 p47.1)
13:45 US Markit PMIs
14:00 US New Home Sales

Sunday, 10 March 2019

Week to Mar 7th


Growth forecast cuts in China, Europe and Canada, Worst US TB since 2008

Mon Mar 04
Despite encouraging remarks from President Trump at the weekend, and another call for a weaker dollar, a rally in China during the Asian session did not prevent optimism from fading in the US markets and SPX close down 0.4%. DAX and NKY followed suit although FTSE advanced as GBP faded some its Brexit hopes gains. Yields fells on stock-bond rotation.
President Trump also called for a weaker dollar again, but this had no effect, with all currencies except JPY declining slightly, in line with the equity softening. Gold fell in line, although Oil managed to move up after Friday’s sharp fall.

Tuesday March 05
Mixed US data left equities directionless today. The situation was better in Europe after UK, German and Eurozone PMI beats at 0855, and DAX and FTSE were both up slightly. The dollar benefited from continuing EUR weakness ahead of the ECB meeting, with DXY advancing 0.24%, and CAD and JPY also fell slightly, and GBP was flat, as was Gold. Oil was choppy but ended slightly up, whereas yields fell for a second day. AUD hardly moved after the rate hold.

Wednesday March 06
Markets faltered again today on the US trade balance miss at 1330, the worst deficit since 2008, together with the ADP miss at the same time, and all indices were down, even FTSE. Yields were down 3.2bp, and JPY was up in line with the risk off mood. DXY was flat (as was Gold), with small recoveries (after two days decline) in EUR and GBP balancing a sharp drop in CAD (only 9.1% of the basket) after gloomy growth forecasts from the BoC at 1500 and mixed Ivey PMIs at the same time. AUD dropped sharply by nearly 1% on the Australian Q4 GDP miss. Oil ended slightly up, with the usual choppiness around the EIA print at 1530. The headline missed, but the Gasoline estimate beat.

Thursday March 07
Another day, another problem. Following the record US trade deficit and the BoC forecast, today the ECB downgraded growth forecasts for the giant Eurozone, and more significantly reversed policy from tightening (the end of bond buying in December) back to easing by a new TLTRO program. The forecast was expected, the TLTROs were not, and EUR fell 1.27% during the next six hours. US, Japanese (futures), and UK equities accelerated their fall. DAX had a short currency related spike up and then joined them.

DXY had its best day since June 2018, and rose 0.75%. As you would expect EURJPY moved even more (down 1.18%). Other currencies moved down, although notably, CAD did not suffer from its usual risk aversion, having softened the day before. Gold was flat. Oil was up slightly again, staying in the 56.50-57.50 range it has held all week. Yield were down again, following the rotation principle rather than the stronger dollar. This is showing that the dollar was not really stronger, it is just EUR that is weaker, as evidenced by the move down in USDJPY.

Friday March 08
The February NFP miss (20k vs 180k) at 1330 gave us three bad days in a row. Small misses sometime push equities up on the theory that they will delay rate hikes, but this was the third-worst print since 2011, following a stellar (311k) January. No tweet from Trump today! Markets all slid down further, although there was a small rally in the last hour. Notably China fell 4% in Asia well before the NFP release.

DXY was down 0.26%, giving back a third of its Thursday gains, with all currencies up, in particular big moves up in JPY and Gold, and down in Oil in line with the equity fade, although the latter recovered somewhat into the close. The Canadian NFP beat had a surprisingly modest effect, with USDCAD only down 0.28%, no more than DXY as a whole. Yields were down 5bp on rotation or dollar tracking.


WEEKLY PRICE MOVEMENT
Despite the stronger yen, NKY was the biggest index decline this week. The strong yen also made shorting GBPJPY (down 2.35%) the best forex trade of the week. Cryptos went to sleep again after a brief burst of activity last week. Another mixed week for FANGs with a surprisingly strong performance from FB.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on UUP. The equity and index prices are now based on the cash close each day.


NEXT WEEK 
(all times are GMT)
(Calendar High volatility items are in bold)
  • Yet another Brexit ‘high noon’
  • BoJ Rate Decision
  • US Inflation release
  • US/Europe DST disconnect

Monday March 11
Today is the first day of the bi-annual one-hour disconnect between the start of daylight saving (summer) time in North America and Europe. The first effect is the Retail Sales print, an hour earlier for European traders, coming after the worst figure since 2001 last month. Our times remain on GMT, as they will when Europe enters DST.


21:45 NZD NZ Electronic Card Retail Sales (Sunday)
00:00 EUR Eurogroup meeting (all day)
07:00 EUR Germany Industrial Production/Trade Balance
12:30 USD US Retail Sales Jan (Control Group est 0.6% prev -1.7%)
13:00 GBP BoE Haskel speech

Tuesday March 12
Today, we have another attempt by embattled UK PM Theresa May to get her Brexit deal through the British Parliament. The vote seems likely to fail again, at which point the saga moves to later votes in the week. US inflation (one leg of the Fed’s dual mandate) will inevitiably affect USD if it is well off estimates. Fed Chair Powell is due to speak at some time today (unconfirmed).

00:00 EUR EcoFin Meeting (all day)
02:15 CNY China FDI
06:30 AUD RBA Debelle speech
09:30 GBP UK Industrial/Manufacturing Production
09:30 GBP UK GDP MoM
12:30 USD US CPI (Core YoY est 2.1% prev 2.2%)
13:45 USD Fed Brainard speech
19:00 GBP UK Parliamentary vote on Brexit (time approx)
20:30 WTI API Oil Stock

Wednesday March 13
Provided the Tuesday vote fails (as expected), a (free) vote by UK MPs is expected to on whether it is acceptable to exit on Mar 29 without a deal. This is designed to be rejected, and almost certainly will be.  In the middle of this, the UK Spring Statement (Budget) is announced, with possible tax changes. A new US report, the unwieldy-titled Nondefense Capital Goods Orders ex Aircraft has been marked by commentators as important, more so that the normal Durable Goods release at the same time.

10:00 EUR Eurozone Industrial Production s.a. (MoM)
12:30 USD US Core PPI
12:30 USD US Durable Goods
12:30 USD US ND Capital Goods (est 0.1% prev -1%)
12:30 GBP UK Budget Report (time approx)
14:30 WTI EIA Oil Stock

Thursday March 14
If the two previous votes are rejected, today’s British Parliament vote is crucial. This will be to extend the exit date (probably to May 23). There may be amendments for a longer delay, or even a second referendum (polls suggest a new people’s vote would cancel Brexit). This is the least certain and therefore potentially the most volatile for GBP. China’s Industrial Production figures are important, given reactions to recent Chinese data. There is a rate decision on UAH (0.5% cut expected)

00:00 AUD Aus Consumer Inflation Expectations
02:00 CNY China Retail Sales/Industrial Production (YoY)
07:00 EUR Germany CPI (est 1.% prev 1.7%)
12:30 USD US Jobless Claims
14:00 USD US New Home Sales (MoM)
21:30 NZD Business NZ PMI
22:50 CAD BoC Wilkins speech

Friday March 15
After growth downgrades elsewhere last week, traders will be listening carefully for any similar views from the BoJ, so for once, this normally unimportant rate decision and statement may cause some JPY volatility. The Michigan Sentiment Index is estimated to fall further. The miss two weeks ago caused a sharp fall in SPX, and another could do the same.

02:00 JPY BoJ Rate Decision/Statement (est -0.1% hold)
10:00 EUR Eurozone CPI
13:15 USD US Industrial Production (MoM)
14:00 USD Michigan Consumer Sentiment Index (est 93.0 prev 93.8)
18:00 WTI Baker Hughes Rig Count


This report is published every week as an email by MatrixTrade.com - you can sign up to receive it here. This blog is supported solely by advertising, so if any of them interest you, please click the links. If you want notification when the blog is updated, please follow me on Twitter, Facebook, Stocktwits or Linkedin (all open in separate windows). Details of how I compile the report are here