Showing posts with label EURUSD. Show all posts

Sunday, 10 July 2022

Week to July 8th

DAX underperformance
MY CALL THIS WEEK : SELL EURUSD


LAST WEEK

In a shortened week due to Independence Day, European divergence and underperformance came to a head on Tuesday’s re-open as DAX dropped 3% to take out its March low and EURUSD dropped through 1.035 support, reaching 1.007 on Friday. Meanwhile, the SPX easily held last week’s low. Tuesday also saw the peak of the recent recession scare, with commodities down heavily and oil lower by 11%. The data highlight of the week came from the NFP, which with a solid beat and print of +372k, tells us the US economy is holding up extremely well despite all the recession talk. Expect the Fed to raise 75bps again in July.


WEEKLY PRICE MOVEMENT

The biggest index mover this week was NDX, up 4.66%. The top forex mover was EURNZD down 2.32%. Crypto recovered sharply again, and FANG outperformed NDX.

My EURCAD long lost 1.89% this week, meaning I am now ahead 2.91% with 13/25 (52%) wins. This week I have thrown in the towel and am shorting EURUSD.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.


NEXT WEEK

Each month in the past the main focus was on NFP week or Fed week, but these days the most importantly monthly print is CPI, due on Wednesday. The raw figure is estimated to increase yet again to 8.7% from 8.6%, but core inflation (stripping out food and, particularly, energy) is thought to fall again as it has done since the April peak of 6.5%. If this doesn't happen it could be bad for equity markets, whereas a miss (lower) on the headline rate would imply a Fed slowdown and boost recovery.

Earnings season for Q2 also starts next week, with, as always JPM first out of the gate, reporting on Thursday with MS, followed by WFC and C on Friday (GS report the following Monday to complete the opening quintet). UNH, at nearly 11% the largest component of DJIA also report on Friday. After the worst Q1 for decades, these releases will also be key, so overall, strong moves are possible ahead.


CALENDAR  (all times are GMT, volatile items in bold)

Monday, July 11
01:00 BoJ Gov Kuroda speech
18:00 US Monthly Budget Statement

Tuesday, July 12
09:00 Germany ZEW Sentiment
17:00 BoE Governor Bailey speech

Wednesday, July 13
00:30 Aus Westpac Consumer Confidence
02:00 China Imports/Exports/TB
06:00 UK GDP MoM
06:00 UK Ind/Mfr Production
06:00 Germany CPI (e8.7% p8.2%)
12:30 US CPI (Core e5.9% p6.0%)
14:00 BoC Rate Decision/Statement (e2.25% p1.5%)
15:00 BoC Press Conference
18:00 US Fed Beige Book

Thursday, July 14
01:00 Aus Consumer Inflation Expectations
01:30 Aus Jobs/UnEmp (Jobs e25k p60.6k)
04:30 Japan Ind Production
12:30 US Jobless Claims
12:30 US PPI

Friday, July 15
02:00 China GDP (QoQ e0.6% p1.3%)
02:00 China Ind Production
02:00 China Retail Sales (YoY e-7.1% p-6.7%)
12:30 US Retail Sales (MoM e-0.8% p-0.3%)
13:00 US Fed Index of Common Inflation Expectations (time approx.)
14:00 Michigan CSI (e58 p50)

Sunday, 15 May 2022

Week to May 13th

Early signs of a trend change
MY CALL THIS WEEK : BUY EURUSD


LAST WEEK


In a week that was light on data, but packed with significant action, the only real event worth mentioning was the CPI print out of the US. This showed some slowing in inflation but was still far from comfortable reading for the markets or the Fed. Even so, it helped mark a change as long-term yields started to pull back. While this may help stocks in the near-term, the catalyst is hardly encouraging; yields are starting to price in a recession. The 3m 10y spread dropped sharply from 2.26% on May 6 to 1.88% this week. With the Fed set to hike 50bps next month and July, the spread could invert next quarter, in which case a recession is almost guaranteed.
Last week’s market price action was noteworthy for several reasons. Firstly, it showed a change in character. There was no Monday/Tuesday bottom and weak Thursday/Friday as previous weeks. In fact, it was almost the opposite with a solid Friday close which cemented weekly reversal patterns. These reversals came from some significant areas.


WEEKLY PRICE MOVEMENT

The biggest index mover was DAX, back up after three red weeks. The top forex mover was GBPAUD down 2.05%. Bitcoin and Ethereum fell hard, and once again, some FANGs underperformed. AAPL finally fell victim with the other FANGs whereas NFLX made a small recovery.

Last week's GBPAUD long made 1.33%, which means I am ahead 8.08% this year, with 10/16 (62.5%) wins. This week I think EURUSD is well oversold so I am buying it.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.


NEXT WEEK

There is no important US news this week, other that perhaps Retail Sales, so the main markets are likely to show the large two-way volatility often seen when VIX is over 30. Even outside the US, the influence are more on currencies. The all-important inflation reports from Canada and the UK are the main macro releases, with Retail Sales also reported from China and the UK, the former estimating further contraction.


CALENDAR  (all times are GMT, volatile items in bold)

Monday May 16
02:00 China Retail Sales (e-6% p-3.5%)
09:00 EC Economic Growth Forecasts

Tuesday May 17
01:30 RBA Meeting Minutes
06:00 UK Unemployment (e3.6% p3.8%)
09:00 Eurozone Q1 Prelim GDP (YoY e5% p5%)
12:30 US Retail Sales (MoM e0.6% p0.5%)
23:50 Japan Q1 GDP (QoQ e-0.3% p1.1%)

Wednesday May 18
00:30 Aus Wage Price Index
04:30 Japan Industrial Production
06:00 UK CPI (p7%)
09:00 Eurozone CPI
12:30 US Building Permits/Housing Starts
14:30 Canada BoC CPI (Core YoY e5.5% p5.5%)
23:50 Japan Imports/Exports/TB

Thursday May 19
01:30 Aus Jobs/UnEmp (UnEmp e4.1% p4.0%)
11:30 ECB MPC Minutes
12:30 US Jobless Claims
12:30 Philly Fed Mfr Survey
23:30 Japan National CPI

Friday May 20
01:30 PBoC Interest Rate Decision (p3.7%)
06:00 UK Retail Sales
06:00 UK PPI
07:30 BoE Pill speech
14:00 Eurozone Consumer Confidence

Sunday, 24 April 2022

Week to Apr 22nd

Markets hit by Fed comments. 50bp hike looms.
MY CALL THIS WEEK : SELL EURUSD


LAST WEEK

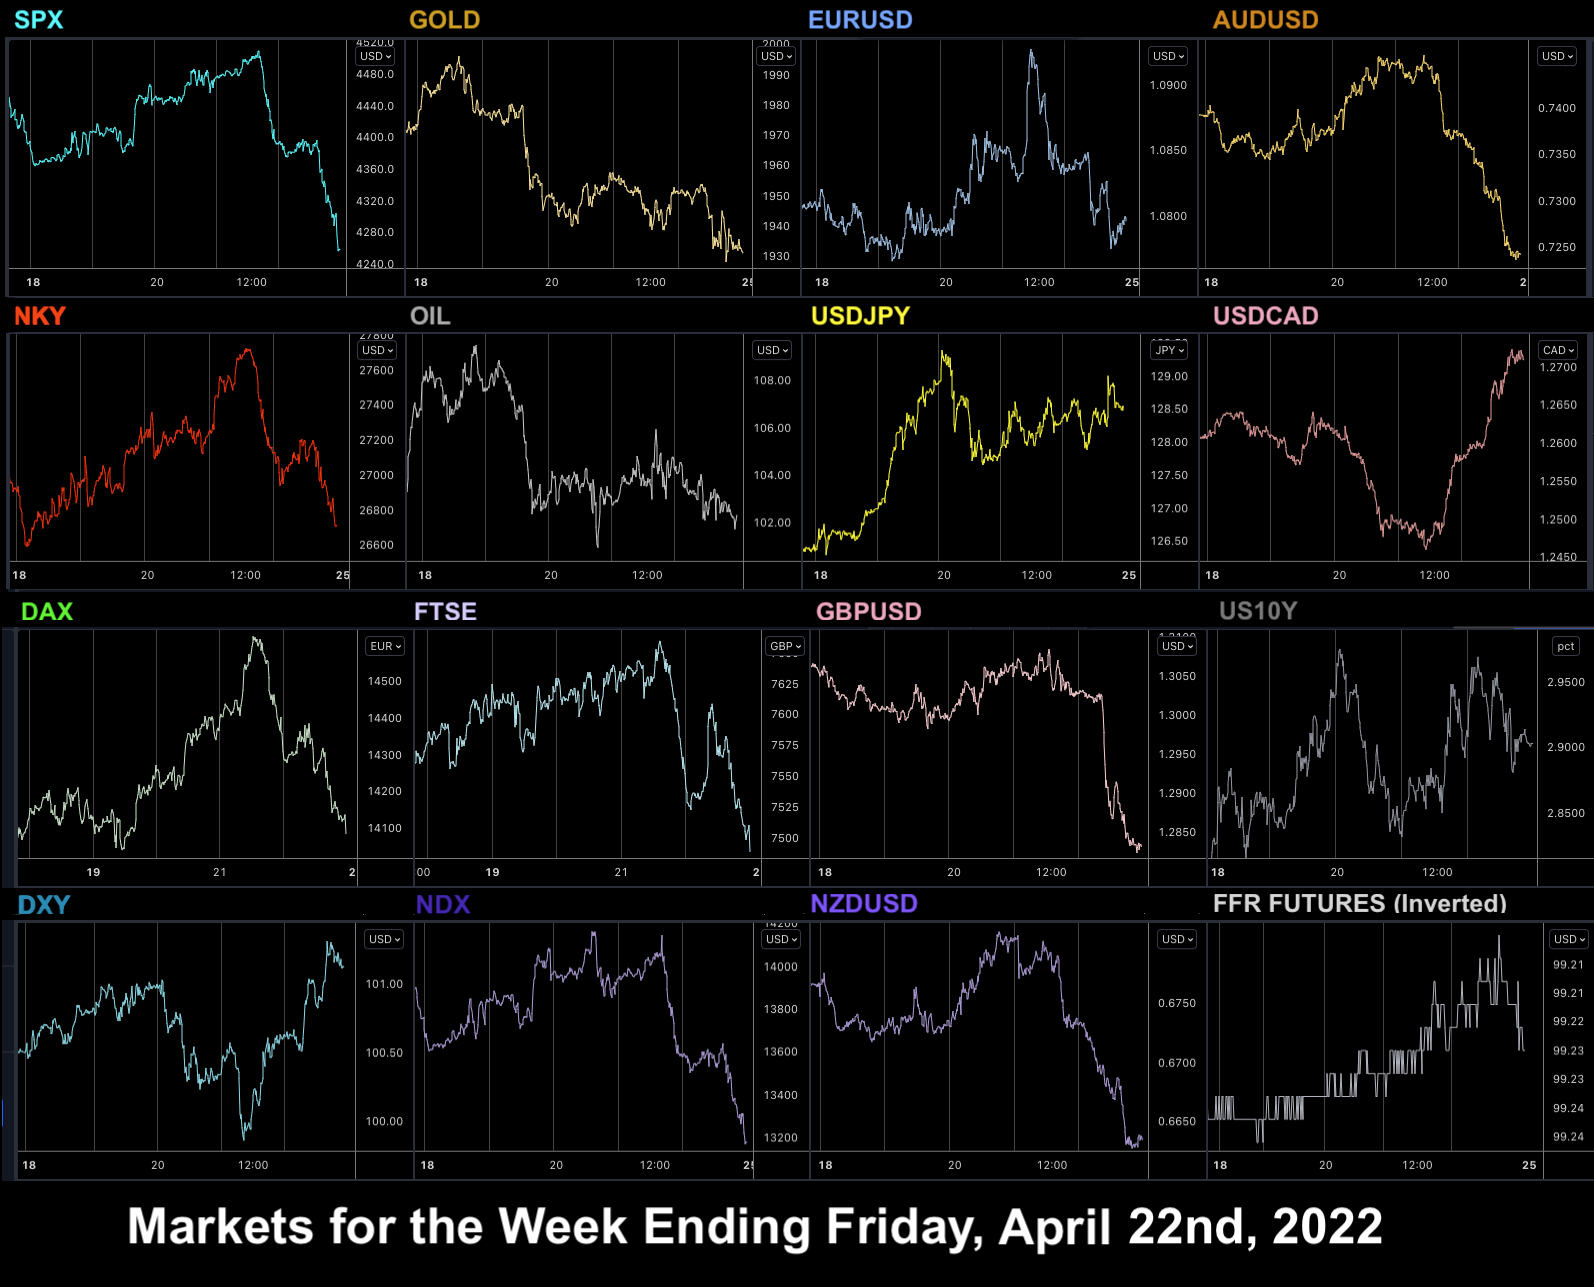
Stock markets managed a few strong sessions but faded following more hawkish Fed signals indicating the May rate hike would be 50bp not 25bp. DAX and NKY were relatively unscathed, but US markets dropped to new April lows by the end of the week and the weak close presents a similar situation to last week—continuation is likely on Monday and Tuesday.


WEEKLY PRICE MOVEMENT


The biggest index mover was rate-sensitive NDX which was down 3.98%, over 7% in two weeks. Clearly rates are still the issue, as other indices moved much less. The top forex mover was EURNZD up 2.19%. Bitcoin and Ethereum pulled back again, and FANGs severely underperformed, after NFLX reported the first reduction in subscribers for a decade. Only AAPL was relatively unscathed.


Last week's EURAUD long position gained 2.17%, which means I am ahead 6.13% this year, with 8/15 (53%) wins. This week I am selling EURUSD.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.


NEXT WEEK


Next week is the big week for earnings, in particular for NDX, with over 42% by weight of the index (including AAPL MSFT GOOGL INTC FB) reporting. These companies are also 22% of SPX. NDX has been severely hit by the rate hike narrative, and entered bear market territory last week. Focus will be in all cases on unit metrics rather than just earnings and revenue. News from the US is again light, with only Durable Goods and GDP of note. Inflation is reported from Australia, Eurozone and Germany, and again estimates show it is still increasing.


CALENDAR  (all times are GMT, volatile items in bold)


Monday April 25

08:00 Germany IFO Sentiment

15:00 BoC Governor Macklem speech

15:00 BoC Rogers speech


Tuesday April 26

12:30 US Durable/ND Capital Goods (DG e1.0% p-2.1%)

12:55 BoC Lane speech

13:00 US Housing/Home Price Indices

14:00 US Consumer Confidence

14:00 US New Home Sales


Wednesday April 27

01:30 Australia CPI (RBA Mean e1.2% p1.0%)

14:00 US Pending Home Sales

23:50 Japan Retail Sales


Thursday April 28

03:00 BoJ Rate Decision/Statement (e-0.1% hold)

06:00 BoJ Press Conference

09:00 Eurozone Consumer Confidence

12:00 Germany CPI (e7.6% p7.6%)

12:30 US Q1 GDP (e1.0% p6.9%)

12:30 US Jobless Claims

12:30 US PCE QoQ


Friday April 29

01:45 China Caixin Mfr PMI

06:00 Germany Q1 GDP (QoQ e0.2% p-0.3%)

09:00 Eurozone GDP (YoY e5.1% p4.6%)

09:00 Eurozone CPI (Core e3.1% p2.9%)

12:30 US PCE MoM & YoY

12:30 Canada GDP

13:45 Chicago PMI

14:00 Michigan CSI

Friday, 1 January 2021

Week to Jan 1st

Final week of 2020, Core ‘Santa Rally’, New all-time highs, 30m USD low.
MY CALL THIS WEEK : BUY EURUSD

An orderly vaccine rollout, the Brexit deal, the passing of the next stimulus package and the general seasonal ‘Santa Rally’ sentiment sent indices to new all-time highs, and the safe haven dollar to a new 30-month low. Gold, Oil and bonds were not in focus, and had inside weeks.


Next week is the new calendar and US fiscal year and a full week. We have a clean sheet as the main issues of late 2020 appear to have been resolved. The Georgia run-off elections are the highlight of the week, followed of course by NFP.


Monday December 28

The Santa Rally was in full risk-on swing today with US indices up and NDX outperforming. Markets were closed in Europe. Without London volume, the dollar was flat overall as EUR rising compensated the GBP drop. Gold was down, for once, in line with equities, but unusually Oil was down as well. Bonds were flat on the day.


Tuesday December 29

The Santa Rally continued, and indices hit new all-time highs today, and then pulled back slightly today, although NDX managed to remain flat. Oil was up in line. The safe haven dollar continued its downward path, with all currencies and Gold rising, and the yen up less than the others confirming risk-on. Bonds were flat again day.


Wednesday December 30

US indices rose again today but with less vigor, and surprisingly there was a slight rotation out of NDX which only managed to stay flat. Oil rose in line. The British Parliament formally agreed the Brexit ‘deal’. This was expected, but nevertheless, gave a boost to EUR and GBP which in turn depressed DAX and FTSE into the red. The dollar was down across the board, leading to Gold rising. Bonds were very slightly up, with a 1.5bp drop in yields.


Thursday December 31 *

After early sliding, there was a strong year-end equity rally in the last 20m of the US session, with NDX slightly outperforming, to close the day, month and year up. Clearly an institutional window dressing move, seen also in DAX futures (Europe had closed) but not FTSE or NKY. After rising all week, EUR came off sharply probably more to do with year-end positioning than Brexit. No other currency showed this move, and it resulted in a closing rally in DXY also. After collapsing in the Asian session, Gold was notably up, as was Oil. Bonds yields dropped another 1.5bp.


Friday January 1

All markets globally were closed today for New Year’s Day, however OTC forex showed a slight recovery in EUR in very thin trading. Otherwise the mood was flat. Bitcoin closed the wee another 22.3% up at an all-time high of $27,444, and was the best performing asset of 2020.


WEEKLY PRICE MOVEMENT

Indices were up this short week of the Santa Rally, with NKY outperforming, up 2.91% The strongest currency move was EURAUD down 1.55%. Cryptos soared, with BTC posting a new all-time high. FANGs did well, outperforming NDX as whole.


Selling EURCAD this week netted me 1.14%, a running total of 9.81% with 25/42 (59.5%) wins for 2020. We will reset for 2021, and in the New Year, I might branch out from just currencies, and I will start the profit count again. This week I’ll buy the dip and go long EURUSD.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.


NEXT WEEK (all times are GMT)

(Calendar High volatility items are in bold)


  • New calendar and fiscal year
  • New Congress
  • Georgia run-offs
  • Non-Farm Payrolls


Monday January 4

The first trading day of 2021 may well see heightened volatility as fund reposition again for the new quarter and year. News is exclusively manufacturing PMIs, all comfortably above 50. The 117th US Congress opened on Sunday. We have an agreed stimulus package, Brexit is behind us, so the year starts with a clean sweep so to speak.


01:45 China Caixin Mfr PMI

08:55 Germany Markit Mfr PMI

09:30 UK Markit Mfr PMI

10:00 OPEC Meeting

14:30 Canada Markit Mfr PMI

14:45 US Markit Mfr PMI


Tuesday January 5

The ISM print is the most important news today, but all eyes will be on today’s Georgia run-off elections.


07:00 Germany Retail Sales (YoY e3.9% p8.2%)

08:55 Germany Unemployment Rate/Change

15:00 US ISM Mfr PMI (e56.5 p57.5)

20:45 Fed Williams speech

22:00 Aus Commonwealth Bank Svcs PMI


Wednesday January 6

The big news today will be the result of the Georgia run-off elections, which in turn determine the color of the Senate for the next two years. Dems need to win both seats to prevail, which is very unlikely. Otherwise the FOMC Minutes will be watched closely.


01:45 China Caixin Svcs PMI(Dec)

08:55 Germany Markit Comp PMI

09:00 Eurozone Markit Comp PMI

10:00 DE10Y Bond Auction (time approx.)

13:00 Germany CPI (YoY Prelim e-0.6% p-0.7%)

13:15 US ADP Jobs (e159k p307k)

14:45 US Markit Svcs/Comp PMI

15:00 US Factory Orders (MoM)(Nov)

19:00 FOMC Minutes


Thursday January 7

Attention turns to Europe today, with inflation and retail sales prints at 1000.


00:30 Aus Imports/Exports/TB

07:00 Germany Factory Orders

10:00 Eurozone CPI (YoY Dec e-0.2% p-0.3%, Core e0.2% unch)
10:00 Eurozone Retail Sales (YoY Nov e1.2% p4.3%)

13:30 US Trade Balance

13:30 US Jobless Claims

15:00 US ISM Svcs PMI (Dec e 54.5 p55.9)

15:00 Canada Ivey PMI

23:30 Japan Overall Household Spending


Friday January 8

The first week ends, as always with NFP. The estimates are very modest. Canada publishes simultaneously assuring volatility in USDCAD.


07:00 Germany TB/Ind.Production

10:00 Eurozone Unemployment

13:30 US NFP/AHE/UnEmp (NFP e100k p245k)

13:30 Canada NFP/AHE/UnEmp (NFP e-5k p62k)

Sunday, 10 March 2019

Week to Mar 7th


Growth forecast cuts in China, Europe and Canada, Worst US TB since 2008

Mon Mar 04
Despite encouraging remarks from President Trump at the weekend, and another call for a weaker dollar, a rally in China during the Asian session did not prevent optimism from fading in the US markets and SPX close down 0.4%. DAX and NKY followed suit although FTSE advanced as GBP faded some its Brexit hopes gains. Yields fells on stock-bond rotation.
President Trump also called for a weaker dollar again, but this had no effect, with all currencies except JPY declining slightly, in line with the equity softening. Gold fell in line, although Oil managed to move up after Friday’s sharp fall.

Tuesday March 05
Mixed US data left equities directionless today. The situation was better in Europe after UK, German and Eurozone PMI beats at 0855, and DAX and FTSE were both up slightly. The dollar benefited from continuing EUR weakness ahead of the ECB meeting, with DXY advancing 0.24%, and CAD and JPY also fell slightly, and GBP was flat, as was Gold. Oil was choppy but ended slightly up, whereas yields fell for a second day. AUD hardly moved after the rate hold.

Wednesday March 06
Markets faltered again today on the US trade balance miss at 1330, the worst deficit since 2008, together with the ADP miss at the same time, and all indices were down, even FTSE. Yields were down 3.2bp, and JPY was up in line with the risk off mood. DXY was flat (as was Gold), with small recoveries (after two days decline) in EUR and GBP balancing a sharp drop in CAD (only 9.1% of the basket) after gloomy growth forecasts from the BoC at 1500 and mixed Ivey PMIs at the same time. AUD dropped sharply by nearly 1% on the Australian Q4 GDP miss. Oil ended slightly up, with the usual choppiness around the EIA print at 1530. The headline missed, but the Gasoline estimate beat.

Thursday March 07
Another day, another problem. Following the record US trade deficit and the BoC forecast, today the ECB downgraded growth forecasts for the giant Eurozone, and more significantly reversed policy from tightening (the end of bond buying in December) back to easing by a new TLTRO program. The forecast was expected, the TLTROs were not, and EUR fell 1.27% during the next six hours. US, Japanese (futures), and UK equities accelerated their fall. DAX had a short currency related spike up and then joined them.

DXY had its best day since June 2018, and rose 0.75%. As you would expect EURJPY moved even more (down 1.18%). Other currencies moved down, although notably, CAD did not suffer from its usual risk aversion, having softened the day before. Gold was flat. Oil was up slightly again, staying in the 56.50-57.50 range it has held all week. Yield were down again, following the rotation principle rather than the stronger dollar. This is showing that the dollar was not really stronger, it is just EUR that is weaker, as evidenced by the move down in USDJPY.

Friday March 08
The February NFP miss (20k vs 180k) at 1330 gave us three bad days in a row. Small misses sometime push equities up on the theory that they will delay rate hikes, but this was the third-worst print since 2011, following a stellar (311k) January. No tweet from Trump today! Markets all slid down further, although there was a small rally in the last hour. Notably China fell 4% in Asia well before the NFP release.

DXY was down 0.26%, giving back a third of its Thursday gains, with all currencies up, in particular big moves up in JPY and Gold, and down in Oil in line with the equity fade, although the latter recovered somewhat into the close. The Canadian NFP beat had a surprisingly modest effect, with USDCAD only down 0.28%, no more than DXY as a whole. Yields were down 5bp on rotation or dollar tracking.


WEEKLY PRICE MOVEMENT
Despite the stronger yen, NKY was the biggest index decline this week. The strong yen also made shorting GBPJPY (down 2.35%) the best forex trade of the week. Cryptos went to sleep again after a brief burst of activity last week. Another mixed week for FANGs with a surprisingly strong performance from FB.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on UUP. The equity and index prices are now based on the cash close each day.


NEXT WEEK 
(all times are GMT)
(Calendar High volatility items are in bold)
  • Yet another Brexit ‘high noon’
  • BoJ Rate Decision
  • US Inflation release
  • US/Europe DST disconnect

Monday March 11
Today is the first day of the bi-annual one-hour disconnect between the start of daylight saving (summer) time in North America and Europe. The first effect is the Retail Sales print, an hour earlier for European traders, coming after the worst figure since 2001 last month. Our times remain on GMT, as they will when Europe enters DST.


21:45 NZD NZ Electronic Card Retail Sales (Sunday)
00:00 EUR Eurogroup meeting (all day)
07:00 EUR Germany Industrial Production/Trade Balance
12:30 USD US Retail Sales Jan (Control Group est 0.6% prev -1.7%)
13:00 GBP BoE Haskel speech

Tuesday March 12
Today, we have another attempt by embattled UK PM Theresa May to get her Brexit deal through the British Parliament. The vote seems likely to fail again, at which point the saga moves to later votes in the week. US inflation (one leg of the Fed’s dual mandate) will inevitiably affect USD if it is well off estimates. Fed Chair Powell is due to speak at some time today (unconfirmed).

00:00 EUR EcoFin Meeting (all day)
02:15 CNY China FDI
06:30 AUD RBA Debelle speech
09:30 GBP UK Industrial/Manufacturing Production
09:30 GBP UK GDP MoM
12:30 USD US CPI (Core YoY est 2.1% prev 2.2%)
13:45 USD Fed Brainard speech
19:00 GBP UK Parliamentary vote on Brexit (time approx)
20:30 WTI API Oil Stock

Wednesday March 13
Provided the Tuesday vote fails (as expected), a (free) vote by UK MPs is expected to on whether it is acceptable to exit on Mar 29 without a deal. This is designed to be rejected, and almost certainly will be.  In the middle of this, the UK Spring Statement (Budget) is announced, with possible tax changes. A new US report, the unwieldy-titled Nondefense Capital Goods Orders ex Aircraft has been marked by commentators as important, more so that the normal Durable Goods release at the same time.

10:00 EUR Eurozone Industrial Production s.a. (MoM)
12:30 USD US Core PPI
12:30 USD US Durable Goods
12:30 USD US ND Capital Goods (est 0.1% prev -1%)
12:30 GBP UK Budget Report (time approx)
14:30 WTI EIA Oil Stock

Thursday March 14
If the two previous votes are rejected, today’s British Parliament vote is crucial. This will be to extend the exit date (probably to May 23). There may be amendments for a longer delay, or even a second referendum (polls suggest a new people’s vote would cancel Brexit). This is the least certain and therefore potentially the most volatile for GBP. China’s Industrial Production figures are important, given reactions to recent Chinese data. There is a rate decision on UAH (0.5% cut expected)

00:00 AUD Aus Consumer Inflation Expectations
02:00 CNY China Retail Sales/Industrial Production (YoY)
07:00 EUR Germany CPI (est 1.% prev 1.7%)
12:30 USD US Jobless Claims
14:00 USD US New Home Sales (MoM)
21:30 NZD Business NZ PMI
22:50 CAD BoC Wilkins speech

Friday March 15
After growth downgrades elsewhere last week, traders will be listening carefully for any similar views from the BoJ, so for once, this normally unimportant rate decision and statement may cause some JPY volatility. The Michigan Sentiment Index is estimated to fall further. The miss two weeks ago caused a sharp fall in SPX, and another could do the same.

02:00 JPY BoJ Rate Decision/Statement (est -0.1% hold)
10:00 EUR Eurozone CPI
13:15 USD US Industrial Production (MoM)
14:00 USD Michigan Consumer Sentiment Index (est 93.0 prev 93.8)
18:00 WTI Baker Hughes Rig Count


This report is published every week as an email by MatrixTrade.com - you can sign up to receive it here. This blog is supported solely by advertising, so if any of them interest you, please click the links. If you want notification when the blog is updated, please follow me on TwitterFacebookStocktwits or Linkedin (all open in separate windows). Details of how I compile the report are here


Sunday, 3 March 2019

Week to Mar 1st


Brexit softening of position helps GBP, Tariff delay confirmed, Trump/Kim summit fails

Mon Feb 25
President Trump announced today that as there had been “substantial progress” in the US/China trade talks, he would be postponing the 15% increase in tariffs on $200Bn of Chinese imports. Although Chinese markets soared over 6%, the results were only modest in the US, Japan and Europe, which registered slight gains. DAX even retreated after the cash close. DXY had a flat day (as did Gold), with modest moves up in EUR, AUD and GBP being balanced by slight softening of CAD and JPY. Yields 

We have highlighted before the effect of President Trump’s tweets on his two favorite market subjects, the value of the dollar and the price of oil. Today he tweeted again that oil was too high, and  called on OPEC to “relax” Brent crude. The prices of both BNO and WTI quick dropped 3.2%.

Tuesday February 26
The big story of the day was UK PM May giving ground on Brexit, saying that if a vote for a deal could not be reached in time for the Mar 29 deadline, she would seek an extension. Sterling added over 1% on the news, which inevitably caused FTSE to fall (71% of the revenue of FTSE companies is from outside the UK). NKY moved down sharply in the cash session but recovered in futures to end the day flat, as did a volatile SPX. DAX continued to move independently and ended up.

The miss on US Housing Starts and Home Prices led to a weaker dollar, with DXY down 0.39%. Although not as strong as GBP, all currencies and Gold were up. Oil recovered 1% after the tweet crash. Yields were down in line with the weaker dollar. The Powell Humphrey-Hawkins testimony (summary: ‘patient’) did not add anything to what we already know.

Wednesday February 27
Another down day in equities as USTR Lighthizer testified to the House that a China trade deal was not yet certain, and would be a “long process”. Although not directly market-related, it didn’t help that Pakistan shot down two Indian military jets in Kashmir. Also the US Trade Balance (1330), Capital Goods, and Factory Orders (both 1500) reports were all down on the previous figure. World markets followed suit, although NKY managed to close flat in futures helped by the weaker yen.

The Brexit softening by PM May was accompanied by softening from both the hardline (want out, don’t care about a deal) ERG group in her party, and also the opposition Labour Party. Sterling continues to rise to its highest level in nearly eight months. Further oil recovery on the strong EIA beat at 1530 helped CAD, which despite a miss on annualised CPI, improved core monthly to 0.3% from -0.2% previously. Other currencies and Gold fell, resulting in a flat dollar basket. Yields were unusually up 4bp today, following USDJPY on part two of the Powell testimony.

Thursday February 28
Another down day after the failure of the Trump/Kim summit, where no progress was achieved. Also the long-awaited US Q4 GDP print at 1330, which beat estimates (YoY 2.6% vs 2.3% est, but was still well down on Q3 (3.4%). US Jobless Claims also missed. The markets are also working off an overbought condition after the strong 10-week bull run. Only DAX managed to post a small gain. The GDP print gave DXY a small boost (up 0.11%) with all currencies (even GBP) and Gold softening. Yields were up again. Oil continued its post Trump tweet recovery.

Friday March 01
Markets recovered again today, buoyed initially by the Chinese Manufacturing PMI beat at 0145, and German (0855) and Eurozone (1000) unemployment beats. The mood continued into the US Open, but was sharply halted by the double whammy of misses on the Michigan Consumer Sentiment (93.8 vs 95.7) and ISM Manufacturing PMI/Prices Paid at 1500. SPX dropped 0.73% in the two hours after the print. However, it then went on to fully recover into the close.

The GDP feelgood factor continued today with DXY up 0.22%, and all currencies and Gold down. However over half of the move was a plummet by CAD after the severe Q4 YoY GDP miss (0.4% vs 1.2%). The loonie is 9.1% of DXY, and fell 1.32% after the print, meaning if it had gone the other way, DXY would have been flat. The CAD move was accentuated by a 2.5% drop in Oil, fuelling by the ISM PMI miss.

WEEKLY PRICE MOVEMENT
A strong recovery from DAX this week, as it beat US indices and was the best performer. For the first time this year, we have a strong divergence in forex, with GBPCAD easily the biggest mover, up 2.26%. Last week’s crypto rally was short-lived, with BTC and ETH down again. A mixed week for FANGs, which were more volatile than the underlying NDX.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on UUP. The equity and index prices are now based on the cash close each day.

  • Rate decisions in EUR, CAD and AUD
  • Non-farm payrolls in US and Canada
  • Australian and Eurozone Q4 GDP
  • China’s main political conference

NEXT WEEK (all times are GMT)
(Calendar High volatility items are in bold)

Monday March 04
A quiet start to a busy week, with limited scheduled news, so as usual, the trade war and Brexit will dominate. Brazil and Argentina are closed for two days for Carnival. India is also closed for Mahasivarathri Day.

00:30 AUD Aus Building Permits (MoM)
09:30 GBP UK Markit Construction PM

Tuesday March 05
The 13th National People’s Congress in China is expected to produce economic growth targets going forward, and review intellectual property and technology transfers, key areas in the trade dispute. The key scheduled event is the RBA rate decision. Fed Rosengren (hawk, 2019 voter) speaks at 1230, followed two hours later by Kashkari (dove, 2020 voter). Barkin (hawk, non-voter) is also on. Brazil and Argentina remain closed.

01:45 CNY China Caixin Services PMI
03:30 AUD RBA Rate Decision/Statement
07:00 EUR Germany Retail Sales (MoM)
09:00 EUR Eurozone Markit PMI Composite
09:30 GBP UK Markit Services PMI
10:00 EUR Eurozone Retail Sales (YoY)
14:00 NZD NZ GDT Milk Index
14:45 USD US Markit Services/Composite PMI
15:00 USD US ISM Non-Manufacturing PMI
15:00 USD US New Home Sales (MoM)
19:00 USD US Monthly Budget Statement
21:30 WTI API Oil Stock
23:01 GBP UK BRC Like-For-Like Retail Sales (YoY)

Wednesday March 06
The Canadian rate decision is expected to be a hold, but watch out for Gov Poloz remarks. It’s Australia’s turn to report Q4 GDP, which we have seen has moved markets in other countries. The ADP ‘sneak preview’ jobs estimate is 190k, 10k more than the NFP estimate for Friday. Fed Williams (hawkish, 2019 voter) and Mester (hawk, 2019 voter) both speak at 1700. There are also rate decisions on TRY and PLN. Brazil and Argentina reopen.

00:00 CNY China PPI
00:30 AUD Aus GDP Q4
12:15 GBP BoE Cunliffe speech
13:15 USD US ADP Employment Change
13:30 USD US Trade Balance
15:00 USD US Factory Orders (MoM)
15:00 USD US New Home Sales (MoM)
15:00 CAD BoC Rate Decision/Statement
15:00 CAD Canada Ivey PMI
15:30 WTI EIA Oil Stock
19:00 USD Fed Beige Book
21:30 AUD Aus AiG Performance of Construction Index

Thursday March 07
Another day, another rate decision, this time the key Eurozone figure. A hold is virtually certain, but as always it’s the report and press conference 45 minutes later which will be examined. The third day of Fed speeches as well, this time Brainard (was dovish, now centrist, 2019 and 2020 voter) is on at 1715. BoE Tenreyro speaks at 0930.

00:30 AUD Aus Retail Sales s.a. (MoM)
00:30 AUD Aus Imports/Exports/Trade Balance
05:00 JPY Japan Leading Economic Index
09:30 GBP BoE's Tenreyro speech
10:00 EUR Eurozone GDP Q4
12:30 USD US Jobless Claims
12:45 EUR ECB Rate Decision/Statement
13:30 USD US Trade Balance
13:30 USD US Nonfarm Productivity/Unit Labor Costs
13:30 EUR ECB Draghi Presser
13:30 CAD Canada International Merchandise Trade
23:30 JPY Japan Overall Household Spending (YoY)

Friday March 08
Simultaneous US and Canadian NFPs offer strong volatility for USDCAD today. As usual, the AHE figure may be more important than the jobs print itself. This is the final day before the US/Europe summer time disconnect. For the next three weeks, for Europeans, US markets will appear to open an hour earlier (1330 GMT), and for Americans, Europe will appear to run an hour later, closing at 1230 EDT. ECB Mersch (hawkish) speaks at 1630. Fed Chair Powell may also speak.

02:00 CNY China Imports/Exports/TB
09:30 GBP Industrial Production (MoM)
13:30 USD US NFP/AHE/UE/Participation/Productivity
13:30 CAD Canada NFP/UE/AHE/Participation
18:00 WTI Baker Hughes Rig Count


This report is published every week as an email by MatrixTrade.com - you can sign up to receive it here. This blog is supported solely by advertising, so if any of them interest you, please click the links. If you want notification when the blog is updated, please follow me on TwitterFacebookStocktwits or Linkedin (all open in separate windows). Details of how I compile the report are here