Showing posts with label CL_F. Show all posts

Sunday, 26 April 2020

Week to Apr 24th


Oil collapses, negative futures, Inside week, GILD COVID drug trial fails
MY CALL FOR THIS WEEK : SELL NZDJPY

In a week dominated, for once, by the collapse of the oil market, and the first time ever that a contract traded at a negative price in the hours prior to expiration, the earnings picture, although mixed overall, was far from disastrous, and as oil recovered, so did equities, and started to form a shallow V-shaped inside week. This was halted mid-session on Thursday with a report that, contrary to expectations, the GILD drug remdesivir had not been successful in COVID-19 trials.

Haven assets also lost volatility, especially USDJPY which was virtually flat, although the ECB move (following the Fed) to buy lower-rated bonds caused a clear move out of EUR, resulting in an second week of uptick in DXY.

Next week sees the scheduled Fed rate decision, but with a rare 100% hold priced in, and of course the recent tendency of the Fed to abandon scheduled decisions, it is probably the least important meeting for years. US preliminary QoQ GDP (-4%) and ISM PMI (36.7) are sure to be dire, and the new jobless claims estimate at ‘only’ 3.5m (previous 4.4m) is the only reversal expected. The most important week of earnings season has over 660 companies reporting. It delivers the rest of the FAANGs and MSFT, and Dow giants BA, V, MCD and CVX. Plenty of results and guidance to possibly resolve the apparent disconnect between price recovery and the continuing pessimistic clinical outlook on the COVID-19 crisis.

SPX was fairly flat and posted an inside week last week and it is interesting that actual earnings did not move the variance from pre-COVID prices very much. The final columns effectively chart the movement in P/E ratio, generally down, but for example AXP now seems overpriced.


Mon Apr 20
The big news today was something that has never happened before in all history, the May contract for WTI crude (which expired the next day) actually went negative, closing at minus $37.63 a barrel. The press buzzed with explanations of what this meant. Oil stocks plunged, but outside that sector, things were fairly calm, and indices were around 2% down, depending on their Oil exposure, for example oil-free DAX was up 0.47%. FTSE was up but by less than amount GBP was down. CAD, an oil proxy was sharply down but with a flat Euro, DXY only advanced a modest 0.33%  Gold and bonds were in demand and advanced.


Tuesday April 21
Another down day as pressure moved onto the June oil contract, which fell over 70% to a low of $6.50, triggering circuit breakers, before recovering slightly into the close. Trading in the USO ETF was halted after its worst day in history. Monday night’s poor results from IBM, with profits down 61% also cast a pall, and indices fell 3-4%, this time with NDX and DAX faring worst. In currencies, money move out of commodity currencies, although as EUR and JPY hardly moved, the DXY gain was again muted. Bonds advanced again, although Gold gave back Monday’s gains, showing once again that it is an unreliable haven.


Wednesday April 22
Strong results from lockdown immune NFLX and SNAP the night before, and more significantly a huge 19% recovery in the June contract price (which does not show in USO in our table) halted the slide, and markets were up across the board. After an early pullback, USD advanced again, mainly because EUR capitulated after two flat days. Bonds were down in line with the recovery, but once again, Gold followed the equity markets rather the inverse.


Thursday April 23

The V-shaped week for equities was doing fine until a report on the GILD drug remdesivir did not actually help with COVID-19 after all. SPX quickly dropped by 80 handles, and closed Thursday less than two points apart from the previous Thursday’s close before the GILD bump up, giving a flat day overall.  It was a similar situation with the dollar, which had also been rising rapidly and also felt the same dip, and only a similar dip in EUR kept DXY flat. Oil continued to rally and this was reflected in CAD. Bonds were flat, and Gold was once again up.


Friday April 24
The last day of the week started badly in futures, but then quickly accelerated as oil stopped falling. Tech shares outperformed with NDX up 1.68% against 1.11% for DJIA. This still led to a red week overall in all indices.  The dollar was generally down with only CAD underperforming. Bonds were again flat, and Gold was down in line with equities.


WEEKLY PRICE MOVEMENT
The weakest indices were NKY, then DAX but this mainly reflected their inability due to timing, to participate in Friday’s rally. GBPAUD was the weakest currency down 1.42%. Cryptos started to show a little bit more volatility, whereas FANGS were lacklustre with the exception of FB, up over 6%.

My call to sell EURCAD failed. I had not expected Oil to crash for a second week, and I was still doing well until Friday. The pair was down 0.21%, so twelve weeks, five wins and a running total of 3.52%. This week I am selling NZDJPY.
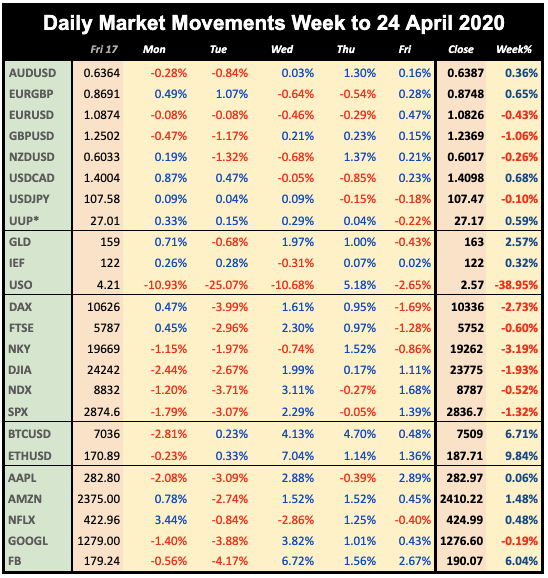


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day. Recoveries in line were seen in most FANGs, but not NFLX, which has not really fallen like the others.


NEXT WEEK (all times are GMT)
(Calendar High volatility items are in bold)


  • Most important earnings week
  • Rate decisions in US, EU and Japan
  • Lockdown end discussed
  • Post-COVID GDP and CPI reports


For the third week, we offer a table of major earnings estimates against current prices. As you can see, unlike Week 1, quite a few companies have now recovered more than their earnings suggest.


Monday April 27
Entering the final week of the month, with no sign of new COVID case reduction in the US, markets will be looking for economic lockdown mitigation strategy. Watch out all week for another oil collapse. DAX giant Bayer reports today. Markets are closed in South Africa.

14:30 USD Dallas Fed Manuf Business Index (Apr)
23:30 JPY Japan Jobs Applicants Ratio/Unemployment Rate(Mar)


Tuesday April 28
We have not heard much from Japan in relation to the COVID crisis, and so today’s BoJ scheduled decision provides a opportunity to possibly hear something different. However, earnings will dominate today, with CAT, MMM and MRK (together 9.88% of DJIA) before the bell, followed by NDX giant GOOGL, along with AMD after the bell. There are rate decisions in Hungary and Sweden. SEK is 4.2% of the DXY basket.

03:00 JPY BoJ Rate Decision/Statement (e0.1% hold)
06:00 JPY BoJ Press Conference
08:00 EUR ECB Bank Lending Survey
13:00 USD US S&P/Case-Shiller Home Price Indices
14:00 USD US Consumer Confidence
22:45 NZD NZ Imports/Exports/TB


Wednesday April 29
The Fed decision today, where for the first time in years, a hold is 100% priced in, will probably be of little interest, especially given that central banks have more of less abandoned keeping news to scheduled dates during this crisis. So it will be an earnings day with troubled aviation giant BA before the bell, once top of the table it now languished at 11th position. After the bell, top NDX stock (11.71% alone of the index) MSFT reports, along with FB, TSLA, QCOM, and a host of smaller companies (EBAY. ALGN, VRTX, BMRN, ADP, QCOM) to make a total of 20.46% of NDX by weight. Markets are today in Japan.

01:30 AUD Australia CPI (RBA Mean QoQ e0.4% p0.4%)
09:00 EUR Eurozone Business Climate
12:00 EUR Germany CPI (YoY e0.6% p1.3%)
12:30 USD US 20Q1 Prelim GDP (e-4.0% p2.1%)
14:00 USD Pending Home Sales
14:30 USD EIA Crude Oil Stocks Change (Apr 24)
18:00 USD Fed Rate Decision/Statement (e0.25% hold)
18:30 USD FOMC Press Conference
23:50 JPY Japan Industrial Production


Thursday April 30
The early focus on European macro issues, with the ECB statement and presser following a triple Eurozone report (GDP, inflation and unemployment all in one go). The ECB is already set to spend $1trn on asset purchases this year, will that be enough, is the question President Lagarde is sure to face.

Earnings before the bell include two large airlines AAL and UAL, and Dow #4 position MCD (5.31% of the index). But once again, the big news is at the end of the day with AAPL and AMZN both reporting, along with recently newsworthy GILD, and smaller NDX companies (KHC, WDC, ILMN  and SGEN), to make a total of 24% of NDX reporting simultaneously. Markets are closed today in South Korea and Hong Kong.

01:00 CNY China PMIs
06:00 EUR Germany Retail Sales (MoM)(Mar)
07:55 EUR Germany Unemployment Rate/Change (e70k/5.2%, p1k/5.0%)
09:00 EUR Eurozone CPI (Core YoY e0.7% p1.0%)
09:00 EUR Eurozone UnEmp (e7.7% p7.3%)
09:00 EUR Eurozone 20Q1 Prelim GDP (QoQ e-3.3% p0.1%)
11:45 EUR ECB Rate Decision/Statement (e0.0% hold)
12:30 USD US PCE/Personal Income
12:30 USD US Initial Jobless Claims (Apr 24) (e3.5M, p4.4M)
12:30 EUR ECB Lagarde Presser
12:30 CAD Canada GDP MoM
13:45 USD Chicago PMI
23:50 JPY Tokyo CPI (YoY e0.1% p0.4%)


Friday May 1
Markets are closed for Labour Day in China, and most of Europe (including Germany) although not in Japan, the UK or the US. The only significant earnings today are three oil giants XOM, CVX and PSX all reporting before the bell, which may bring Oil back into focus. The all-important ISM PMI is predicted to print the lowest level since 2009, a dip below 35.47 would mean the worst figure since 1980. It is of course also the first day of May, the traditional time when markets sell off for summer. They did so precisely on May 1 last year, it remains to be see whether they will do so again.

08:30 GBP Markit Manuf PMI(Apr)
13:30 CAD Markit Manuf PMI(Apr)
13:45 USD Markit Manuf PMI(Apr)
14:00 USD ISM Manuf PMI (e36.7 p49.1)

Sunday, 10 March 2019

Week to Mar 7th


Growth forecast cuts in China, Europe and Canada, Worst US TB since 2008

Mon Mar 04
Despite encouraging remarks from President Trump at the weekend, and another call for a weaker dollar, a rally in China during the Asian session did not prevent optimism from fading in the US markets and SPX close down 0.4%. DAX and NKY followed suit although FTSE advanced as GBP faded some its Brexit hopes gains. Yields fells on stock-bond rotation.
President Trump also called for a weaker dollar again, but this had no effect, with all currencies except JPY declining slightly, in line with the equity softening. Gold fell in line, although Oil managed to move up after Friday’s sharp fall.

Tuesday March 05
Mixed US data left equities directionless today. The situation was better in Europe after UK, German and Eurozone PMI beats at 0855, and DAX and FTSE were both up slightly. The dollar benefited from continuing EUR weakness ahead of the ECB meeting, with DXY advancing 0.24%, and CAD and JPY also fell slightly, and GBP was flat, as was Gold. Oil was choppy but ended slightly up, whereas yields fell for a second day. AUD hardly moved after the rate hold.

Wednesday March 06
Markets faltered again today on the US trade balance miss at 1330, the worst deficit since 2008, together with the ADP miss at the same time, and all indices were down, even FTSE. Yields were down 3.2bp, and JPY was up in line with the risk off mood. DXY was flat (as was Gold), with small recoveries (after two days decline) in EUR and GBP balancing a sharp drop in CAD (only 9.1% of the basket) after gloomy growth forecasts from the BoC at 1500 and mixed Ivey PMIs at the same time. AUD dropped sharply by nearly 1% on the Australian Q4 GDP miss. Oil ended slightly up, with the usual choppiness around the EIA print at 1530. The headline missed, but the Gasoline estimate beat.

Thursday March 07
Another day, another problem. Following the record US trade deficit and the BoC forecast, today the ECB downgraded growth forecasts for the giant Eurozone, and more significantly reversed policy from tightening (the end of bond buying in December) back to easing by a new TLTRO program. The forecast was expected, the TLTROs were not, and EUR fell 1.27% during the next six hours. US, Japanese (futures), and UK equities accelerated their fall. DAX had a short currency related spike up and then joined them.

DXY had its best day since June 2018, and rose 0.75%. As you would expect EURJPY moved even more (down 1.18%). Other currencies moved down, although notably, CAD did not suffer from its usual risk aversion, having softened the day before. Gold was flat. Oil was up slightly again, staying in the 56.50-57.50 range it has held all week. Yield were down again, following the rotation principle rather than the stronger dollar. This is showing that the dollar was not really stronger, it is just EUR that is weaker, as evidenced by the move down in USDJPY.

Friday March 08
The February NFP miss (20k vs 180k) at 1330 gave us three bad days in a row. Small misses sometime push equities up on the theory that they will delay rate hikes, but this was the third-worst print since 2011, following a stellar (311k) January. No tweet from Trump today! Markets all slid down further, although there was a small rally in the last hour. Notably China fell 4% in Asia well before the NFP release.

DXY was down 0.26%, giving back a third of its Thursday gains, with all currencies up, in particular big moves up in JPY and Gold, and down in Oil in line with the equity fade, although the latter recovered somewhat into the close. The Canadian NFP beat had a surprisingly modest effect, with USDCAD only down 0.28%, no more than DXY as a whole. Yields were down 5bp on rotation or dollar tracking.


WEEKLY PRICE MOVEMENT
Despite the stronger yen, NKY was the biggest index decline this week. The strong yen also made shorting GBPJPY (down 2.35%) the best forex trade of the week. Cryptos went to sleep again after a brief burst of activity last week. Another mixed week for FANGs with a surprisingly strong performance from FB.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on UUP. The equity and index prices are now based on the cash close each day.


NEXT WEEK 
(all times are GMT)
(Calendar High volatility items are in bold)
  • Yet another Brexit ‘high noon’
  • BoJ Rate Decision
  • US Inflation release
  • US/Europe DST disconnect

Monday March 11
Today is the first day of the bi-annual one-hour disconnect between the start of daylight saving (summer) time in North America and Europe. The first effect is the Retail Sales print, an hour earlier for European traders, coming after the worst figure since 2001 last month. Our times remain on GMT, as they will when Europe enters DST.


21:45 NZD NZ Electronic Card Retail Sales (Sunday)
00:00 EUR Eurogroup meeting (all day)
07:00 EUR Germany Industrial Production/Trade Balance
12:30 USD US Retail Sales Jan (Control Group est 0.6% prev -1.7%)
13:00 GBP BoE Haskel speech

Tuesday March 12
Today, we have another attempt by embattled UK PM Theresa May to get her Brexit deal through the British Parliament. The vote seems likely to fail again, at which point the saga moves to later votes in the week. US inflation (one leg of the Fed’s dual mandate) will inevitiably affect USD if it is well off estimates. Fed Chair Powell is due to speak at some time today (unconfirmed).

00:00 EUR EcoFin Meeting (all day)
02:15 CNY China FDI
06:30 AUD RBA Debelle speech
09:30 GBP UK Industrial/Manufacturing Production
09:30 GBP UK GDP MoM
12:30 USD US CPI (Core YoY est 2.1% prev 2.2%)
13:45 USD Fed Brainard speech
19:00 GBP UK Parliamentary vote on Brexit (time approx)
20:30 WTI API Oil Stock

Wednesday March 13
Provided the Tuesday vote fails (as expected), a (free) vote by UK MPs is expected to on whether it is acceptable to exit on Mar 29 without a deal. This is designed to be rejected, and almost certainly will be.  In the middle of this, the UK Spring Statement (Budget) is announced, with possible tax changes. A new US report, the unwieldy-titled Nondefense Capital Goods Orders ex Aircraft has been marked by commentators as important, more so that the normal Durable Goods release at the same time.

10:00 EUR Eurozone Industrial Production s.a. (MoM)
12:30 USD US Core PPI
12:30 USD US Durable Goods
12:30 USD US ND Capital Goods (est 0.1% prev -1%)
12:30 GBP UK Budget Report (time approx)
14:30 WTI EIA Oil Stock

Thursday March 14
If the two previous votes are rejected, today’s British Parliament vote is crucial. This will be to extend the exit date (probably to May 23). There may be amendments for a longer delay, or even a second referendum (polls suggest a new people’s vote would cancel Brexit). This is the least certain and therefore potentially the most volatile for GBP. China’s Industrial Production figures are important, given reactions to recent Chinese data. There is a rate decision on UAH (0.5% cut expected)

00:00 AUD Aus Consumer Inflation Expectations
02:00 CNY China Retail Sales/Industrial Production (YoY)
07:00 EUR Germany CPI (est 1.% prev 1.7%)
12:30 USD US Jobless Claims
14:00 USD US New Home Sales (MoM)
21:30 NZD Business NZ PMI
22:50 CAD BoC Wilkins speech

Friday March 15
After growth downgrades elsewhere last week, traders will be listening carefully for any similar views from the BoJ, so for once, this normally unimportant rate decision and statement may cause some JPY volatility. The Michigan Sentiment Index is estimated to fall further. The miss two weeks ago caused a sharp fall in SPX, and another could do the same.

02:00 JPY BoJ Rate Decision/Statement (est -0.1% hold)
10:00 EUR Eurozone CPI
13:15 USD US Industrial Production (MoM)
14:00 USD Michigan Consumer Sentiment Index (est 93.0 prev 93.8)
18:00 WTI Baker Hughes Rig Count


This report is published every week as an email by MatrixTrade.com - you can sign up to receive it here. This blog is supported solely by advertising, so if any of them interest you, please click the links. If you want notification when the blog is updated, please follow me on Twitter, Facebook, Stocktwits or Linkedin (all open in separate windows). Details of how I compile the report are here


Sunday, 3 March 2019

Week to Mar 1st


Brexit softening of position helps GBP, Tariff delay confirmed, Trump/Kim summit fails

Mon Feb 25
President Trump announced today that as there had been “substantial progress” in the US/China trade talks, he would be postponing the 15% increase in tariffs on $200Bn of Chinese imports. Although Chinese markets soared over 6%, the results were only modest in the US, Japan and Europe, which registered slight gains. DAX even retreated after the cash close. DXY had a flat day (as did Gold), with modest moves up in EUR, AUD and GBP being balanced by slight softening of CAD and JPY. Yields 

We have highlighted before the effect of President Trump’s tweets on his two favorite market subjects, the value of the dollar and the price of oil. Today he tweeted again that oil was too high, and  called on OPEC to “relax” Brent crude. The prices of both BNO and WTI quick dropped 3.2%.

Tuesday February 26
The big story of the day was UK PM May giving ground on Brexit, saying that if a vote for a deal could not be reached in time for the Mar 29 deadline, she would seek an extension. Sterling added over 1% on the news, which inevitably caused FTSE to fall (71% of the revenue of FTSE companies is from outside the UK). NKY moved down sharply in the cash session but recovered in futures to end the day flat, as did a volatile SPX. DAX continued to move independently and ended up.

The miss on US Housing Starts and Home Prices led to a weaker dollar, with DXY down 0.39%. Although not as strong as GBP, all currencies and Gold were up. Oil recovered 1% after the tweet crash. Yields were down in line with the weaker dollar. The Powell Humphrey-Hawkins testimony (summary: ‘patient’) did not add anything to what we already know.

Wednesday February 27
Another down day in equities as USTR Lighthizer testified to the House that a China trade deal was not yet certain, and would be a “long process”. Although not directly market-related, it didn’t help that Pakistan shot down two Indian military jets in Kashmir. Also the US Trade Balance (1330), Capital Goods, and Factory Orders (both 1500) reports were all down on the previous figure. World markets followed suit, although NKY managed to close flat in futures helped by the weaker yen.

The Brexit softening by PM May was accompanied by softening from both the hardline (want out, don’t care about a deal) ERG group in her party, and also the opposition Labour Party. Sterling continues to rise to its highest level in nearly eight months. Further oil recovery on the strong EIA beat at 1530 helped CAD, which despite a miss on annualised CPI, improved core monthly to 0.3% from -0.2% previously. Other currencies and Gold fell, resulting in a flat dollar basket. Yields were unusually up 4bp today, following USDJPY on part two of the Powell testimony.

Thursday February 28
Another down day after the failure of the Trump/Kim summit, where no progress was achieved. Also the long-awaited US Q4 GDP print at 1330, which beat estimates (YoY 2.6% vs 2.3% est, but was still well down on Q3 (3.4%). US Jobless Claims also missed. The markets are also working off an overbought condition after the strong 10-week bull run. Only DAX managed to post a small gain. The GDP print gave DXY a small boost (up 0.11%) with all currencies (even GBP) and Gold softening. Yields were up again. Oil continued its post Trump tweet recovery.

Friday March 01
Markets recovered again today, buoyed initially by the Chinese Manufacturing PMI beat at 0145, and German (0855) and Eurozone (1000) unemployment beats. The mood continued into the US Open, but was sharply halted by the double whammy of misses on the Michigan Consumer Sentiment (93.8 vs 95.7) and ISM Manufacturing PMI/Prices Paid at 1500. SPX dropped 0.73% in the two hours after the print. However, it then went on to fully recover into the close.

The GDP feelgood factor continued today with DXY up 0.22%, and all currencies and Gold down. However over half of the move was a plummet by CAD after the severe Q4 YoY GDP miss (0.4% vs 1.2%). The loonie is 9.1% of DXY, and fell 1.32% after the print, meaning if it had gone the other way, DXY would have been flat. The CAD move was accentuated by a 2.5% drop in Oil, fuelling by the ISM PMI miss.

WEEKLY PRICE MOVEMENT
A strong recovery from DAX this week, as it beat US indices and was the best performer. For the first time this year, we have a strong divergence in forex, with GBPCAD easily the biggest mover, up 2.26%. Last week’s crypto rally was short-lived, with BTC and ETH down again. A mixed week for FANGs, which were more volatile than the underlying NDX.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on UUP. The equity and index prices are now based on the cash close each day.

  • Rate decisions in EUR, CAD and AUD
  • Non-farm payrolls in US and Canada
  • Australian and Eurozone Q4 GDP
  • China’s main political conference

NEXT WEEK (all times are GMT)
(Calendar High volatility items are in bold)

Monday March 04
A quiet start to a busy week, with limited scheduled news, so as usual, the trade war and Brexit will dominate. Brazil and Argentina are closed for two days for Carnival. India is also closed for Mahasivarathri Day.

00:30 AUD Aus Building Permits (MoM)
09:30 GBP UK Markit Construction PM

Tuesday March 05
The 13th National People’s Congress in China is expected to produce economic growth targets going forward, and review intellectual property and technology transfers, key areas in the trade dispute. The key scheduled event is the RBA rate decision. Fed Rosengren (hawk, 2019 voter) speaks at 1230, followed two hours later by Kashkari (dove, 2020 voter). Barkin (hawk, non-voter) is also on. Brazil and Argentina remain closed.

01:45 CNY China Caixin Services PMI
03:30 AUD RBA Rate Decision/Statement
07:00 EUR Germany Retail Sales (MoM)
09:00 EUR Eurozone Markit PMI Composite
09:30 GBP UK Markit Services PMI
10:00 EUR Eurozone Retail Sales (YoY)
14:00 NZD NZ GDT Milk Index
14:45 USD US Markit Services/Composite PMI
15:00 USD US ISM Non-Manufacturing PMI
15:00 USD US New Home Sales (MoM)
19:00 USD US Monthly Budget Statement
21:30 WTI API Oil Stock
23:01 GBP UK BRC Like-For-Like Retail Sales (YoY)

Wednesday March 06
The Canadian rate decision is expected to be a hold, but watch out for Gov Poloz remarks. It’s Australia’s turn to report Q4 GDP, which we have seen has moved markets in other countries. The ADP ‘sneak preview’ jobs estimate is 190k, 10k more than the NFP estimate for Friday. Fed Williams (hawkish, 2019 voter) and Mester (hawk, 2019 voter) both speak at 1700. There are also rate decisions on TRY and PLN. Brazil and Argentina reopen.

00:00 CNY China PPI
00:30 AUD Aus GDP Q4
12:15 GBP BoE Cunliffe speech
13:15 USD US ADP Employment Change
13:30 USD US Trade Balance
15:00 USD US Factory Orders (MoM)
15:00 USD US New Home Sales (MoM)
15:00 CAD BoC Rate Decision/Statement
15:00 CAD Canada Ivey PMI
15:30 WTI EIA Oil Stock
19:00 USD Fed Beige Book
21:30 AUD Aus AiG Performance of Construction Index

Thursday March 07
Another day, another rate decision, this time the key Eurozone figure. A hold is virtually certain, but as always it’s the report and press conference 45 minutes later which will be examined. The third day of Fed speeches as well, this time Brainard (was dovish, now centrist, 2019 and 2020 voter) is on at 1715. BoE Tenreyro speaks at 0930.

00:30 AUD Aus Retail Sales s.a. (MoM)
00:30 AUD Aus Imports/Exports/Trade Balance
05:00 JPY Japan Leading Economic Index
09:30 GBP BoE's Tenreyro speech
10:00 EUR Eurozone GDP Q4
12:30 USD US Jobless Claims
12:45 EUR ECB Rate Decision/Statement
13:30 USD US Trade Balance
13:30 USD US Nonfarm Productivity/Unit Labor Costs
13:30 EUR ECB Draghi Presser
13:30 CAD Canada International Merchandise Trade
23:30 JPY Japan Overall Household Spending (YoY)

Friday March 08
Simultaneous US and Canadian NFPs offer strong volatility for USDCAD today. As usual, the AHE figure may be more important than the jobs print itself. This is the final day before the US/Europe summer time disconnect. For the next three weeks, for Europeans, US markets will appear to open an hour earlier (1330 GMT), and for Americans, Europe will appear to run an hour later, closing at 1230 EDT. ECB Mersch (hawkish) speaks at 1630. Fed Chair Powell may also speak.

02:00 CNY China Imports/Exports/TB
09:30 GBP Industrial Production (MoM)
13:30 USD US NFP/AHE/UE/Participation/Productivity
13:30 CAD Canada NFP/UE/AHE/Participation
18:00 WTI Baker Hughes Rig Count


This report is published every week as an email by MatrixTrade.com - you can sign up to receive it here. This blog is supported solely by advertising, so if any of them interest you, please click the links. If you want notification when the blog is updated, please follow me on Twitter, Facebook, Stocktwits or Linkedin (all open in separate windows). Details of how I compile the report are here

Sunday, 24 February 2019

Week to Feb 22nd


Four day week in US markets, Oil climbs for a second week, FTSE100 underperforms

Mon Feb 18
US markets were closed today for President’s Day (George Washington’s birthday), and SPX and bond futures were flat, as was Oil. However Asian markets were strong. The sentiment did not transfer to DAX, which was down. FTSE fared better after news of a firm post-Brexit Australian trade agreement, although it sold off at the very end of the day to end flat. Without US news, the dollar was directionless. DXY was down a mere 0.15%, with AUD and JPY up, but other currencies were up slightly.

Tuesday February 19
Despite an EPS beat WMT, US markets were only slightly up (DJIA was flat), with little reaction to the confirmation from President Xi that trade talks would continue in the US, after the sixth(!) round finished in Beijing. Other markets were down in their cash sessions but recovered in late futures trading to end roughly flat. DXY was down 0.29%, with notable moves up from all currencies and Gold, the exception being JPY which fell 0.3% on a dovish statement from BoJ Governor Kuroda, before ending the day flat. Oil was also flat on the day, 10-year yields were down 3bp in line with USD.

Wednesday February 20
Equities moved up today after the Fed minutes offered little in the way of surprises, given the various speeches since the last release. There was little other news to move markets. DXY fell slightly at the time of the release but ended the day flat. Currencies showed slight and indecisive moves, with GBP and JPY slightly up and CAD a little down. Oil rose sharply at the US Open to finish the day over 1% up (despite the one day late API report which missed). Yields were flat.

Thursday February 21 
The mood changed today as the Mar 1 tariff hike deadline approaches. After a rally in futures before the open, SPX fell fast, and ended the day 0.4% down. Other markets followed suit, with FTSE falling particularly hard, down 0.85%, following profit warnings from CNA.L and BA.L The German Manufacturing PMI miss (47.6 vs 49.7) had relatively little effect on DAX or EUR, in fact it was yet another flat day for DXY (up 0.10%) with EUR and GBP hardly moved, although JPY and Gold were up, and AUD and CAD were down in line with the risk-off mood, the former losing 1% after a dovish report from Westpac and news of Chinese restrictions on Australian coal. Oil gave up a little of yesterday’s gains. Yields were surprisingly up 4bp.

Friday February 22
Today President Trump said it was “more likely than not” that a China trade deal would happen, and this was enough to reverse Thursday’s decline. All equity markets were up, although non-US markets came off a little after their cash sessions closed. USD was down today, but again it was slight with DXY only down -0.13% due to another flat day on EURUSD. Other currencies, Gold, Oil and bond prices (inverse to yields) were up in line. 


WEEKLY PRICE MOVEMENT
NKY was the strongest index this week, adding 2.51%. In a reversal of last week where GBPNZD was the weakest pair, this week it was the strongest. It was a strong week for cryptos after months in the doldrums. Given the 0.50% gain in NDX, it was no surprised that FANGS were directionless.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on UUP. The equity and index prices are now based on the cash close each day.


NEXT WEEK (all times are GMT)
(Calendar High volatility items are in bold)
  • Powell Humphrey-Hawkins Testimony
  • Trade war deadline approaches
  • Another key Brexit debate and vote
  • Delayed US Q4 GDP released

Monday February 25
As earnings season winds down, we have TCEHY (one of the Chinese ‘BAT’ tech stocks) and Dow component HD reporting before the bell. Fed Kaplan (dovish, 2020 voter) and Vice-Chair Clarida (centrist, 2019 and 2020 voter) are on a panel at 1500. There is little in the way of economic news, so as ever, macro focus will be on the China trade talks and Friday’s deadline.

21:45 NZD NZ Retail Sales (Sunday)
05:00 JPY Japan Leading Economic Index
13:30 USD Chicago Fed National Activity Index 


Tuesday February 26
After BoE Governor Carney testifies at the UK parliament inflation report hearings, and embattled UK PM May gives her latest speech on Brexit progress with the EU (not much, we expect), we have Fed Chair Powell giving his semi-annual Humphrey-Hawkins testimony to the House today.

07:00 EUR Germany Gfk Consumer Confidence Survey
10:00 GBP UK Inflation Report Hearings (time approx.)
12:30 GBP UK PM May speech (time approx.)
13:30 USD US Building Permits/Housing Starts
14:00 USD US S&P/Case-Shiller Home Price Indices
14:00 USD Fed Powell Humphrey-Hawkins Day 1 Testimony
15:00 USD US Consumer Confidence
21:30 WTI API Stock Report
21:45 NZD NZ Imports/Exports/TB


Wednesday February 27
Today President Trump starts a two-day meeting with DPRK leader Kim Jong-Un in Hanoi. The Senate have their turn with Jay Powell, with an unscripted Q&A. There will be yet another vote on Brexit, based on any changes reported by PM May the day before. The EIA stock report returns after several weeks.

10:40 EUR DE10Y Bond Auction
13:30 USD US Durable Goods
13:30 CAD Canada CPI
14:00 USD Fed Powell Humphrey-Hawkins Day 2 Testimony
15:00 USD US Pending Home Sales (MoM)
15:00 USD US Factory Orders (MoM)
15:30 WTI EIA Stock Report
18:00 GBP UK Parliamentary vote on Brexit
23:50 JPY Japan Industrial Production (YoY)
23:50 JPY Japan Retail Trade


Thursday February 28
The main release of the day, if not the week is the delayed preliminary 18Q4 US GDP report. Three Fed speakers today, Bostic (dovish, non-voter) at 1350, Harker (dove, 2020 voter) at 1715, and Kaplan again at 1800.

00:01 GBP UK Gfk Consumer Confidence
00:30 AUD Aus HIA New Home Sales (MoM)
01:00 CNY China NBS PMIs
13:00 EUR Germany CPI
13:30 CAD Canada Current Account
13:30 USD US Jobless Claims
13:30 USD US Preliminary GDP/PCE
14:45 USD Chicago PMI
21:30 AUD Aus AiG Performance of Mfg Index
21:45 NZD NZ Building Permits s.a. (MoM)
23:30 JPY Tokyo CPI/Unemployment Rate


Friday March 01
Today is the first day of the new month, and of course the end of the 90-day trade truce, and the date China tariffs are increased from 10% to 25% on $200 billion of goods. The shutdown-delayed December US PCE report (the Fed’s preferred inflation proxy) is released. Fed Bostic (dovish, non-voter) speaks at 1815. Italy presents its latest budget at 1000, which may result in a fresh row with Brussels. Markets in South Korea are closed.

01:45 CNY China Caixin Manufacturing PMI
08:30 GBP UK Markit Manufacturing PMI
08:30 EUR Germany Markit Manufacturing PMI
08:55 EUR Germany Unemployment Change/Rate s.a.
10:00 EUR Eurozone Unemployment Rate
10:00 EUR Eurozone CPI
13:30 USD US Core PCE Price Index/Personal Spending
13:30 CAD Canada GDP
14:45 USD US Markit Manufacturing PMI
15:00 USD Michigan Consumer Sentiment Index
15:00 USD US ISM Manufacturing PMI/Prices Paid
18:00 WTI Baker Hughes Rig Count
23:30 JPY Japan Jobs/applicants ratio


This report is published every week as an email by MatrixTrade.com - you can sign up to receive it here. This blog is supported solely by advertising, so if any of them interest you, please click the links. If you want notification when the blog is updated, please follow me on Twitter, Facebook, Stocktwits or Linkedin (all open in separate windows). Details of how I compile the report are here

Sunday, 17 February 2019

Week to Feb 15th


Possible China tariff extension, Second shutdown averted, Big miss on US Retail Sales

Mon Feb 11
The threat of another government shutdown and President Trump confirming no meeting with his counterpart in China before the Mar 1 tariff deadline led to caution in the US equity market today, with SPX and NDX closing flat, although non-US markets were comfortably up, after last week’s Thursday/Friday pullback, following a bid in China markets as they reopened. DXY—which likes trade war tension—added 0.45% and broke 97 to make a new 2019 high. All currencies, Gold, Oil and 10-year bond price (inverse to yields) were down in line.

Tuesday February 12
A possible deal to avert the shutdown (despite Trump being “unhappy”) was enough to rally markets today with SPX up 1.3%. NDX and DJIA did even better. The story was the same in Europe and Asia, with NKY sharply up at the open after Monday’s holiday in Japan. FTSE could only break even on a stronger GBP. The dollar had a ‘Turnaround Tuesday’ and lost ground against all currencies. Gold and Oil were up in line, but bond yields carried on rising, up 2bp today, the same as yesterday. Fed Chair Powell’s speech had little effect.

Wednesday February 13
Global stocks continued upwards, as President Trump hinted at an extension (to the Mar 1st China tariff hike from 10% to 25%) if a “real deal” was close, although the gain (SPX up 0.3%) was muted after Senator Rubio tweeted that buybacks should be taxed. Buybacks are of course a major reason for market strength.

USD was strong overall after the CPI beat at 1330, with DXY up 0.53%. However (only) NZD bucked the trend, adding 1% after RBNZ said there would be no rate cuts for two years. GBP had a brief 70 pip spike on chatter about an Article 50 (Brexit) extension but this soon faded, and all currencies except NZD, and Gold were down. Oil was up again after comments from the Saudi energy minister, and evidence that cuts were being adhered to.

Thursday February 14
A miss on the final German Q4 GDP QoQ and working day adjusted figures at 0700 (although YoY beat, oddly), followed by a severe miss on the shutdown-delayed December US Retail Sales print (Core -1.85% vs +0.10% est) at 1330 (coupled with a Jobless Claims miss), was enough to send SPX sharply down over 20 handles at the US open, and to finish down 0.3% on the day. Global indices went the same way.  The Retail Sales miss also cause an instant spike down in yields and DXY. The basket finished 0.19% down. AUD joined EUR and JPY in appreciating, but GBP was weak all day, after the UK 10-year bond auction only fetched 1.16% (prev 1.27%). CAD was unusual. The relatively unimportant Manufacturing Shipments (MoM, Dec) print missed badly (-1.3% vs 0.2%), but this was enough to soften it by 0.5% (and 0.9% against JPY). Gold was up in line with the weaker dollar, but although Oil continued upwards. DJIA component KO matches EPS estimates, but reduced forward guidance by 1%, shares dropped 7.5% on the news.

Friday February 15
After falling in the European futures pre-market, DJIA soared on Friday, up 1.74% on trade war hopes, as President Xi said the two sides would meet again next week in Washington. The effect was more muted in NDX which is not as trade war sensitive, but global markets rose on the news, with DAX up nearly 2%. The effect was also helped by the Michigan Consumer Sentiment beat at 1500 (95.5 vs 93). After a brief spike up on the Michigan release, DXY ended slightly down as EUR and JPY were for once flat, but less components GBP and CAD rose. AUD was also sharply up on the trade news, helped by an $8 rise in Gold, and oil continued upwards. Yields were up on stock-bond rotation. At the end of the day President Trump decided he would use emergency powers to get his wall money. Markets were not affected.


WEEKLY PRICE MOVEMENT
After being the weakest last week, DAX was the strongest index this week. DXY was only slightly up, with Brexit-troubled GBP the weakest currency. The reversal also applies in currencies, with last week’s loser NZD being the strongest, therefore shorting GBPNZD would have been the best trade. Another quiet week for cryptos and FANGs as the January volatility fades.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on UUP. The equity and index prices are now based on the cash close each day.


NEXT WEEK (all times are GMT)
(Calendar High volatility items are in bold)
  • Four day week in US markets
  • FOMC minutes hawkish risk
  • Wal-Mart completes Dow earnings
  • Knife-edge German PMIs

Monday February 18
US Markets are closed for President’s Day (George Washington’s birthday). Asia and Europe are of course open, but as always with US market holidays, a quiet day is expected. There is no significant news.

23:50 JPY Japan Machinery Orders

Tuesday February 19
China Trade talks resume and traders will be looking for soundbites. The earnings season is pretty much over now, but we have the final DJIA component (2.62% weight) China-sensitive WMT reporting before the bell (after last week’s fall in Retail Sales, WMT is the biggest bricks-and-mortar retailer in the world). Fed Mester (hawk, 2019 voter) speaks at 1350.

00:30 AUD RBA Meeting's Minutes
09:30 GBP UK AHE/UnEmp/Claimant Count Change (UnEmp e 3.9% p 4.0%)
10:00 EUR Germany ZEW Sentiment Surveys
14:00 NZD NZ GDT Milk Index
21:30 WTI API Stock
21:45 NZD NZ PPI
23:50 JPY Japan Imports/Exports/Trade Balance

Wednesday February 20
The most important day of the week, when we read the Fed minutes from their January meeting, where they calmed the market. The risks are to a less dovish internal discussion, which could be bearish for equities, ie neutral could be seen as hawkish. Fed Bullard (dove, 2019 voter) speaks in New York today, as does Kaplan (dovish, non-voter) at 1810. Again there is no EIA Oil stock print this week.

00:30 AUD Aus Wage Price Index (QoQ)
07:00 EUR Germany PPI
19:00 USD FOMC Minutes
23:50 JPY Foreign investment in Japan stocks

Thursday February 21 
The German and Eurozone Markit PMIs are more important than usual because the German estimate of 49.9 is just on the wrong side of contraction/expansion, a move back over 50 would be bullish for DAX. Chinese ‘BAT’ company BIDU reports after the bell. Fed Bostic (dovish, non-voter) speaks today at 1250.

00:30 AUD Aus NFP/UnEmp (NFP e 15k p 21.6k)
04:30 JPY Japan All Industry Activity Index
07:00 EUR Germany CPI (e 1.7% p 1.7%)
08:30 EUR Germany Markit PMIs
09:00 EUR Eurozone Markit PMIs
09:30 GBP UK PSBR
13:30 USD Jobless Claims
13:30 USD Philly Fed Manufacturing Survey
13:30 USD Durable Goods
14:45 USD US Markit PMIs
15:00 USD Existing Home Sales (MoM)
23:30 JPY Japan National CPI

Friday February 22
A Fitch credit rating for Italy is expected today, and the risk is to the downside (which may already be priced, you may remember when S&P didn’t change their outlook a few months ago, the MIB soared). Fed Bullard speaks again at 1830, as do Harker (dove, non-voter) and Quarles (hawkish, voter) at the same time. There are rate decisions on COP and LKR.

07:00 EUR Germany GDP
09:00 EUR Germany IFO Sentiment Surveys
10:00 EUR Eurozone CPI
13:30 CAD Retail Sales
18:00 WTI Baker Hughes Rig Count

This report is published every week as an email by MatrixTrade.com - you can sign up to receive it here. This blog is supported solely by advertising, so if any of them interest you, please click the links. If you want notification when the blog is updated, please follow me on Twitter, Facebook, Stocktwits or Linkedin (all open in separate windows). Details of how I compile the report are here