Showing posts with label EURAUD. Show all posts

Sunday, 26 June 2022

Week to Jun 24th

Strong bounce back in markets
MY CALL THIS WEEK : BUY EURAUD


LAST WEEK


In a week of two-way volatility and US-EU divergence, the overall theme was of improving risk sentiment. The SPX managed to hold last Friday’s low in an early dip and has since recovered nearly 300 points (+7%). Associated markets helped the bullish case as yields fell, oil and commodities continued to drop and the USD stayed steady. Inflation expectations were revised lower. Even Bitcoin provided a tailwind as it survived the key 20k re-test and is already +20% off the lows. Pockets of weakness continued, however, especially in the eurozone. DAX made new lows on Wednesday and Thursday and the euro dropped due to poor PMIs and the likelihood that the ECB will be severely limited in any hawkish ambitions.

Developments last week suggest an interim bottom has been struck or is very close. A 5-leg decline has developed on SPX and when it completes, we should see a correction to the entire downtrend, often a 50-61% retrace. Beyond that, the view gets bearish again as the presence of trend suggests another major leg lower should unfold. Just how severe this will be hinges on a number of factors, particularly on whether or not the US can avoid a recession. 


WEEKLY PRICE MOVEMENT

The biggest index mover this week was NDX, up 5.79%. The top forex mover was EURJPY up 1.08%. Crypto recovered, and FANG outperformed NDX.

My EURNZD long made 0.59% this week, meaning I am now ahead 3.68% with 12/23 (52%) wins. This week I will carry on the theme but switch to buying EURAUD.
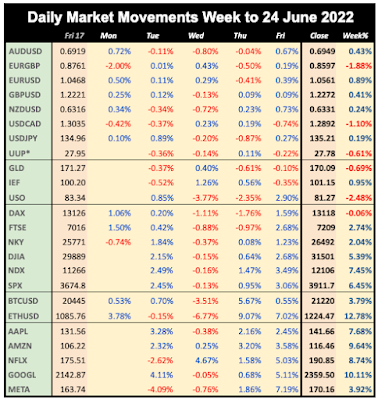


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.


NEXT WEEK

As we close out the month, quarter and half-year, the only key US prints next week are the annualised GDP and ISM PMI. Also of interest are the PCE The big central bank event is the ECB Sintra summit (their version of Jackson Hole which is at the end of August), hence the raft of speeches on Wednesday. Markets didn't worry about the Powell testimony this week, so it is reasonable to assume there will be nothing new from the Fed Chair at Sintra. Ms Lagarde however is another story, a surprise from her could move DXY.

German inflation is still disappointingly on the increase, not helped by the fact that lagging EU tightening, a policy for all 27 member states now disadvantages the richest one, and may be a factor in SPX outperforming DAX by over 6% last week. One often overlooked release is PCE, said to be the Fed's preferred method of measuring inflation. The YoY print on Thursday is estimated to fall slightly, could this be a turning point in sentiment.


CALENDAR  (all times are GMT, volatile items in bold)

Monday June 27
12:30 US Durable/ND Capital Goods Orders (DG e0.1% p0.5%)
14:00 US Pending Home Sales
18:30 ECB Pres Lagarde speech

Tuesday June 28
06:00 Germany Gfk Consumer Confidence
08:00 ECB Pres Lagarde speech
13:00 US Housing/Home Price Indices
14:00 US Consumer Confidence(Jun)
23:50 Japan Retail Sales

Wednesday June 29
01:30 Aus Retail Sales (e0.4% p0.9%)
09:00 Eurozone Business/Consumer Confidence
11:10 BoE Governor Bailey speech
12:00 Germany CPI (e8.8% p8.7%)
12:30 US PCE (QoQ)
12:30 US GDP Annualised (e-1.5% p-1.5%)
13:00 Fed Chair Powell speech
13:00 BoE Gov Bailey speech
13:00 ECB Pres Lagarde speech
15:00 ECB Pres Lagarde speech
23:50 Japan Ind Production

Thursday June 30
01:00 China PMIs (Mfr e49.6 p49.6)
06:00 UK Q1 GDP (QoQ e0.8% p0.8%)
06:00 Germany Retail Sales (p-0.4%)
07:55 Germany UnEmp
09:00 Eurozone UnEmp
12:30 US PCE (MoM and YoY) (YoY e4.7% p4.9%)
12:30 US Jobless Claims
12:30 Canada MoM GDP
13:45 Chicago PMI
22:30 Aus AiG Mfg Index
23:30 Japan Jobs/UnEmp
23:30 Tokyo CPI
23:50 Japan Tankan Mfr Index (e13 p14)

Friday July 1
01:45 China Caixin Mfr PMI
07:55 Germany S&P Mfr PMI
08:30 UK S&P Mfr PMI
09:00 Eurozone CPI (e7.8% p8.1%)
13:45 US S&P Mfr PMI
14:00 US ISM Mfr PMI (p56.1)

Sunday, 17 April 2022

Week to Apr 15th

Markets fall despite CPI miss/MSCI beat. EUR down on dovish ECB
MY CALL THIS WEEK : BUY EURAUD


LAST WEEK

In a shortened Easter week, stock markets attempted to strike a bottom on ‘Turnaround Tuesday’ but failed to break out of corrective channels and NDX closed the week right at the low. Meanwhile, 10-year yields and the US dollar broke to yet more 2022 highs with the US10Y reaching 2.82% and DXY breaking above 100. The USD was helped on by a 1c collapse in EUR triggered by the ECB meeting and the snail’s pace the bank has mapped towards normalization.


Earnings season opened with, as always, the major banks and the top DJIA stock UNH reporting. The reactions were briefly as you would expect, with UNH, MS and C all beating on EPS and revenue, and rising 2% briefly. JPM missed on EPS and WFC missed on revenue, both fell sharply. A clear sign of a bearish market is when beats rise less than misses fall. US CPI at 6.5% was lower than the 6.6% estimate, but still higher than last month. The market didn’t like it. Even the surprise strong beat on Michigan CSI on Friday (65.7 vs 59.0 est) could not lift spirits.


With so many markets closing right at weekly (some at yearly) highs or lows, it would be normal to see continuation of Thursday's moves early next week. However, there are some major reversals setting up and we can look for a dollar top in the coming sessions followed slightly later by yields topping out towards the end of the month. Stocks should turn higher by the latest on Tuesday and DAX looks ready to run sooner than most.


WEEKLY PRICE MOVEMENT


The biggest index mover was rate-sensitive NDX which was down 3.03%,. Clearly this was the issue, as other indices moved much less. The top forex mover was GBPJPY up 1.91%. Bitcoin and Ethereum pulled back again, and again FANGs underperformed NDX as a whole..


Last week's EURAUD long position gained 0.12%, which means I am ahead 3.96% this year, with 7/14 (50%) wins. This week I am buying EURAUD again.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.


NEXT WEEK


In the absence of any major news, the focus is likely to be on earnings, with reports from so-called bellwether IBM and heavyweight JNJ (together 5.85% of DJIA), and NFLX and TSLA (5.95% of NDX). The scheduled macro news is primarily from outside the US, with China and Canada most prominent. Markets seem to have largely discounted Ukraine, and priced in the rate hike schedule. Note Europe is closed on Monday for the Easter break.


CALENDAR  (all times are GMT, volatile items in bold)


Monday April 18

02:00 China GDP (YoY e4.4% p4.0%)

02:00 China Retail Sales (YoY e0.7% p6.7%)


Tuesday April 19

01:30 RBA MPC Minutes

04:30 Japan Ind Production

11:00 JNJ Earnings

12:30 US Building Permits/Housing Starts

20:00 NFLX, IBM Earnings

23:50 Japan Imports/Exports/TB


Wednesday April 20

01:15 PBoC Rate Decision/Statement (e3.7% hold)

06:00 Germany PPI

09:00 Eurozone Ind Production

12:30 Canada BoC CPI (Core YoY e5.0% p4.8%)

21:00 TSLA Earnings


Thursday April 21

09:00 Eurozone CPI

12:30 US Jobless Claims

12:30 Philly Fed Mfr Survey(Apr)

14:00 Eurozone Consumer Confidence

16:30 BoE Governor Bailey speech

22:00 Australia PMIs

23:30 Japan National CPI


Friday April 22

06:00 UK Retail Sales

07:30 Germany PMIs (Mfr e54.4 p56.9)

08:00 Eurozone PMIs (Comp e54.0 p54.9)

08:30 UK PMIs (Svcs e60.3 p62.6)

12:30 Canada Retail Sales (e-0.5% p3.2%)

13:45 US PMIs

14:30 BoE Governor Bailey speech

Saturday, 9 April 2022

Week to Apr 8th

Dollar and yields surge on hawkish Fed marks. FTSE outperforms
MY CALL THIS WEEK : BUY EURAUD


LAST WEEK


Most equity markets fell this week on hawkish comments from Fed Brainard and also the FOMC minutes where it was reported that 50bp rate hikes “could be appropriate”. The exception was the oil and bank heavy UK FTSE which came within a whisker of a 44-month high. There was little scheduled data, and as the Ukraine stalemate continues, the war fades from traders’ minds (SPX underperformed DAX), and focus is on rate hikes, and inflation which is driving them (see next week). The same factors drove the dollar to a new 11-month high, and yields to a 3-year high, whilst the yield curve retraced last week's move back into positive territory. JPY, gold and silver had inside weeks. Other metals and oil had reduced volatilty as they consolidate off the highs.


WEEKLY PRICE MOVEMENT

The biggest index mover was rate-sentitive NDX which was down 3.59%. The top forex mover EURUSD down 1.59%. Bitcoin and Ethereum pulled back. FANGs underperformed NDX as a whole..

Last week's EURJPY long position lost 0.10%, which means I am ahead 3.84% this year, with 6/13 (46%) wins. This week I am buying the oversold EURAUD


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.


NEXT WEEK

Earnings season starts next week, with as always JPM first out of the door on Wednesday, followed by WFC, C and GS the next day. Also Thursday sees the ECB rate decision meeting and press conference. We have inflation from the UK and China as well as the all-important US, which are all forecast to rise, a miss on this print would be positive for stocks short-term. Finally, this is Easter week, and markets are closed for Good Friday (UK and Germany have a four day break with Monday off as well)


CALENDAR  (all times are GMT, volatile items in bold)

Monday April 11
01:00 BoJ's Governor Kuroda speech
01:30 China CPI (e1.2% p0.9%)
06:00 UK GDP MoM
06:00 UK Ind/Mfr Production
11:00 UK NIESR GDP Est (time approx.)
13:30 Fed Bowman speech
16:00 Fed Williams speech

Tuesday April 12
06:00 UK Claimant Count/AHE/UnEmp (UE e3.8% p3.9%)
06:00 Germany CPI (e7.6% p7.6%)
08:00 ECB Bank Lending Survey
09:00 Germany ZEW Sentiment
12:30 US CPI (Core e6.6% p6.4%)
16:10 Fed Brainard speech
18:00 US Monthly Budget Statement

Wednesday April 13
00:30 Aus Westpac Consumer Confidence
02:00 China Imports/Exports/TB
06:00 UK CPI (e6.6% p6.2%)
06:15 BoJ Governor Kuroda speech
09:30 DE10Y Bond Auction
12:30 US PPI
14:00 BoC Rate Decision/Statement (e0.5% hold)
15:15 BoC Press Conference

Thursday April 14
01:00 Aus Consumer Inflation Expectations
01:30 Aus Jobs/Unemp (UE p4.0%)
04:30 Japan Ind Production
05:00 China FDI (time approx.)
11:45 ECB Rate Decision/Statement (e0% hold)
12:30 US Jobless Claims
12:30 US Retail Sales
12:30 ECB Pres Lagarde Presser
14:00 Michigan CSI (e60.6 p59.4)

Friday April 15
No significant news, markets closed

Sunday, 21 November 2021

Week to Nov 19th

NDX ATH, Sterling rallies, Austria lockdown
MY CALL THIS WEEK : SELL EURAUD


THIS WEEK


This week saw beats (not necessarily good) on US Retail Sales and UK inflation. The latter buoyed sterling, the only currency to beat the dollar. This made FTSE the week's worst performing index. News of rising continental European COVID cases and a full lockdown in Austria made EURGBP the largest forex mover, hitting 2020 lows.

Increased volatility led to extremes in the NDX and the dollar. The tech index hit new all-time highs, and also the NDX/DJI ratio reached its highest level since 2000. At 0.465, the ratio is only 1% below the 0.47 spike on Mar 13, 2000, a level it only held for half a day. (The low was 0.11 on 24 Sep 2002). DXY had its strongest week for five months, and hit a 16 month high, with EUR recording the same periods for lows. Gold had its best week in two months, and made new 5-month high, before fading as the dollar rallied mid-week. Yields and Gold largely followed the dollar.


WEEKLY PRICE MOVEMENT

The biggest mover for a third week was FTSE, down 1.69% on a strong pound. The top forex mover was EURGBP this week, down 1.71%. Bitcoin and Ethereum were down sharply, whereas FANGs performed well, in line with NDX.

Last week’s EURGBP short made 1.71%, taking my year to date profit to 7.90% and 31/45 wins. This week I am selling EURAUD.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.


NEXT WEEK

The week ahead is foreshortened to three and half days in the US, with Thanksgiving and the half-day on Black Friday which opens the holiday season. The minutes of the last FOMC meeting are published and there are interest rate decisions in China and New Zealand. Otherwise it is a fairly quiet week for important data.


CALENDAR  (all times are GMT)

Monday November 22
01:30 PBoC Interest Rate Decision (e3.85% hold)
13:30 Chicago Fed National Activity Index
15:00 Eurozone Consumer Confidence
22:00 Aus Commonwealth Bank PMIs

Tuesday November 23
08:30 Germany Markit PMIs (Mfr e56.7 p57.8)
09:00 Eurozone Markit PMIs (Comp e53.1 p54.2)
09:30 UK Markit Mfr/Svcs PMIs (Svcs 58.5 p59.1)
11:00 BoE Haskel speech
14:45 US Markit PMIs
18:00 BoC Beaudry speech
22:15 RBA Bullock speech

Wednesday November 24
00:40 RBA Bullock speech
01:00 RBNZ Rate Decision/Statement (e0.75% p0.5%)
02:00 RBNZ Press Conference
09:00 Germany IFO Sentiment Indicators
12:45 UK Autumn Budget
13:30 US Durable/ND Capital Goods (NDC Oct e0.6% p0.8%)
13:30 US Jobless Claims
13:30 US Q3 GDP Annualized (e2.1% p2.0%)
15:00 US PCE QoQ
15:00 Michigan CSI
15:00 US New Home Sales (MoM)(Oct)
19:00 FOMC Minutes

Thursday November 25
07:00 Germany GDP
12:30 ECB MPC Accounts
23:30 Tokyo CPI

Friday November 26
00:30 Aus Retail Sales (MoM e2.5% p1.3%)