Showing posts with label yields. Show all posts

Sunday, 3 July 2022

Week to Jul 1st

Markets back down again
MY CALL THIS WEEK : BUY EURCAD


LAST WEEK

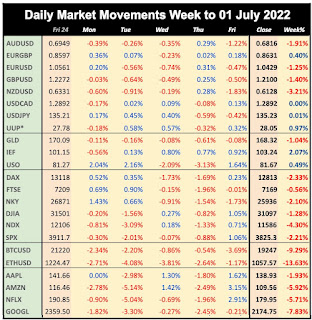
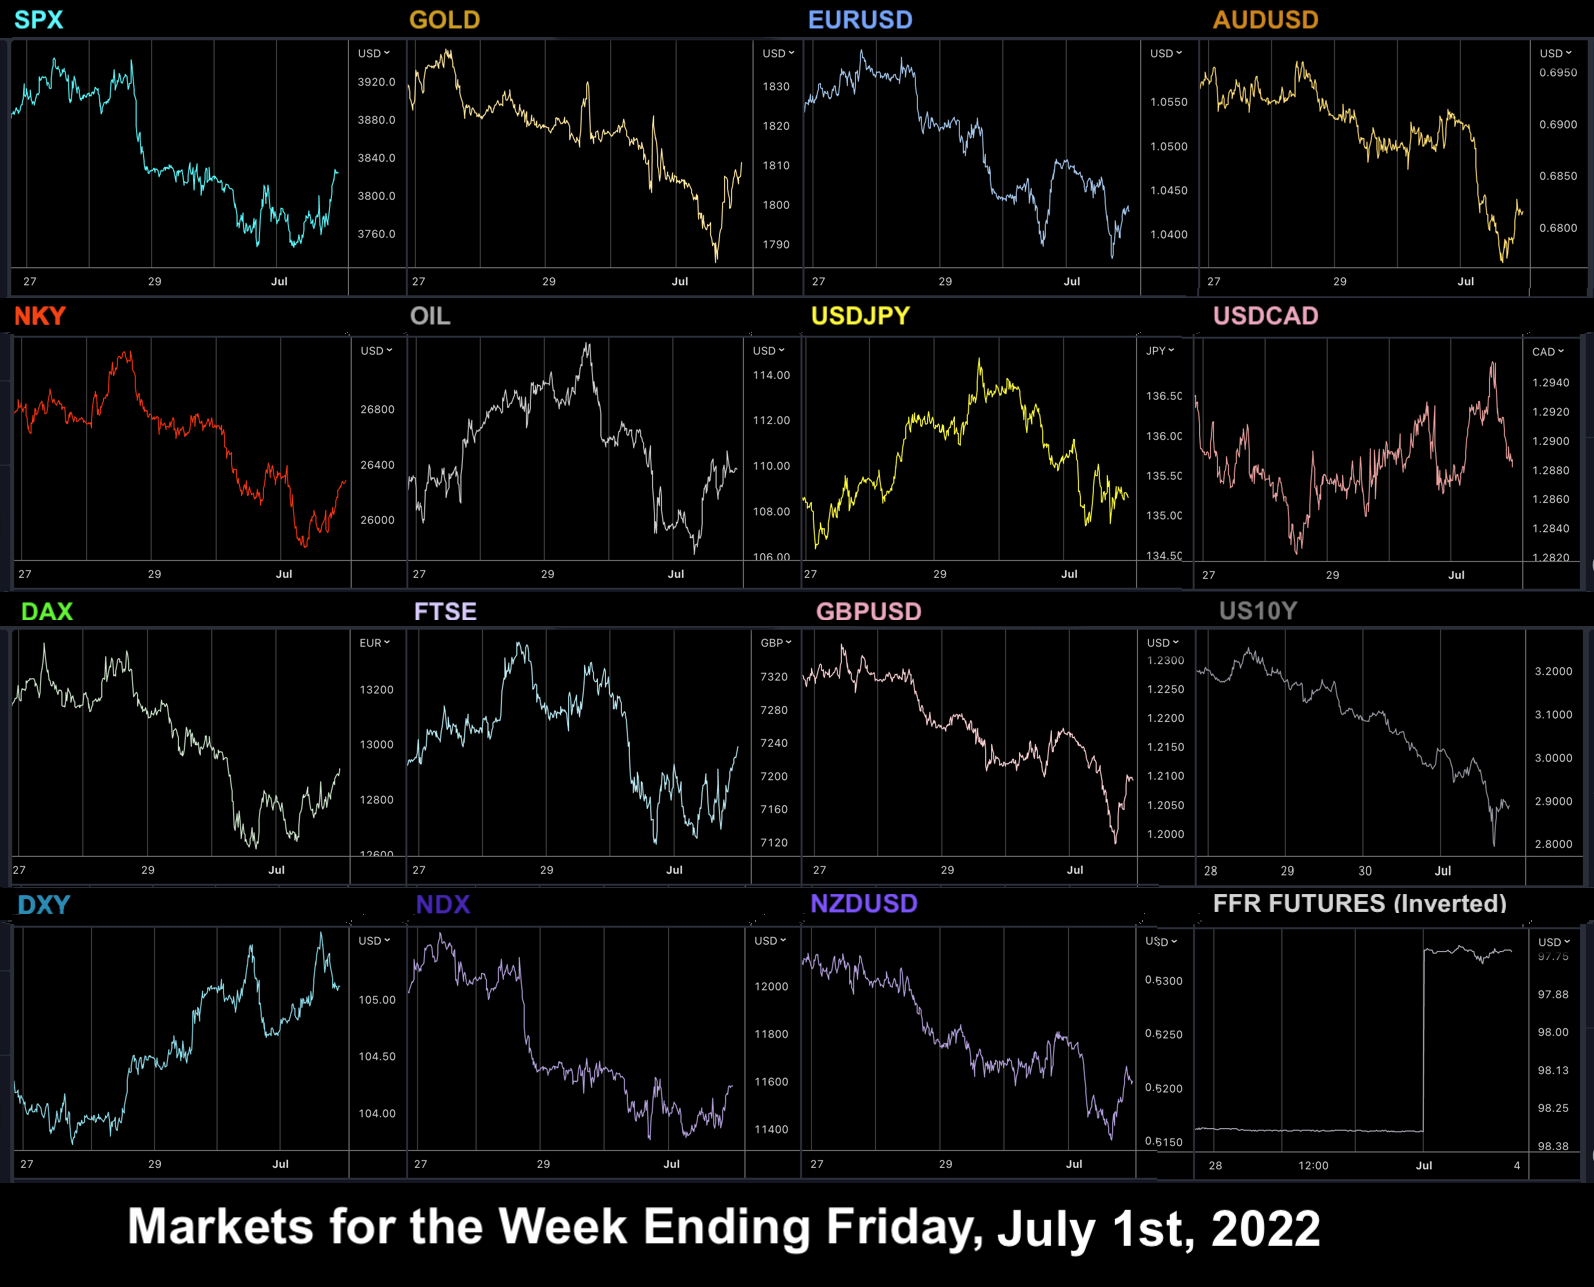
In a week where inflation concerns mixed with recession fears, the net effect was negative on stock markets as SPX and NDX retraced the late June rally and DAX maintained its relative weakness with further June lows. Currencies were mixed, but the general theme was one of USD strength as it made four higher highs and higher lows after bottoming on Monday. EURUSD re-tested the 1.035 low and looks on shaky ground as the annual central bank summit at Sintra underlined the ECB’s lack of options. ECB President Lagarde tried to strike a hawkish tone by saying that they could “move faster” depending on the data, which looked especially toothless when Spain’s CPI came in at 10.2% soon after, beating expectations by 1.4%. It begs the question: if not now, then when? Note the loose EU tone is not helping European stocks.

Inflation now looks more of a European problem than a US one as the Fed’s hiking cycle appears to be working. Long-term yields fell in the US and the 5-year forward inflation expectation rate fell to 2.08%, down from a high of 2.67% in April. Meanwhile, the 10s3s fell to 1.15% and the fall is accelerating – as inflation concerns fade, recession fears are picking up.


WEEKLY PRICE MOVEMENT

The biggest index mover this week was NDX, down 4.30%. The top forex mover was NZDUSD or NZDCAD down 3.21%. Crypto fell sharply again, and FANG underperformed NDX.

My EURAUD long made 1.12% this week, meaning I am now ahead 4.80% with 13/24 (54%) wins. This week I will carry on the theme but switch to buying EUR against the biggest riser CAD, which I think may pull back, so I will be long EURCAD.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.


NEXT WEEK

A new month, quarter and half year, and of course the main event is NFP. Although inflation is the primary driver of expectations of Fed action (and thus SPX pricing), the jobs report still has some effect. Traders are looking for signs that the tightening will be slowed down, and a poor report could therefore boost markets.

The week is of course foreshortened in the US (only) for Independence Day, hence why the ADP report is a day late. The only other significant event is the RBA rate decision, where a 50bp hike is expected, and may reverse the AUD trend, which is now trading at a one-year low. There are several trade balance and PMI reports but as you know, these have much less effect on markets than central bank actions.


CALENDAR  (all times are GMT, volatile items in bold)

Monday, July 4
01:00 Aus TD Securities Inflation
01:30 Aus Building Permits
06:00 Germany Trade Balance
13:30 Canada S&P Mfr PMI
14:30 BoC Business Outlook Survey
22:30 Aus AiG Construction Index
23:00 Aus S&P Svcs PMI

Tuesday, July 5
01:45 China Caixin Svcs PMI
04:30 RBA Rate Decision/Statement (e1.35% p0.85%)
07:55 Germany S&P Comp PMI
08:00 Eurozone S&P Comp PMI
08:30 UK S&P Comp PMI
09:30 UK Financial Stability Report
14:00 US Factory Orders
16:30 BoE Tenreyro speech

Wednesday, July 6
06:00 Germany Factory Orders
08:10 BoE Pill speech
09:00 EC Growth Forecasts
09:00 Eurozone Retail Sales (e5.4% p3.9%)
09:30 DE10Y Bond Auction
13:45 US S&P Comp & Svcs PMI
14:00 ISM Svcs PMI (e55.7 p55.9)
18:00 FOMC Minutes

Thursday, July 7
01:30 Aus Imports/Exports/TB
11:30 ECB MPC Minutes
12:15 US ADP (e200k p128k)
12:30 US Trade Balance
12:30 US Jobless Claims
12:30 Canada Trade Balance
14:00 Canada Ivey PMI
23:50 Japan Current Account

Friday, July 8
12:30 US NFP/AHE/UnEmp (NFP e250k p390k)
12:30 Canada NFP/AHE/UnEmp (UE e5.2% p5.1%)

Saturday, 12 February 2022

Week to Feb 11th

Highest #CPI for 40 years. Yields and Oil at multi-year highs
MY CALL THIS WEEK : BUY EURGBP


LAST WEEK


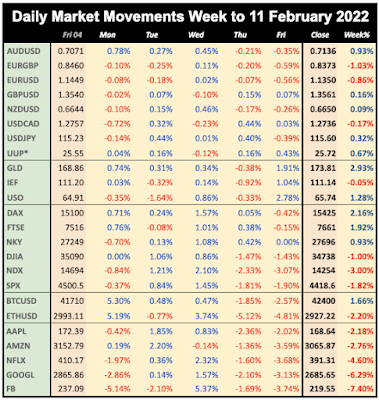
As is often the case, markets were progressing gently only to be hit by the worse than expected CPI print on Thursday, which at 7.5% was the highest for 40 years. Higher inflation implies earlier rate hikes, and Fed hawk Bullard said “I'd like to see 100 basis points in the bag by July 1." Indices pulled back with SPX closing an inside week, and rate-sensitive NDX down 3%. The effect was largely confined to the US, and DAX and FTSE were up on the week. Although the dollar briefly spiked on the CPI release, it quickly retraced and also had an inside week, although Gold was well up, making a 12-week and 2022 high. Oil reached $94, a six-year high, and yields crossed 2% for the first time since July 2019.


WEEKLY PRICE MOVEMENT

The biggest index mover was again NDX, down 3.0%. The top forex mover was EURAUD down 1.79%. Bitcoin and Ethereum were flat, and FANG suffered again, falling more than NDX in aggregate.

Last week's AUDNZD long position made 0.84%, which means I am ahead 3.31% this year, with 3/5 (60%) wins. This week I am buying EURGBP as I think it has bounced off the 0.83 bottom, but pulled back last week, making a good entry.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.


NEXT WEEK

Next week’s US data is light, only Retail Sales (which is not rising with inflation). The all-important inflation releases come from China (low), the UK and Canada (high but not as high as US). FOMC minutes probably the main US takeaway. Everything is about inflation. Earnings season enters the ‘retail’ phase when WMT report on Thursday.


CALENDAR  (all times are GMT, volatile items in bold)

Monday February 14
23:50 Japan Q4 Prelim GDP (QoQ e1.4% p-0.9%)

Tuesday February 15
00:30 RBA MPC Minutes
04:30 Japan Ind Production
07:00 UK Claimant Count/AHE/UnEmp (UnEmp e4.1% p4.1%)
10:00 Eurozone Q4 Prelim GDP (YoY e4.6% p4.6%)
10:00 Germany ZEW Sentiment Surveys
13:30 US PPI

Wednesday February 16
01:30 China CPI (e1.0% p1.5%)
07:00 UK CPI (e5.4% p5.4%)
10:00 Eurozone Ind Production
10:30 DE10Y Bond Auction (time approx.)
13:30 US Retail Sales (Control e0.1% p-3.1%)
13:30 Canada BoC CPI (e4.6% p4.0%)
18:30 BoC Lane speech
19:00 FOMC Minutes
23:50 Japan Imports/Exports/TB

Thursday February 17
00:30 Aus NFP/UnEmp (NFP e-15k p64.8k)
09:00 Eurozone Economic Bulletin
13:30 US Building Permits/Housing Starts
13:30 US Jobless Claims
13:30 Philly Fed Mfr Survey
23:30 Japan National CPI

Friday February 18
07:00 UK Retail Sales
13:30 Canada Retail Sales (e1.2% p0.7%)
15:00 Eurozone Consumer Confidence

Sunday, 21 February 2021

Week to Feb 19th

NKY 30-year high, Yields 12 month high, New US ATHs
MY CALL THIS WEEK : BUY EURGBP 


This week President Biden said he would ‘go big’ on COVID stimulus, and the vaccine rollout continued without problems. Stocks soared again, with NKY hitting 30,000 for the first time in 30 years. However, by mid-week, the 10-year yield hit a one-year high, and the dollar followed it upwards. The Fed saying inflation risks were “weighted to the downside”, which put a damper on already overheated stocks (SPX is up 20% since the election) and the dollar, resulting in a flat week for DXY. GBP hit 1.40 for the first time since April 2018 and Gold made a 7-month low. Nevertheless, despite the first 3-day losing streak of 2021, DJIA only moved 0.11% the entire week, DXY only 0.16% and Oil 0.65%, so consolidation rather than collapse.


Next week is the final week of February, and the main highlight the Semiannual  Monetary Policy Report to Congress by Fed Chair Powell, known as the Humphrey-Hawkins testimony named after the two senators who introduce the Act of Congress mandating the report.


Mon Feb 15

Futures were flat today as US markets remained closed. Europe was positive with FTSE rising 2.5% and DAX 0.42%.. NKY broke the 30,000 barrier for the first time in 30 years. The dollar was down very slightly, and Oil was slightly up in line. Gold was flat on the day.


Tuesday February 16

Markets briefly made new highs today before pulling back, although from a cash point of view (ignoring Monday) they were up, and bonds (yields up 7bp), Gold and JPY were sharply and noticeably down line. The dollar reflected this, up across the board. Oil was up in line.


Wednesday February 17

Markets fell further today, as bonds and JPY recovered (although Gold did not, driven down by a strong risk-off mood, as seen in NDX dropping 0.6% against a flat SPX. The drop was particularly sharp after the Fed minutes at 1900 as is often the case. USD and Oil also fell on the Fed minutes, and continued to so for the rest of the week.


Thursday February 18

A sign that the market euphoria has probably topped is that today saw the first three-day losing streak of 2021. All equity markets and Oil were down. The dollar pulled back after its two day rising streak, and of course after the Fed comments. Gold and bonds were flat.


Friday February 19

Markets attempted to rally today but pulled back into the close (leaving Europe green) with NDX underperforming, and Oil down and Gold up in line. The US 10-year yield was up 7bp again to a new 12-month high. All in all a consolidating week, for example DJIA only moved 0.11% the entire week, DXY only 0.16% and Oil 0.65%


WEEKLY PRICE MOVEMENT

A flattish week for indices, with NKY at 1.69% the best performer. The strongest pair was AUDJPY up 2.10%. Bitcoin continued to go stratospheric, hitting new highs. FANGS notably underperformed NDX as a whole.


My AUDUSD sell was a disaster, losing 1.43% and wiping out most of my profit for the year. The running total is a mere 0.24% with 5/7 wins. This week I am betting that as EURGBP is the most oversold since Mar 2015, it will bounce back. Therefore I am buying EURGBP.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.


NEXT WEEK (all times are GMT)

(Calendar High volatility items are in bold)


  • Final week of February
  • Powell Humphrey-Hawkins testimony
  • Heavy CB speaker roster
  • US GDP second reading


Monday February 22

Not much news, but we have important speeches from UK Prime Minister Boris Johnson and ECB President Lagarde.


02:00 PBoC Interest Rate Decision (time approx.)

09:00 Germany IFO Sentiment

11:00 UK Prime Minister Boris Johnson speech

13:30 Chicago Fed National Activity Index (Jan)

13:45 ECB President Lagarde speech

20:30 Fed Bowman speech


Tuesday February 23

Today, Chair Powell gives his twice-yearly MPC report to the Senate. Otherwise US news is light.


07:00 UK UnEmp/Claimant Count/AHE (UE e5.1% p5%)

10:00 Eurozone CPI

14:00 US Housing/Home Price Indices

15:00 US Consumer Confidence(Feb)

15:00 Fed Chair Powell H-H Testimony to the Senate

17:30 BoC Governor Macklem speech


Wednesday February 24

As well as the Powell testimony, there are speeches today from Fed Brainard and Clarida.


00:30 Aus Wage Price Index

07:00 Germany GDP

15:00 Fed Chair Powell H-H Testimony to the House

15:00 US New Home Sales


Thursday February 25

EU leaders start a two-day (online) summit today to discuss COVID and their responses. Given that the EU is well behind many other countries, we might actually see some action. There is a press conference at 1700. Today is also the busiest day of the week for macro news.


00:00 EU leaders summit

07:00 Germany Gfk Consumer Confidence

10:00 Eurozone Consumer Confidence/Business Climate

10:45 ECB Lane speech

13:30 US Core PCE (QoQ)

13:30 US Jobless Claims

13:30 US Q4 Prelim GDP (e4.1% p4.0%)

13:30 US Durable/ND Capital Goods Orders (DG e1.1% p0.5%)

15:00 US Pending Home Sales (MoM)(Jan)

20:00 Fed Williams speech

23:30 Tokyo CPI

23:50 Japan Retail Sales/Ind Production


Friday February 26

The last trading day of the month may bring additional volatility, otherwise news is light.


00:00 EU leaders summit

13:30 US Core PCE (MoM and YoY)

14:45 Chicago PMI

15:00 Michigan CSI

Saturday, 15 August 2020

Week to Aug 14th

Bond yields rise all week, SPX misses ATH, Gold Rally reverses
MY CALL THIS WEEK : SELL GBPCAD


We have been saying for weeks that the action at the moment is not in equities and so it was proven this week, with indices consolidating, with the exception of NKY which followed the move down in JPY, and perhaps was attractive as a growth market, as SPX came close to new highs, fully erasing the COVID crash. Indeed the historically weaker DJIA was the best performer. The main news was a reversal in bonds, with yields rising all week, but particularly on Tuesday when a 6bp spike caused a notable fade in Gold (-5.4%) and Bitcoin (-4.23%). As we have also said before, the effect cannot be seen so easily in DXY itself, as the problems affecting the dollar are affecting other currencies as well. 

Next week’s scheduled news is routine again, but the earnings pause is over, and the retail sector reports this week, starting with WMT on Tuesday. The FOMC minutes are published on Wednesday, and all eyes will be on yields and Gold to determine whether the reversals are confirmed. Also, the Democratic National Convention starts on Monday, the official start of the campaign. (The GOP are next week). Joe Biden’s speeches will clearly be scrutinised both in style and substance.

Mon Aug 10
Today saw good news in that the President signed an executive order expanding COVID relief, but China tensions rose as Beijing sanctions 11 US senators and officials. The net result was a weak rally, with the rotation out of tech into industrials that we have seen recently. DJIA was up 1.3% whereas NDX was down 0.49%. Oil was up slightly, in line. The haven trio (Gold, Bonds and JPY) dipped very slightly, although this may have been driven by an uptick in DXY (+0.23%) continuing Friday’s reversal. It was all weak, with GBP and CAD outperforming.


Tuesday August 11
Sentiment was positive to open today, on news of a possible Russian vaccine. However later skepticism, and announcement from the Senate that there had been no progress on the latest COVID package prevented SPX from making a new all-time high (it reached 3380, 0.38% away) as markets tumbled sharply into the close. Again we saw industrial outperformance with NDX falling 1.3% more than DJIA. Oil fell in line. European markets closed earlier and were therefore up

The earlier rally finally broke the inexorable rise in Gold which tumbled 5.7%, its worst day for 7 years (Silver fell 15%, its worst day since the 2008 crisis), as yields rose 6%. The dollar was only slightly up, but JPY was the strongest currency of the day. NZD was particularly weak as coronavirus was detected after several weeks of no new cases.


Wednesday August 12
The mood was reversed today after the US CPI strong beat (double the figures expected). In a clear risk-on day, helped by dip buyers, NDX outperformed, up 2.1%, and SPX exceeded the Feb 19 closing all-time high, and came within 5.63 points (0.17%) of the intraday high of the same day. Oil was up 2.48%, and only JPY was down against a notably weaker dollar. Despite risk-on, yields advanced again and Gold was up, a bounce from Tuesday’s sharp sub-$2000 fall.


Thursday August 13
News today was a beat on Jobless Claims, but another day of stimulus deadlock. Another day of NDX outperformance saw the tech index slightly up and SPX and DJIA slightly down (so no new high) on what was generally a flat day, although European indices fell, notably FTSE on GBP performance following Wednesday’s GDP beat. Oil slipped slightly, and the dollar was directionless, with AUD, NZD, and JPY down, but EUR, GBP and CAD up. Gold continued its bounce back and yields continued to climb. This week, these assets are being driven by a longer-term trend as the dollar flattens.


Friday August 14
Poor Chinese Industrial Production and Retail Sales figures triggered a sell-off in the European morning, although this recovered in the US session, to produce the oft-seen pattern of recovery after the European close. FTSE was down sharply on another GBP rally (which came off, when London closed!). So US markets were flat overall, and closed another consolidating weekk. All US and European indices had larger daily moves than their total for the week. The dollar faded again, this time across the board, as the yields rally stalled, and Bonds were flat on the day. Gold also came off slightly, as did Oil.

WEEKLY PRICE MOVEMENTEuropean and US indices consolidated this week, but the picture was completely different on NKY which was our largest index mover, up 4.29%. The weakest currency was NZD and the strongest was CAD. Selling NZDCAD would have made 1.98%. Yet another week where ETH advanced but BTC was flatter than forex, and a very mixed performance from FANGs.

Selling NZDUSD for a second week paid off, making 1.05% and my running total 7.91% (28 weeks, 13 wins). I think GBP is probably overextended and CAD’s recent strength looks like it will go another week, so I will sell GBPCAD this week.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.

NEXT WEEK (all times are GMT)
(Calendar High volatility items are in bold)

  • DNC due to confirm Biden/Harris
  • Retail earnings phase
  • OpEx on Friday
  • UK, EU and Canada inflation

Monday August 17 
The Democratic National Convention starts today, where Joe Biden and Kamala Harris will be confirmed as candidates. Traders will be watching all week for signs of policy given that Biden is the front runner in the polls.

23:50 Japan Prelim Q2 GDP (e-7.6% p-0.6%) (Sun)
04:30 Japan Industrial Production (YoY)(Jun)


Tuesday August 18 
Retail earnings season opens today with DJIA components WMT and HD reporting before the bell. Like yesterday, macro news is thin.

01:30 RBA Meeting Minutes
08:00 Fed Brainard speech
12:30 US Housing Starts/Building Permits
23:50 Japan Imports/Exports/TB


Wednesday August 19 
A raft of inflation data today, and earnings from many SPX component retailers. Tech giant NVDA reports after the bell. Also important are the FOMC minutes from the last meeting.

06:00 UK CPI (YoY Jul e0.7% p0.6%)
06:30 UK CPI MoM
09:00 Eurozone CPI
12:30 Canada BoC CPI
18:00 FOMC Minutes


Thursday August 20 
A lot of low-level economic releases today, with Jobless Claims being the most important. Chinese giant BABA reports before the bell.

06:00 Germany PPI
06:00 Germany Gfk Consumer Confidence Survey
10:00 UK CBI Industrial Trends Survey – Orders
11:30 ECB MPC Minutes
12:30 US Jobless Claims
12:30 Philly Fed Mfr Survey (Aug)
16:00 BoC Beaudry speech
23:00 Aus Commonwealth Bank Prelim PMIs (Aug)
23:30 Japan National CPI


Friday August 21 
Today is August option expiration date, so additional volatility may be seen. European PMIs dominate the early day. Agricultural proxy DE reports before the bell.

06:00 UK Retail Sales
07:30 Germany Prelim Markit Mfr PMI (Aug e52.5 p51.0)
08:00 Eurozone Prelim Markit Composite PMI (Aug e54.7 p54.9))
08:30 UK Prelim Markit Svcs PMI (Aug e57.0 p56.5)
12:30 Canada Retail Sales (MoM Jun p24.5%)
13:45 US Markit Prelim PMIs (Aug)
14:00 US Existing Home Sales
14:00 Eurozone Prelim Consumer Confidence

Sunday, 24 March 2019

Week to Mar 22nd


Fed signal no more hikes in 2019, Still no Brexit resolution, Very bad week in Germany


 Mon Mar 18
US markets continued last week’s rally today, as did FTSE on the back of weaker sterling. The mood did not extend to NKY and DAX, which were flat. The dollar was generally flat (DXY +0.08%). There was none of the usual intermarket correlation. Gold and JPY (and EUR) were slightly up despite SPX gains. AUD was up, CAD was slightly down despite Oil rising, as was GBP. Yields fell slightly despite stronger equities.

Tuesday March 19
An early rally in SPX today fell off sharply on reports that China is pushing back on some US trade demands, with indices flattening off. Only DAX managed to stay green, after upbeat comments on the automotive sector (about 20% of the index) from BAML. The dollar had another flat and directionless day (DXY +0.12%), with a Turnaround Tuesday on most currencies, bonds and Oil. Only Gold and EUR moved in the same direction as Monday. This was despite decisive beats in UK AHE and unemployment (the latter the lowest since 1971) at 0930, and German ZEW Sentiment at 1000. It seems like everyone was waiting for the Fed.

Wednesday March 20
The big story today was the Fed minutes, with a hugely dovish move in the ‘dot-plot’ (the views of individual FOMC members) from two rate hikes in 2019 to zero. The reaction in USD was immediately, an instant 0.5% down, which is where it ended the day. All currencies, Gold and bonds (inverse to yields) were up with the exception of GBP, which was already down 0.75% on Brexit concerns that it still managed to close red on the day. The third parliamentary vote on Brexit was postponed. Oil was up sharply on the EIA beat at 1430.

US equities had been falling all day following a statement by President Trump that the US will most likely leave tariffs in place during negotiations to ensure “China lives by the deal”. They were given a small short-lived boost by the Fed announcement, but all ended red. DAX woes were compounded by a 13% drop in BAYN.DE (BAYRY) following a court judgment that Roundup weedkiller caused cancer, and 5.7% drop in BMW on a profits warning.

Thursday March 21
Stocks slid in the Asian and European markets, as did US futures, but on the cash open there was a classic risk-on surge with SPX adding 1.1% and the riskier NDX was 1.4% higher. It was clear that this was a reaction to the dovish Fed as financials (which benefit from high interest rates as they are lenders when everyone else is borrowers) were the only sector to fall. Other indices followed, except DAX, beleaguered with individual component problems, today it was DBK.DE (DB) and CBK.DE (CRZBY) opening 5% and 4% lower.

DXY recovered most of its Wednesday drop, and all currencies, Gold, Oil and bonds were down. However this was not even. Although EUR exactly retraced (as did AUD), the key instruments of JPY and bond yields only faded a little of the Fed move. It was a large further drop (0.57%) in GBP which evened out the basket. The BoE rate decision did not cause any notable move, selling was fairly even all day.

Friday March 22
In the European session today, DAX and EUR were hit hard by a surprisingly bad miss on the German Manufacturing PMI at 0830 (44.7 v 48.0 est). The German Bund yield went negative for the first time since October 2016.

The Eurozone equivalent print half an hour later was 47.6 vs 49.5 est. FTSE also fell as GBP recovered. Following that, US markets were sapped by the US 3-month bond yield rising above that of the benchmark 10-year note, as the latter hit a 14-month low of 2.418%. This inversion is considered to be a recession indicator and was last seen in August 2007, just before the massive equity pullback. The sell-off was strong, SPX down 1.9%, NDX down 2.5% and RUT losing 3.6%.

USD was generally back up again today, although Gold, JPY and bonds rallied in the risk-off conditions, and GBP bounced back from the Thursday low. The Canadian CPI beat
and Retail Sales miss at 1230 cancelled each other out. Oil 
gave up Wednesday’s gains in line with the equity fade.


WEEKLY PRICE MOVEMENT
The collapse of DAX after a string of issues for individual stocks such as Bayer, BMW and Wirecard made in the biggest index mover in a generally flat week for equities. For the third week, the biggest forex mover was GBPJPY, the best short two weeks ago, the best buy last week, and now the best short again. It was a second quiet week for cryptos, and FANGs were mixed, although generally outperforming NDX.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on UUP. The equity and index prices are now based on the cash close each day.


NEXT WEEK 
(all times are GMT)


(Calendar High volatility items are in bold)
  • Brexit endgame approaches
  • Large CB speaker roster
  • NZ rate decision
  • Final week of Q1/2019


Weekend News
The latest on Brexit is that the EU have offered to extend Friday’s deadline until May 22 if the deal is passed in Parliament this week, but only until Apr 12 if it isn’t. Weekend reports suggest no progress. In the US, Special Prosecutor Mueller is due to publish his report into Russian election meddling, but has already said there will be no further indictments. 


Monday March 25
USTR Lighthizer and TreasSec Mnuchin return to China this week to resume trade talks. Apple are holding a special product event, widely believed to be a new streaming service. There is another attempt by British MPs to take control of Brexit from the government. Fed Evans (centrist, 2019 voter) speaks today at 0145, followed by Harker (dove, 2020 voter) at 1000. Markets are closed in Greece and Colombia.

09:00 EUR Germany IFO Business Climate/Assessment/Expectations
12:30 USD Chicago Fed National Activity Index
17:00 AAPL Apple Product Event
20:30 AUD RBA Ellis speech
21:45 NZD NZ Imports/Exports/TB


Tuesday March 26
The third and final Brexit deal vote is planned for today, although weekend reports suggested it may be cancelled due to lack of support.

The Boao Forum opens in China today, with Premier Li Keqiang giving the opening remarks. Fed Harker (dove, 2020 voter) speaks at 1200 followed by Rosengren (hawk, 2019 voter). There are rate decisions on HUF (est 0.9% hold) and NGN.

07:00 EUR Germany Gfk Consumer Confidence Survey
12:30 USD US Housing Starts/Building Permits
13:00 USD US S&P/Case-Shiller Home Price Indices (YoY)
14:00 USD US Consumer Confidence
20:30 WTI API Oil Stock


Wednesday March 27
Senate Aviation Committee hearings on the Boeing 737-Max start today. The FAA and NTSB will testify. Traders will be listening to see if the RBNZ joins the dovish chorus. There are plenty of other CB speakers. RBA Asst Gov Kent speaks at 0010, and Fed George (hawk, 2019 voter) is on at 2130. From the ECB we have Chair Draghi (0800), Praet (0845), De Guindos (1045) and Mersch (1330). There is rate decision on KES.

01:00 NZD RBNZ Rate Decision/Statement (1.75% hold est)
09:40 EUR DE10 Bond Auction
12:30 USD US Trade Balance
12:30 CAD Canada International Merchandise Trade
14:30 WTI EIA Oil Stock


Thursday March 28
Today is the most important day in the week for data, with the final US GDP print for Q4, as well as PCE, the Fed’s preferred inflation indicator, and German inflation as well. Fed Quarles (centrist, 2019/2020 voter) speaks at 1115, followed by Williams (hawkish, 2019/2020 voter) at 1325 and Vice-Chair Clarida (centrist 2019/2020 voter) at 1330, and Bullard (dove, 2019 voter) at 2120. SNB Maechler is on at 1700. There are rate decisions, all expected to hold on CZK (1.75%), ZAR (6.75%) and MXN (8.25%).

In the British Parliament, today is the last day to pass the Brexit extension bill (short or long) as the House does not sit this Friday.

08:00 EUR ECB Pres Draghi speaks
10:00 EUR Eurozone Business Climate
12:30 USD US Jobless Claims
12:30 USD US 18Q4 GDP Final (est 2.4% prev 2.6%)
12:30 USD US PCE
13:00 EUR Germany CPI (est 1.6% prev 1.7%)
14:00 USD US Pending Home Sales (MoM)
21:45 NZD NZ Building Permits s.a. (MoM)
23:30 JPY Tokyo CPI (est 1.1% prev 1.1%)
23:30 JPY Japan Unemployment Rate
23:50 JPY Japan Retail Sales


Friday March 29
Today is the end of the week, month and quarter. In the UK, it is Brexit Day, unless an extension is granted and passed by Parliament, which seems almost certain. Taxi firm LYFT makes their IPO on the Nasdaq. Fed Quarles speaks again at 1645. A Moodys rating review is due in South Africa. There is a rate decision on CLP.

00:00 GBP Brexit Day - UK Initial Departure Day
00:01 GBP UK GfK Consumer Confidence
07:00 EUR Germany Retail Sales
08:55 EUR Germany Unemployment Rate/Change
09:30 GBP UK 18Q4 GDP Final
12:30 USD US Personal Income (MoM)
12:30 CAD Canada GDP Jan (MoM)
13:45 USD Chicago PMI
14:00 USD Michigan CS Index
14:00 USD US New Home Sales (MoM)
17:00 WTI Baker Hughes Rig Count


This report is published every week as an email by MatrixTrade.com - you can sign up to receive it here. This blog is supported solely by advertising, so if any of the ads interest you, please click on them. If you want notification when the blog is updated, please follow me on Twitter, Facebook, Stocktwits or Linkedin (all open in separate windows). Details of how I compile the report are here

Sunday, 14 October 2018

Week to Oct 12th


Monday October 08
The US stock market was open on Columbus Day, when concerns about the China trade war and Italian politics continued the downward slide in markets seen last week. The Chinese CSI300 had its worst day since February, and MIB fell 2.4% after the EC warned that Italy’s budget plans would break EU rules. All indices fell slightly, but with the US bond market closed, there was no direction for USD. DXY advanced very slightly (0.09%) with downward movements from Gold and all currencies except AUD and JPY, the latter reflecting risk-off mood. Oil was slightly up on the day.

Tuesday October 09
Unusually today, the worries switched back to the US. Italy’s bonds and stocks recovered, with MIB recovering 1.1%, leaving DAX flat on the day. FTSE and NKY were down slightly due to currency strength. The bond market re-opened and yields briefly touched a new seven-year high, SPX fell again, but was only down by 0.1% at the close after bonds finished 2bp down. Similarly, currency movements were muted with DXY flat (down 0.08%) on the day, and with no variations, every currency was very slightly up, as was Gold and Oil.

Wednesday October 10
The constant pressure from bond yields (Monday’s high was 3.248%) which are now nearly double the dividend yield of SPX (currently 1.89%) meant something had to give, and today indices fell hard. SPX fell 4%, in a near-marubozu red candle, and other indices followed suit. DAX was down 3.21%, FTSE a relatively mild 1.27% and NKY 3.46%. VIX rose 43%. USD also fell against EUR and GBP, the latter despite the GDP miss at 08:30. JPY was particularly strong, as would be expected, leaving DXY 0.23% down. However risk currencies AUD and CAD fell hard, as did Oil. As we pointed out a few weeks ago, Oil often falls in line with stocks, indicating reduced growth. Yields pulled back, but ended the day flat.

Thursday October 11
As often happens after sharp falls, there is a follow through day, and this is what happened today. All indices were down again, with SPX giving up  and falling below its 200-day moving average for only the second time since June 2016. The inflation miss at 12:30 did not help. Further downside was probably mitigated by a sharp pullback in yields, down 8bp on the day. Oil was down following the EIA stock miss at 15:30 and in line with stocks.

The follow-through happened with USD as well. DXY was down 0.45%, with all currencies advancing, particularly AUD, after Gold, somewhat late to the risk-off party, put in its best day in two years, adding 2.5% or $28.

Friday October 12
Earnings season starts in earnest today, and JPM, C and WFC reported before the bell. The first two beat on EPS but all three missed on revenue. Nevertheless, sentiment shifted and US indices recovered part of the previous two days losses. Foreign indices were still slightly down on the day (NKY was flat).It was still the worst week for indices since February, and in the case of RUT, the worst since Jan 2016.

DXY was quieter, adding 0.2%, gaining against all currencies except CAD, which advanced slightly, to be usual the least volatile, and the only currency to beat the dollar this week. The release of the US pastor in Turkey had a surprisingly muted effect on TRY, up only 0.73%. Oil was slightly up, and Gold gave $6 back of the previous day’s huge move.

Please note all figures and percentages given for daily movement on indices cover the entire cash and futures period in that day.


WEEKLY PRICE MOVEMENT

DXY retreated 0.4% this week, with all currencies except CAD advancing. JPY was the strongest, in the risk-off environment, so a CADJPY short would have been the best forex trade. Indices of course fell heavily (except NIFTY, which did it last week). Note that the foreign indices fell more than the US but if you take into account the currency movements (ie a DAX short is placed in euros), SPX was the best short. Cryptos resumed their downward trend, and again ETH suffered more than BTC. FAANG performance was uneven, with AAPL holding up well, and AMZN being the best short.

AUDUSD 0.7114 (+0.92%)
EURGBP 0.8800 (+0.22%)
EURUSD 1.1575 (+0.49%)
GBPUSD 1.3154 (+0.32%)
NZDUSD 0.6506 (+1.09%)
USDCAD 1.3041 (+0.80%)
USDJPY 112.21 (-1.31%)
DAX     11568 (-4.52%)
FTSE     6998 (-4.37%)
NIFTY   10358 (+0.41%)
NKY     22689 (-4.63%)
SPX    2768.8 (-4.22%)
GOLD  1216.60 (+1.11%)
OIL     71.49 (-3.70%)
BTCUSD   6292 (-5.24%)
ETHUSD 197.02 (-13.79%)
FB     153.74 (-2.28%)
AAPL   222.11 (-0.97%)
AMZN  1788.61 (-5.35%)
NFLX   339.56 (-3.36%)
GOOGL 1120.54 (-4.05%)

(Crypto prices are given as at 0000GMT Saturday, after the other markets close.)

NEXT WEEK (High volatility items are in bold)

Monday October 15
A US Treasury report is due today, the key takeaway of which is whether China will be branded a currency manipulator. Commentators don’t think it will happen, but if it does, expect Chinese stocks and CNY volatility. Also the Italian budget is presented to the EU, who are expected to reject it as incompatible with deficit rules. The bank earnings continue with BAC reporting before the bell, and of course we have US Retail Sales. The Bavarian election result is due, with a possible CSU loss of majority.

02:15 CNY China FDI (time approx)
12:30 USD US Retail Sales (Ex-autos est 0.3% prev 0.3%)
14:30 CAD BoC Business Outlook Survey
18:00 USD US Monthly Budget Statement (time approx)
21:45 NZD NZ CPI

Tuesday October 16
A big day of earnings with GS, JNJ and UNH (together 16.25% of DJIA) reporting before the bell, along with MS, and NFLX (1.8% of NDX) and IBM (3.77% of DJIA) reporting after the close. UK earnings are the big news release of the day. There is also a rate decision on HUF, hold expected.

01:30 AUD RBA Meeting's Minutes
01:30 CNY China CPI/PPI
08:30 GBP UK Average Earnings/Unemp/Claimant Change (Ex-bonus est 2.8% prev 2.9%)
09:00 EUR Germany Economic Sentiment/Current Situation
13:15 USD US Industrial Production/Capacity Utilisation
14:00 NZD NZ GDT Milk Index
20:30 WTI API Stock

Wednesday October 17
The EU Brexit summit today is focused on the Northern Ireland border issue, which has become the main sticking point in negotiations. Remember that the ruling Conservatives are only in power with the support of the Northern Irish DUP, who strongly oppose a hard border. Staying with the UK, yesterday’s earnings figure is followed by the inflation print. GBP could have a volatile day. The monthly FOMC minutes are of course important. The market current expects another 25bp in December, and is divided on March 2019. Trader will be looking for any language which varies this view.

00:00 EUR EU Brexit Summit (all day)
08:30 GBP UK CPI (Core est 1.8% prev 2.1%)
09:00 EUR Eurozone CPI (Core est 1.0% prev 0.9%)
12:30 USD US Housing Starts/Building Permits
18:00 USD FOMC Minutes
15:30 WTI EIA Stock
23:50 JPY Japan Imports/Exports/TB

Thursday October 18
Another day, another GBP print, but Retail Sales is less important, coming after CPI as the former is, in the end, a proxy for the latter. The Australian jobs report is important. The estimate is modest, and a beat may well add to the shaky recovery of AUD. ISRG (0.74% of NDX) report after the bell. There are rate decisions in CLP (hold expected) and KRW (25bp hike expected).

00:00 EUR EU Brexit Summit (all day)
00:30 AUD NAB Business Confidence (QoQ)
00:30 AUD NFP/Unemp/Participation Rate (NPF est 15k prev 44k)
08:30 GBP UK Retail Sales
12:30 USD Philly Fed Manufacturing Survey
13:00 USD Fed Bullard speech
23:30 JPY National CPI

Friday October 19
Attention turns to Canada today with the simultaneous inflation and Retail Sales reports. Now that NAFTA is concluded, these reports may start to have more significance. PG (2.12% of DJIA) reports before the bell. Today is OpEx day, so expect additional volatility.

02:00 CNY China Retail Sales/Industrial Production
02:00 CNY China GDP (YoY est 6.6% prev 6.7%)
04:30 JPY All Industry Activity Index (MoM)
06:35 JPY BoJ Kuroda Speech
08:30 GBP UK PSBR
12:30 CAD Canada CPI/Retail Sales (Core CPI est 1.8% prev 1.7%)
13:00 USD FOMC Kaplan Speech
14:00 USD Existing Home Sales (MoM)
17:00 WTI Baker Hughes Rig Count

This report is published every week as an email by MatrixTrade.com - you can sign up to receive it here.