Showing posts with label EURGBP. Show all posts

Sunday, 12 June 2022

Week to Jun 10th

CPI beat causes market plunge
MY CALL THIS WEEK : SELL EURGBP


LAST WEEK


In a week which started with some cagey, range-bound trading, Thursday’s session finally provided a decisive break lower in the main stock indices. The S&P 500 broke 4073 to signal the end of the sequence off the May low, and the DAX head and shoulders pattern gave a solid top signal.

Volatility increased after a hawkish ECB meeting pre-announced a 25bps hike in July and September, and surprisingly left the door open for the September hike to be upped to 50bps. The bank also revised inflation projections higher, and in a bizarre footnote to its statement, admitted the new projections were still too low as the May HICP inflation numbers came in higher than expected and they didn’t have time to re-calculate. Meanwhile, the White House pre-warned that inflation numbers due for release on Friday would be elevated due to the rally in oil and gas. And they weren’t wrong—CPI came in at 8.6%, the highest in 40 years. Barclays now expects a 75bps hike by the Fed next week.

Inflation shocks and central banks scrambling to get rates into neutral/restrictive territory continues to be the main theme and any pause in the Fed’s hiking cycle seems wishful thinking at this stage.  Friday’s print will break the 100-year downtrend in inflation and the worry is that central banks have lost control.

Yields keep pushing higher and are back near the yearly highs, as is DXY. Dollar pairs look quite similar to SPX and EURUSD et al have completed their first rally sequence higher from the May low and are now retracing that move.


WEEKLY PRICE MOVEMENT

The biggest index mover this week was NDX, down 5.70%. The top forex mover was for the third week USDJPY up 2.73%. Crypto had a relatively quiet week, moving no more than indices, and FANGs notably underperformed NDX as a whole.

The ECB was not hawkish enough, or more to point, USD rallied on the CPI print. Last week's EURUSD long lost 1.87%, which means I am ahead 3.71% this year, with 11/21 (52.4%) wins. This week I am selling EURGBP on the hope of a hawkish BoE.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.


NEXT WEEK

There are three rate decisions next week, from the UK, Japan and the all important Fed. The CME Fedwatch tool suggests a 92.5% chance of a 50bp hike (the 7.5% is all for 75bp), so all eyes will be on the statement and Chair Powell presser. The situation with the BoE is less clear, the official consensus is a hold, but there is a strong risk to the upside, which should benefit beleaguered GBP.

The Fed decision will affect equities, already approaching the May 20 low after the new multi-decade high inflation print on Friday caused a 3% sell-off, and the May LOY of 3810 is in sight.
It is also OpEx week, where we have historically seen a downtrend.


CALENDAR  (all times are GMT, volatile items in bold)

Monday June 13
06:00 UK GDP MoM
06:00 UK Ind/Mfr Production

Tuesday June 14
01:30 Aus House Price Index
04:30 Japan Ind Production
06:00 UK AHE/UnEmp (UnEmp e3.8% p3.7%)
06:00 Germany CPI (e7.8% p8.7%)
09:00 Germany ZEW Sentiment
12:30 US PPI

Wednesday June 15
00:30 Aus Westpac Consumer Confidence
02:00 China Retail Sales (e-6.1% p-11.1%)
09:00 Eurozone Ind Production
12:30 US Retail Sales (e0.2% p0.9%)
18:00 Fed Rate Decision/Statement (e1.5% p1.0%)
18:30 FOMC Press Conference
23:50 Japan Imports/Exports/TB

Thursday June 16
01:00 Aus Inflation Expectations
01:30 Aus Jobs/UnEmp (Unemp e3.9% p3.9%)
09:00 Eurozone Labor Cost
11:00 BoE Rate Decision/Statement (e1.00% hold)
12:30 US Building Permits/Housing Starts
12:30 US Jobless Claims
12:30 Philly Fed Mfr Survey

Friday June 17
03:00 BoJ Rate Decision/Statement (e-0.1% p-0.1%)
06:00 BoJ Press Conference
08:30 BoE Pill speech
08:30 BoE Tenreyro speech
09:00 Eurozone CPI
15:00 Fed Monetary Policy Report

Saturday, 12 February 2022

Week to Feb 11th

Highest #CPI for 40 years. Yields and Oil at multi-year highs
MY CALL THIS WEEK : BUY EURGBP


LAST WEEK


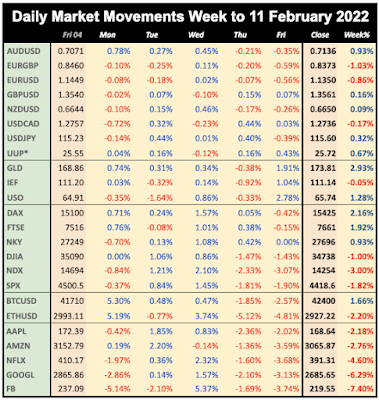
As is often the case, markets were progressing gently only to be hit by the worse than expected CPI print on Thursday, which at 7.5% was the highest for 40 years. Higher inflation implies earlier rate hikes, and Fed hawk Bullard said “I'd like to see 100 basis points in the bag by July 1." Indices pulled back with SPX closing an inside week, and rate-sensitive NDX down 3%. The effect was largely confined to the US, and DAX and FTSE were up on the week. Although the dollar briefly spiked on the CPI release, it quickly retraced and also had an inside week, although Gold was well up, making a 12-week and 2022 high. Oil reached $94, a six-year high, and yields crossed 2% for the first time since July 2019.


WEEKLY PRICE MOVEMENT

The biggest index mover was again NDX, down 3.0%. The top forex mover was EURAUD down 1.79%. Bitcoin and Ethereum were flat, and FANG suffered again, falling more than NDX in aggregate.

Last week's AUDNZD long position made 0.84%, which means I am ahead 3.31% this year, with 3/5 (60%) wins. This week I am buying EURGBP as I think it has bounced off the 0.83 bottom, but pulled back last week, making a good entry.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.


NEXT WEEK

Next week’s US data is light, only Retail Sales (which is not rising with inflation). The all-important inflation releases come from China (low), the UK and Canada (high but not as high as US). FOMC minutes probably the main US takeaway. Everything is about inflation. Earnings season enters the ‘retail’ phase when WMT report on Thursday.


CALENDAR  (all times are GMT, volatile items in bold)

Monday February 14
23:50 Japan Q4 Prelim GDP (QoQ e1.4% p-0.9%)

Tuesday February 15
00:30 RBA MPC Minutes
04:30 Japan Ind Production
07:00 UK Claimant Count/AHE/UnEmp (UnEmp e4.1% p4.1%)
10:00 Eurozone Q4 Prelim GDP (YoY e4.6% p4.6%)
10:00 Germany ZEW Sentiment Surveys
13:30 US PPI

Wednesday February 16
01:30 China CPI (e1.0% p1.5%)
07:00 UK CPI (e5.4% p5.4%)
10:00 Eurozone Ind Production
10:30 DE10Y Bond Auction (time approx.)
13:30 US Retail Sales (Control e0.1% p-3.1%)
13:30 Canada BoC CPI (e4.6% p4.0%)
18:30 BoC Lane speech
19:00 FOMC Minutes
23:50 Japan Imports/Exports/TB

Thursday February 17
00:30 Aus NFP/UnEmp (NFP e-15k p64.8k)
09:00 Eurozone Economic Bulletin
13:30 US Building Permits/Housing Starts
13:30 US Jobless Claims
13:30 Philly Fed Mfr Survey
23:30 Japan National CPI

Friday February 18
07:00 UK Retail Sales
13:30 Canada Retail Sales (e1.2% p0.7%)
15:00 Eurozone Consumer Confidence

Sunday, 14 November 2021

Week to Nov 12th

Inflation higher than expected, Strong Gold rally 
MY CALL THIS WEEK : SELL EURGBP
 

THIS WEEK


This week’s inevitable slide in equity markets was reversed after Wednesday’s strong inflation overshoot (core 4.6% vs est 4.3%, previously 4%), which created a V-shaped week, and sent Gold to five-month highs which were sustained.. The dollar and yields also rallied, pushing Oil down. All this showed the market thought rate hikes would come sooner, although surprisingly the Fed Futures rate did not move.


WEEKLY PRICE MOVEMENT


The biggest mover for a third week was NDX, down 0.97%. The top forex mover was NZDUSD this week, down 0.96%. Bitcoin and Ethereum were fairly flat, and FANGs were fairly flat except NFLX which reverted to mean.

Last week’s GBPNZD long made 0.42%, taking my year to date profit to 6.19% and 30/44 wins. This week I am selling EURGBP.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.


NEXT WEEK

Next week sees the retail phase of earnings, and as inflation is the hot topic, with retail sales and CPI from the UK and Canada, and more importantly US retail sales. Overall, the proximity to Thanksgiving and Black Friday is more likely to influence markets.


CALENDAR 
 (all times are GMT)

Monday November 15
23:50 Japan Q3 Prelim GDP (Sunday) (QoQ e-0.2% p0.5%)
04:30 Japan Ind Production
09:30 BoE Haskel speech

Tuesday November 16
00:30 RBA Meeting Minutes
02:30 RBA Governor Lowe speech
07:00 UK Claimant Count/AHE/UnEmp (UnEmp e4.5% unch.)
10:00 Eurozone GDP (e2.2% unch.)
13:30 US Retail Sales (MoM e0.7% unch.)
23:30 Aus Westpac Leading Index

Wednesday November 17
00:30 Aus Wage Price Index
07:00 UK CPI (p3.1%)
08:00 EU Financial Stability Review
13:30 US Building Permits/Housing Starts
13:30 Canada BoC CPI (p3.7%)
14:10 Fed Williams speech
17:40 Fed Waller speech
21:05 Fed Evans speech

Thursday November 18
10:00 Eurozone CPI
13:30 Philly Fed Mfr Survey
13:30 US Jobless Claims
14:30 Fed Williams speech
19:00 Fed Evans speech
23:30 Japan National CPI
23:50 Japan Imports/Exports/TB

Friday November 19
07:00 UK Retail Sales
07:00 Germany PPI
08:00 ECB President Lagarde speech
13:00 ECB Weidmann speech
13:30 Canada Retail Sales (MoM e2.0% p2.1%)
15:45 Fed Waller speech
17:15 Fed Clarida speech

Sunday, 31 October 2021

Week to Oct 29th

NDX ATH, ECB acknowledge inflation, volatile DXY
MY CALL THIS WEEK : BUY EURGBP


THIS WEEK 
(all times are GMT) 

In a week packed with central bank activity and US corporate earnings, new all-time highs were made in the SPX and DJI, and for the first time since 7th September, NDX finally caught up too with a new high. The Earnings season continues to be a positive driver, although a bad EPS miss by Amazon and in-line earnings from Apple and Facebook were punished. The FTSE also made new 2021 highs, as did oil before both faded lower again. But neither the DAX nor the (key) Russell made new highs … yet!

In the central bank race to tighten, the ECB caved in and admitted inflation was not as transitory as it had hoped, although no changes in policy decisions made. The BoJ were also unchanged while, in comparison, the BoC ended QE and signalled rate hikes in the near future.  This generally contributed to further bearish consolidation in bonds and partly explains why the Dollar was subject to increasing two way volatility which end up with EURUSD back down at its lows after an ECB inspired ramp. Currency volatility increased, with DXY and EURUSD both posting outside weeks, as did Oil, although Gold had an inside week.


WEEKLY PRICE MOVEMENT

The biggest mover this week was NDX, up 3.23%. The top forex mover was EURAUD this week, down 1.49%. Bitcoin was flat but ETH hit new highs, and FANGs were strong despite variable earnings.

Last week’s AUDNZD short lost 0.46%, taking my year to date profit to 3.77% and 28/42 wins. This week I am buying EURGBP.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.


NEXT WEEK (all times are GMT)

Although most major earnings have now been reported, the first week of November is busy as we enter the early part of the post Hallowe’en holiday season, traditionally a bullish sign.
The Fed, as always, dominates the week. A taper announcement is virtually inevitable as Fed Quarles confirmed on Oct 20 that the “substantial further progress” test had been met. The focus will now turn to rate hikes to combat inflation. The BoE have been equally bullish recently. Their strategy is that rate hikes are not necessarily preceded by taper. As no adjustment is expected this week, Gov Bailey’s words will be scrutinised closely. There is also a rate decision in Australia, which has now caught up with vaccinations, and is also seeing inflation above 2%.

As if that was not enough, we also have NFP, with a relatively modest estimate of 385k (vs 369k on ADP). Given the order of business this week, the ‘bad is good’ factor is removed, and markets are expected to initially react the logical way, although given the Fed timing, the effect may not be as strong as in previous months.


CALENDAR (all times are GMT)

Monday November 1
01:45 China Caixin Mfr PMI
07:00 Germany Retail Sales (p0.4%)
09:30 UK Markit Mfr PMI
14:00 US ISM Mfr PMI (e60.41 p61.1)
14:30 Canada Markit Mfr PMI
14:45 US Markit Mfr PMI
23:50 BoJ MPC Minutes

Tuesday November 2
00:30 Aus TD Securities Inflation (time approx.)
03:30 RBA Rate Decision/Statement (e0.1% hold)
05:50 RBA Debelle speech
08:55 Germany Markit Mfr PMI
21:30 Aus AiG Performance of Construction Index
22:00 Aus Commonwealth Bank Svcs PMI

Wednesday November 3
00:30 Aus Building Permits
01:45 China Caixin Svcs PMI
09:00 Eurozone Unemployment Rate
12:15 US ADP Employment Change (e369k p568k)
13:45 US Markit Svcs & Comp PMI
14:00 US ISM Services PMI (e61.5 p61.9)
14:00 US Factory Orders (MoM)(Sep)
18:00 Fed Rate Decision/Statement (e0.25% hold)
18:30 FOMC Press Conference

Thursday November 4
00:30 Aus Trade Balance (e1.03B p1.50B)
07:00 Germany Factory Orders
08:55 Germany Markit PMI Composite
09:00 Eurozone Economic Growth Forecasts
09:00 Eurozone Markit Comp PMI
12:00 BoE Rate Decision/Statement (e0.1% hold)
12:30 BoE Governor Bailey speech
12:30 US Trade Balance
12:30 US Productivity/Labor Costs
12:30 US Jobless Claims
12:30 Canada Trade Balance
23:30 Japan Overall Household Spending

Friday November 5
00:30 RBA MPC Statement
07:00 Germany Industrial Production
10:00 Eurozone Retail Sales (p0%)
12:30 US NFP/AHE/UnEmp (NFP e385k p194k)
12:30 Canada NFP/AHE/UnEmp (NFP e65k p157.1k)
14:00 Canada Ivey PMI


Saturday, 10 July 2021

Week to Jul 9th

Marginal ATHs after dip, Dollar rally falters, Gold/Oil up

MY CALL THIS WEEK : SELL EURGBP


LAST WEEK

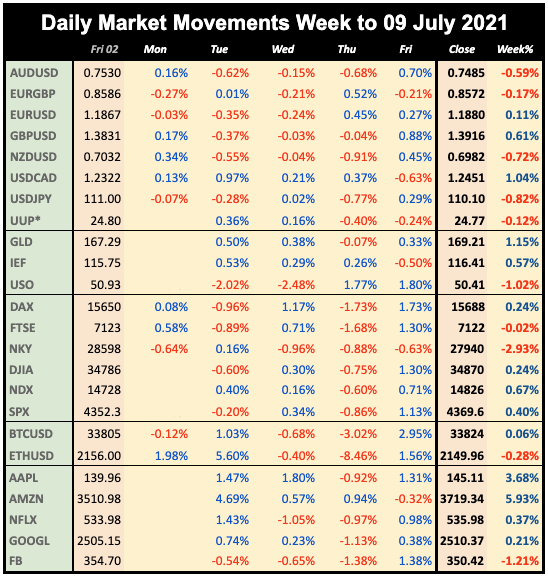
The four-day week saw stocks continued to consolidate, with a noticeable dip on Thursday, which recovered firmly on Friday, to close the week very slightly up (DJIA +0.24%, NDX +0.67%), with new SPX and NDX ATHs. The Thursday dip was influenced by falling 10-year yields, which touched February lows this week, and the ISM miss on Tuesday, but the trigger was probably the speech by Fed Bostic, who gave a very hawkish speech on Wednesday evening, saying “delaying rate rises might cause … instability”. Oil briefly touched its 2018 high on continuing OPEC uncertainty, but then pulled back from an oversold condition. The dollar had an inverted V-shaped week, slightly leading the V-shaped yield pattern. In line with the fragility of sentiment, this was largely euro and sterling strength, the latter bouncing off a three month low. Other currencies were weaker, and gold outperformed, hitting a three-week high.


WEEKLY PRICE MOVEMENT


The biggest mover this week was NKY, down 2.93% in contrast with other markets. The top forex mover was CADJPY down 1.86%. Crypto was very flat this week, with BTC probably having its flattest week for years. FANGS again outperformed NDX.


My NZDJPY short worked, making 1.25%, one of my best this year, taking my year to date profit to 4.63% and 20/26 wins. This week I am shorting EURGBP.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.


NEXT WEEK (all times are GMT)

(Calendar High volatility items are in bold)


Earnings season for Q2 opens this week as always with the banks first, with EPS estimates notably lower than Q1. JPM (e3.09 p4.50) and GS (e9.41 p18.60) report Tuesday, and BAC (e.077 p0.86), WFC (e0.93 p1.05) and C (e2.01 p3.62) the day afterwards. Fed Chair Powell gives his biannual ‘Humphrey-Hawkins’ testimony to Congress. He may address the gap between stronger inflation and falling bond yields. The macro schedule is packed, with rate decisions in Canada, Japan and New Zealand, inflation from the US, UK, Eurozone and Germany. The key US print, with MoM estimated as slightly lower than last month, which may support the view that the COVID rebound figure last month was transitory. Finally, China is first out of the gate with Q2 GDP, a modest 1.3% QoQ growth is expected. Markets are closed in France for La Quatorze Juillet.


CALENDAR


Monday July 12

12:10 ECB President Lagarde speech (Sunday)

13:20 Fed Quarles speech (Sunday)

02:00 China FDI (time approx.)


Tuesday July 13

01:00 Aus HIA New Home Sales (time approx.)

02:00 China Imports/Exports/RB (time approx.)

06:00 UK Financial Stability Report

06:00 Germany CPI (e2.2% p2.1%)

12:30 US CPI (Core MoM e0.5% p0.7%) 

18:00 US Monthly Budget Statement


Wednesday July 14

00:30 Aus Westpac Consumer Confidence

04:30 Japan Industrial Production

06:00 UK CPI (e2.2% p2.1%)

09:00 Eurozone Industrial Production

10:30 DE10Y Auction (time approx.)

12:30 US PPI

14:00 BoC Rate Decision/Statement (e0.25% hold)

15:15 BoC Press Conference

16:00 Fed Chair Powell H-H House Testimony

18:00 Fed Beige Book


Thursday July 15

01:00 Aus Consumer Inflation Expectations

01:30 Aus Jobs/UnEmp (Empfehlen e30k p115.2k)

02:00 China Q2 GDP (QoQ e1.3% p0.6%)

02:00 China Retail Sales (YoY e11.0% p12.4%)

06:00 UK AHE/UnEmp (UnEmp e4.7% p4.7%)

12:30 Philly Fed Mfr Survey

12:30 US Jobless Claims

13:30 Fed Chair Powell H-H Senate Testimony


Friday July 16

03:00 BoJ Rate Decision/Statement (e-0.1% hold)

06:00 BoJ Press Conference

09:00 Eurozone CPI

12:30 US Retail Sales (MoM e-0.6% p-1.3%)

14:00 Michigan CSI (e87.0 p85.5)

Monday, 12 April 2021

Week to Apr 9th

ISM Services PMI beat, Further all time highs, Dovish Fed
MY CALL THIS WEEK : SELL EURGBP


A strong US Services PMI beat started another positive week as stocks drifted up, helped by dovish FOMC minutes. It was moderate but solid risk-on, with NDX outperforming and DXY declining smoothly all week, helping Gold. SPX and DJI, unlike RUT and NDX posted new all-time highs, as did DAX and the MCSI World Index. Yields ranged finishing down but in last week’s range, as did Oil.


Next week is the start of earnings season, with JPM, C and GS leading the way as always. In practice surprises are unlikely, but with markets at elevated levels, the risks are to the downside. Before earnings comes US inflation on Tuesday. The estimate is up on the last month, and a beat could cause taper concerns.


Mon Apr 5

Friday’s rally continued with even further vigor today helped by the ISM Services PMI beat. SPX was up 1.44% and NDX even further. Europe was closed but DAX futures hit an all-time high The safe haven dollar was down. Yields were slightly down, and surprisingly so was Oil. Gold was flat on the day.


Tuesday April 6

US market were slightly off today, rotating into Europe to post an ATH for SX5E, the first since the pre-pandemic high over a year ago. Of the major indices, only FTSE is still below the Feb 2020 level. The dollar fell again, pushing Gold up. Bonds were also up, and Oil recovered somewhat.


Wednesday April 7

A flat day throughout asset class land, with equities, gold, oil and the dollar, although both all showed a slight blip upwards after the dovish FOMC minutes. FTSE advanced on a weaker dollar, but both DAX and SX5E retreated.


Thursday April 8

The Fed message had more effect today, with another rally across the board. DAX and now the MCSI World Index posted all-time highs. The dollar duly fell pushing Gold up again, and yields down. Oil was flat on the day.


Friday April 9

In a move similar to the previous Friday, markets rallied hard into the close, with for once, DJIA outperforming NDX, after four days of tech outperformance, and posting a new ATH, as did the MSCI World. The dollar reversed up after declining all week. Gold, bonds and Oil were all down.


WEEKLY PRICE MOVEMENT


A week of rotation back into NDX made it the top index, up 3.87%. The top forex pair was EURGBP up 1.95%. Cryptos were fairly flat (by their standards, ie under 5%), and FANG again outperformed NDX as a whole.


My strategy of the most extreme pair last week worked, but hardly at all, up 0.03%, taking the total to -1.03% 9/13 wins. I will try it again and sell EURGBP hoping for a reversion to mean.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.


NEXT WEEK (all times are GMT)

(Calendar High volatility items are in bold)

  • Q1 Earnings season opens
  • US inflation expected to rise
  • Early Chinese GDP
  • US Retail Sales, German inflation


Monday April 12

As is often the case, a quiet Monday with no US releases.


09:00 Eurozone Retail Sales (YoY e-5.7% p-6.4%)

14:30 BoC Business Outlook Survey

17:00 Fed Rosengren speech

18:00 US Monthly Budget Statement(Mar)


Tuesday April 13

The US inflation reports dominates today, too high and it might worry traders that the Fed may tighten policy.


02:00 China Imports/Exports/TB

06:00 UK Mfr/Ind Production

06:00 UK GDP

08:00 UK NIESR GDP Estimate (time approx.)

09:00 Eurozone ZEW Economic Sentiment

09:00 Germany ZEW Economic Sentiment

10:30 DE10Y Bond Auction (time approx.)

12:30 US CPI (YoY e1.6% p1.3%)


Wednesday April 14

Earnings season opens today, as usual with JPM first out of the gate. WFC and GS also report today. Markets are closed in India.


00:30 Aus Westpac Consumer Confidence(Apr)

01:00 RBNZ Rate Decision/Statement (e0.25% hold)

09:00 Eurozone Industrial Production s.a. (MoM)(Feb)

18:00 Fed Beige Book

18:30 Fed Williams speech


Thursday April 15

The second day of earnings season has BAC, C and top Dow component UNH (7.32%). Today would normally be US Tax Day, but this year the filing deadline has been extended to May 17. There are rate decisions in S.Korea and Turkey.


01:00 Aus Consumer Inflation Expectations(Apr)

01:30 Aus NFP/UnEmp (NFP e35k p88.7k)

06:00 Germany CPI (e2% p2%)

12:30 US Retail Sales (Control Group e-0.9% p-3.5%)

12:30 Philly Fed Mfr Survey(Apr)

12:30 US Jobless Claims(Apr 9)


Friday April 16

There are Eurogroup and EcoFin meetings all day today.


02:00 China Q1 GDP (YoY e18.6% p6.5%) 

02:00 China Retail Sales/Industrial Production

09:00 Eurozone CPI

12:30 US Building Permits/Housing Starts

14:00 Michigan CSI (e88.9 p84.9)


Sunday, 28 February 2021

Week to Feb 26th

Markets pull back, Powell Humphrey-Hawkins testimony, Bonds and Gold also collapse
MY CALL THIS WEEK : BUY EURGBP


In a week that saw nothing surprising in the news, ie no changes in the stimulus plan, the vaccine rollout or The Fed’s stance, as expounded in the Humphrey-Hawkins testimony from Chair Powell, we got a chance to see underlying sentiment.


It is easy to believe the market is bullish, as Gold, bonds and JPY made new five-month lows this week. However, there was a clear underperformance in NDX this week, which never improved on its opening gap down and DJI which actually made new highs. The danger is that the pullbacks in the last couple of weeks may mean investors are moving to cash, perhaps expecting a ’no hiding place’ pullback, a general collapse in sentiment across all asset classes, reminiscent of March 20, and unlike Q4/18, where conventional havens were available. It does of course also mean with uninvested cash, the recovery from the correction will be swift. The problem with trying to interpret haven assets in March 20 is that equities fell first.


This week saw USD move up suddenly, but not buy much and well within the 89.20-91.60 (2.7%) range it has run all year. Note that moves to dollar cash from dollar instruments (such as ETFs), the majority of transactions, do not of course affect the dollar itself. The V-shaped (or inverted) charts for the currency and foreign indices confirm this consolidation.


Mon Feb 22

Markets fell today, as the pullback continued. The general feeling was that this is the start of a correction after the election to January rally, and NDX fell further than SPX, although FANG, in general didn’t fall as far as NDX in general. USD was down across the board meaning Gold was up 1.50%. The equity pullback did not affect Oil which continued this week’s rally making a new 13-month closing high. Unusually, bonds were also slightly up on the day.


Tue Feb 23

Today was a wild ride, with NDX down as much as 3.9% at one point, before recovering most of the drop. SPX followed a similar path and ended 0.13% up. All part of a correction. The dollar was surprisingly quiet, flat with little volatility. Gold was similarly flat. Bonds were up and Oil was down in line with risk-off mood.


Wednesday February 24

Chair Powell today reiterated his dovish stance in the Humphrey-Hawkins testimony, and markets rose late in the day after falling at the open. Bonds followed stocks inversely, ie the yield chart looks much like the SPX chart. The dollar was flat overall, but this was composed of a general upward dollar (hence Gold down) but a notable strong rise in JPY, showing the markets are far from risk-on. Oil continued its rise.


Thursday February 25

The general mood we have seen all week and elevated prices trigged a sharp fall today with SPX down 2.5% and NDX losing 3.5% its worst day since October. The bond market also sold off with yields hitting a new 12m high of 1.6140%, in fact almost synchronously with equities, so not a flight from risk to fixed income, a flight to cash, as Gold also fell, and even Oil was only flat.


Friday February 26

There was some recovery today from yesterday’s sharp sell-off, with bond yields down 10bp and NDX up 0.6%, although DJIA and SPX were down. Much more action on USD which was sharply up following a sharp reverse in bond yields, down 10bp on the day. Gold was sharply down on the rising dollar, and Oil pulled back on the weaker equity position.


WEEKLY PRICE MOVEMENT

A second week of pullback, with NDX the biggest loser, down 4.94%. The largest forex mover was AUDUSD down 2.09% Cryptos continued to fall sharply after their super-rally, and FANGs broadly followed NDX down.


I was.a week too early last week with my AUDUSD sell. I made 0.34% on my EURGBP taking my total this year to a measly 0.58% with 6/8 wins. I will learn from my AUD mistake, and buy EURGBP again.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.


NEXT WEEK (all times are GMT)

(Calendar High volatility items are in bold)


  • New Month
  • Trend is down
  • RBA Rate Decision
  • Canada, Australia GDP

Mon Mar 1

A new month with five Markit Manufacturing PMIs, speeches from Fed Williams and Brainard, and ECB De Guindos, and President Lagarde at 1610, although this is only a pre-recorded event for German SMEs.


00:00 Aus TD Securities Inflation

01:45 China Caixin Mfr PMI(Feb)

08:55 Germany Markit Mfr PMI(Feb)

09:30 UK Markit Mfr PMI(Feb)

13:00 Germany CPI (e1.6% p1.6%)

13:30 Canada Current Account(Q4)

14:30 Canada Markit Mfr PMI(Feb)

14:45 US Markit Mfr PMI(Feb)

15:00 ISM Mfr PMI (e58.9 p58.7)

23:30 Japan Jobs/Unemployment Rate(Jan)


Tue Mar 2

Another heavy data day, and CB speeches from ECB Panetta and Fed Brainard again.


03:30 RBA Rate Decision/Statement (e0.1% hold)

07:00 Germany Retail Sales (YoY e5.0% p1.5%)

08:55 Germany Unemployment Rate/Change(Jan)

10:00 Eurozone CPI (Core YoY e1.1% p1.4%)

13:30 Canada Q4 GDP Final (QoQ e47.6% p40.5%) 

22:00 Aus Commonwealth Bank Svcs PMI(Feb)


Wednesday March 3

The data keeps on coming. Four ECB speeches today: Weidmann, Panetta, De Guindos and Schabel.


00:30 Australia Q4 GDP Final (QoQ e2.5% p3.3%)

01:45 China Caixin Svcs PMI(Feb)

08:55 Germany Markit PMI Composite(Feb)

09:00 Eurozone Markit PMI Composite(Feb)

13:15 US ADP Employment Change (e168k p174k)

14:45 US Markit Svcs PMI(Feb)

14:45 US Markit PMI Composite(Feb)

15:00 ISM Svcs PMI (e58.7 p58.7)

19:00 Fed Beige Book


Thursday March 4

Key today is the US Initial and Continuing Jobless Claims. Chair Powell speaks at the Wall Street Journal Jobs Summit.


00:30 Aus Imports/Exports/TB (TB e6.5B, p6.78B)

00:30 Aus Retail Sales (MoM e0.6%, p0.6%)

09:00 Eurozone Economic Bulletin

10:00 Eurozone Retail Sales (YoY e-1.3%, p0.6%)

10:00 Eurozone Unemployment Rate(Jan)

13:30 US Jobless Claims

15:00 US Factory Orders (MoM)(Jan)

17:05 Fed Chair Powell speech


Friday March 5

First Friday so it’s NFP day with little else on the calendar.


07:00 Germany Factory Orders s.a. (MoM)(Jan)

13:30 US NFP/AHE/UnEmp (NFP e148k p49k)

13:30 US Trade Balance(Jan)

15:00 Canada Ivey PMI