Showing posts with label vaccine. Show all posts

Monday, 3 January 2022

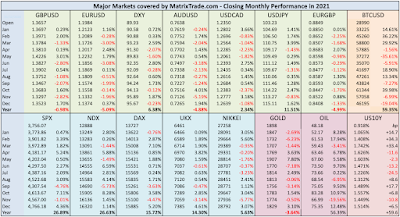
Review of 2021

Year of the Vaccine and recovery, First year of Biden, and hints of tightening.


The first full year of the Biden presidency, and of the COVID vaccine program was generally positive, with SPX and NDX both up just over 25%. Notably SPX outperformed NDX for the first time since 2016. There was notable two-way DJI/NDX divergence this year, as the industrial index reacted to COVID, and tech stocks reacted to taper. Foreign indices did better than last year. The dollar recovered last year's losses, as did Oil. Gold was flat on the year, after a 25% rise in 2020. Yields were up 60bp after falling 100bp last year. COVID still dominated everything, and other world events were notably subdued. The most notable factor of the year was the return of inflation, although equally notable. There were no big dips this year in equities.


January 2021
The Capitol riots, and a weak NFP kicked off a weak month, with SPX unable to rise at all. NDX did a little better as it had done throughout the pandemic. The vaccine rollout started in earnest as Joe Biden was inaugurated as the 46th president. The "meme stock" phenomenon started with GME rising from $17 to $482 in a few days, only to pull straight back. Foreign markets were down, as was Gold, whereas Oil rose and yields were up above 1% for the first time since the pandemic.


February 2021

President Biden's commitment to mass vaccination rallied markets, with SPX rallying above and beyond the relatively COVID-immune NDX. Gold fell 6.23% its worst month since November 2016, against a flat dollar. Oil was particularly strong, and yields were up.


March 2021

March saw the worst equity pullback if the year, (although mild by previous years, SPX down 5.21%, DJI 6.62%), after Janet Yellen made hawkish remarks, and the Fed did nothing dovish. The dollar was up 2.59%, its best week since 2016, on tightening fears. Bitcoin surpassed $60,000 for the first time. Gold was down, reacting to the dollar rather than risk, and yields had their best month of the year.


April 2021

A strong earnings season, a blowout 916k NFP, the lowest jobless claims since the pandemic started, and continued rollout of vaccine meant a recovery in equity and oil markets. Bitcoin hit a new ATH of $65k. The dollar pulled back after three months of gains, and Gold recovered, against reacting to the dollar. The turn also affected yields, which turned down for the first time in the year.


May 2021

Sentiment changes this time of year, and with the appearance of the more virulent Indian variant (later called the delta variant), markets were subdued, with SPX flat and NDX slightly down. Another meme stock, AMC, rose 500%, although like GME, never recovered its first high. The dollar was down again, which in addition to the mood gave Gold its best month of the year, and another fall in yields. Oil carried on rising.


June 2021

June saw the G7 meeting agreeing a minimum 15% global corporation tax, which should have depressed the market, but it seems that the only things that matters in 2021 were COVID and QE. NFP was 'Goldilocks', not too high to trigger taper fears, but high enough to shoe recovery. Even the inflation print, a thirteen-year high, and a hawkish Fed did not prevent modest SPX gains, NDX outperformance, and Oil up nearly 10%. The dollar rose in line with the Fed and Gold consequently had its worst month of the year. However yields fell again, running to a different timetable.


July 2021

Another good NFP (850k) and quality earnings kept markets moderately buoyant through July, as traders focus moved away from COVID and towards inflation which the Fed declared to be 'transitory' for now. There were definite pullbacks but these only lasted days and were not deep. Oil rallied as OPEC failed to raise production. Currencies, Gold and oil were flatter than usual, although in the absence of anything hawkish from the Fed, yields fell 24.5bp. 


August 2021

Another great NFP (943k) kept markets (although not Oil) buoyant, with the NDX/DJI making a six-month high. Congress passed the $1Trn infrastructure bill. However gains were trimmed later in the month, when FOMC minutes confirmed taper was on the agenda, and Chair Powell at (virtual) Jackson Hole saying inflation was no longer regarded as transitory. The dollar hit a 9-month high, and yields were back up again. The end of the US 20-year war in Afghanistan had little effect on markets.


September 2021

Concern about taper and the Chinese Evergrande crisis led to a sharp pullback this month (SPX -4.76%) This was expressed very firmly on the massively unexpected Retail Sales print (+2.5% vs -0.1% estimate) which resulted in an instant 0.4% move up in DXY, and 1.73% gain on the month. Notably NKY rallied this month, but admittedly after five months of decline. Gold was down with the dollar move, and Oil down with equities. Yields were sharply up in line with the Retail Sales print's implication of inflation to come. FB, which had been at all-time highs was 10% down after the WSJ published a whistleblower's account of the company's disregard of public safety.


October 2021

With a low NFP print of 194k, October started badly but strong earnings recovered Septembers losses and more, despite continued hawkish views from the Fed. In fact, SPX and NDX had their best months of the year, and Oil was up 10% in line, with no particular reason except the time of year, and perhaps the continuing vaccine program and general recovery. The dollar was flat, as was Gold.  FB dropped 5% after a one-day outage, but this was recovered a week later. Inevitably the dollar rallied, hitting a 16-month high. Gold was flat.


November 2021

The rally was halted with another poor month for SPX (-1.01%) on the outbreak of the much more transmissible but, it turned out later, less serious omicron variants of COVID. The long-expected taper timetable announcement was actually seen as positive, removing uncertainty, and mitigated the drop. NDX managed to stay green despite the 31-year high CPI print of 6.2% (which came after the Fed announcement), and the NDX/DJI ratio reached its highest level since 2000. The dollar was of course up, again with flat Gold, but Oil followed omicron and fell nearly 20%. Notably Bitcoin hit a new ATH at $69k. Yields were down.


December 2021

Despite another low NFP, the year finished nicely with a traditional Santa Rally across US and international markets, all reaching 2021 and in many cases all-time highs as omicron fears faded. The dollar was slightly down, producing a small rise in Gold. Oil rallied over 10% and yields recovered slightly.


Sunday, 9 May 2021

Week to May 9th

NFP shock miss, Biden suggests vaccine patent waiver, Yellen remarks on inflation
MY CALL THIS WEEK : BUY GBPCAD


In a week that saw President Biden float the idea of revoking or limiting vaccine producers’ patents, and a large NFP surprise (266k vs 978k est) to the downside, delaying QE taper, the net result was new ATHs for DJIA and SPX, and the strongest rotation out of tech for nine weeks. Vaccine shares were, unsurprisingly, hit particularly hard. Sell in May may have been the cause of Tuesday’s pullback, the worst since March, but it didn’t last.


The safe haven dollar also hit a nine-week low, giving Gold its best week since November. Oil was up in line with the dollar and Dow. Bonds were slightly up on the week.


Next week should see further fallout from the NFP shock. The key macro report is US inflation on Wednesday, with a core estimate of 2.3%, well ahead of 1.6% and over the Fed target. A match or beat at this level may be taken as a pointer to QE taper. Earnings are quiet, with only DIS and BABA of note reporting.  


Mon May 3

Today saw what we can now call A vaccine rally, with a 1.14% variance in DJIA (+0.70%) and NDX (-0.44%), based on recovery hopes, reversing Friday’s fall. USD also reversed Friday’s rally, pushing Gold and Oil up, the latter also in line with stocks, particularly industrial stocks. Bonds were also up.


Tue May 4

A remark from TreasSec Yellen that “interest rates might need to rise” was enough to cause a sharp pullback, the worst since Mar 18th. NDX was down a huge 1.85% (AAPL down 3%), although DJIA managed to stay flat, more evidence of rotation. It was Turnaround Tuesday for currencies and Gold as the dollar reversed back up. Bonds were up in line. However, Oil continued to rise.


Wednesday May 5

Today was eventful. Janet Yellen clarified her remarks saying she did not foresee “an inflationary problem”.  Markets recovered. Meanwhile President Biden mentioned possibly waiving the patents on the vaccine drugs, causing an immediate sharp fall in MRNA, BNTX and other producers. Finally, the ADP report missed, but still showed a healthy improvement on last month. The net result was a positive day for DJIA, negative for NDX. The dollar  fell and Gold rose in line with equities. However bonds were up again. Oil reverses down, losing Tuesday’s gains.


Thursday May 6

Markets were flat most of Thursday, looking for direction after Wednesdays various news, and by the end of the day, took the positive view, and rallied strongly into the close. The dollar fell again, pushing Gold up. Oil carried on down. Bonds were flat. There was no change at the BoE, and GBP hardly moved.


Friday May 7

Markets had been expecting a substantial NFP, at least as much as the ADP print, so the actual print of 266k was a big miss. Markets saw this as “bad is good”, ie delaying QE taper, and rose sharply on the open, staying up all day, with new ATHs on SPX and DJIA. For the same reason, the dollar fell even more sharply than in previous days. CAD closed at 1.2132, its lowest close for six years. Bonds spiked up on the NFP print, but immediately fell again. Oil completed an inverse-V shaped week.


WEEKLY PRICE MOVEMENT

A breakout week with DJIA the best performer at 2.67%, and NDX the worst at -1.02%. The top forex mover was NZDUSD up 1.62%. ETH surged ahead of a flat BTC. In the last four weeks ETH has outperformed BTC by 86%! FANG stocks in general underperformed NDX, with AMZN particularly down as the ‘COVID trade’ unwinds.


After five weeks of wins, I got CADJPY wrong, it went up, and I lost 0.65%, making my running total 12/17, but sadly a -1.23% running loss.vWith USDCAD at a six-year low, I will take a chance on it reversing. GBP looks like the strongest at the moment, so I will buy GBPCAD, which is at/near support. 


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.


NEXT WEEK (all times are GMT)

(Calendar High volatility items are in bold)


  • US Chinese and German inflation
  • US and Australia Retail Sales
  • Various CB speeches
  • DIS and BABA earnings


Monday May 10

As is often the case, a quiet Monday.


01:30 Australia Retail Sales (e1.4% p1.4%)

23:30 Japan Overall Household Spending


Tuesday May 11

ZEW sentiment may reflect EU citizens view of their governments’ vaccine programmes. There is a Treasury auction of $58Bn of 3-year notes today.


01:30 China CPI (YoY e1.0% p0.4%)

09:00 Eurozone ZEW Economic Sentiment

09:00 Germany ZEW Economic Sentiment

14:30 Fed Williams speech

14:30 BoE Governor Bailey speech


Wednesday May 12

The most important print of the week is US inflation today. The estimate is above the Fed target, and if this is matched or beaten, we could see a stocks reversal, anticipating taper. The Treasury auction $41Bn of the bellwether 10-year note today. There is a rate decision in Romania.


00:30 Aus Westpac Consumer Confidence

05:00 Japan Leading Economic Index

06:00 UK Mfr/Ind Production

06:00 UK Q1 Prelim GDP (e0.5% p1.3%)

06:00 Germany CPI (e2.1% p2.1%)

09:00 BoE Governor Bailey speech

09:00 Eurozone Ind Production

10:00 UK NIESR GDP Estimate (time approx.)

12:30 US CPI (Core YoY e2.3% p1.6%)

13:00 Fed Clarida speech

18:00 US Monthly Budget Statement(Apr)

23:50 Japan Current Account


Thursday May 13

There is a $27Bn auction of 30-year paper today. Chinese giant BABA and Dow stalwart DIS report today. There is a rate decision in Mexico.


01:00 Aus Consumer Inflation Expectations

12:00 BoE Cunliffe speech

12:30 US PPI

12:30 US Jobless Claims

15:00 BoC Governor Macklem speech

16:00 BoE Governor Bailey speech


Friday May 14

Retail Sales has less ‘bite’ than CPI as an inflationary measure but in the event of an inconclusive CPI, may have some effect, especially on a strong beat.


10:30 DE10Y Bond Auction (time approx.)

11:30 ECB MPC Minutes

12:30 US Retail Sales (Apr Control Group e0.8% p6.9%)

14:00 Michigan CSI (May Prel e89.5 p88.3)

Sunday, 29 November 2020

Week to Nov 29th

Thanksgiving short week, AZ/Oxford third vaccine, Trump concedes transition
MY CALL THIS WEEK : BUY GBPJPY


Another Monday, another vaccine announcement, this week with AZ and Oxford University announcing their results. Also, the Trump administration conceded some ground, and started facilitating the Biden transition. Coupled with the Thanksgiving seasonal effect, equities and Oil rallied, and the safe haven dollar broke down out of its recent range, to within 1c of the Sep low, itself the lowest level since Apr 2018. Gold collapsed, but bonds stayed in range, ending this three and half day week flat. Bitcoin hit $19,486, very close to its all time high in 2017. The MSCI World index, up 14% so far this month, is on course for its best ever month, after a month of rotation out of tech and into cyclicals and non-US equities.


Next week is a big week for data, led of course by NFP on Friday, with a quite modest 520k estimate. Also important is Fed Chair Powell on Tuesday as the new month opens. After last week’s non-dovish minutes, traders will be looking for the Fed opinion on further stimulus. There are plenty of other CB speakers, including ECB President Lagarde who speaks twice.


Mon Nov 23

Equities and oil rose slightly today on the news of a third vaccine from AZ and Oxford University. SX5E finally broke its pre-COVID high, although pullbacks meant European indices closed  down. Unusually, a strong beat on the US Markit Mfr PMI at 1445 caused a strong spike in the dollar (DXY +0.57% in 10 minutes, and 0.76% in an hour). This may have been helped by strong support at 92.05 (which broke later in the week). Gold, bonds and JPY all fell to confirm a textbook risk-on day.


Tuesday November 24

President Trump’s administration smoothed the path today for the Biden transition team, and this was read, along with the vaccines, as very positive, and equity markets and Oil were sharply up. Gold, bonds and JPY were down in line, as was the dollar giving up the transitory PMI gains. Another risk-on day. Also notable today was a spike up in BTCUSD to $19,486, a level comparable with the Dec 2017 all-time high.


Wednesday November 25

The rally pulled back today after a miss in US Jobless Claims, and FOMC Minutes showing no more dovishness (ie no more stimulus talk) than already known and priced in. However SPX closed at a new ATH. Oil was nevertheless up, although only slightly. Bonds were up in line and Gold was flat. BTCUSD pulled back sharply, down 13.42% at one point, its worst day since March.


Thursday November 26

Thanksgiving Day meant US markets were closed, and equity and Oil futures pulled back slightly, although all movement was only slight as you would expect. The dollar was slightly up, and Gold had another flat day. Bond markets were closed.


Friday November 27

Markets re-opened for a half-day on Black Friday in the US and rose again slightly, with another ATH for SPX. Oil rose in line, and Gold fell, although bonds were up again, meaning a V-shaped week for the US 10-year note. DXY fell again and came within 1c of the Sep low of 91.74. Two more cents down would take us back to April 18’s level.


WEEKLY PRICE MOVEMENT

A lively week with NKY the strongest index mover. NZDJPY was the biggest forex mover, up 1.50%. Crypto volatility, we have seen, with a huge BTC move up and down. FANGS outperformed NDX as a whole, a sign of risk-on.


A third bad week for my forecasting, with EURGBP costing me 0.63%, and taking my running total to 7.81% (21 of 40 wins). I’m taking a chance on risk-on continuing next week and buying GBPJPY.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.


NEXT WEEK (all times are GMT)

(Calendar High volatility items are in bold)

  • New month
  • Non-Farm Payrolls
  • Powell House Testimony
  • Heavy data week


Monday November 30

The last day of the month may see some portfolio-balancing volatility. BoE Tenreyro speaks today. There is a rate decision in Israel. Markets are closed in India and Romania.


23:50 Japan Retail Sales (Sunday)

00:00 Aus TD Securities Inflation

01:00 China PMIs (Mfr e51.5 p51.4)

10:00 OPEC Meeting

10:30 ECB President Lagarde speech

13:00 Germany CPI (YoY e-0.5% p-0.5%)

13:30 Canada Current Account(Q3)

14:30 BoE Tenreyro speech

14:45 Chicago PMI

15:00 US Pending Home Sales (MoM)(Oct)

23:30 Japan Jobs/Unemployment


Tuesday December 1

A new month also sometimes brings volatility, especially with the packed calendar including Fed Powell testimony. Markets remain closed in Romania, and are closed in Dubai for the rest of the week.


00:30 Aus Building Permits (MoM)(Oct)

01:45 China Caixin Mfr PMI

03:30 RBA Rate Decision/Statement (e0.1% hold)

08:55 Germany Unemployment Rate/Change

08:55 Germany Markit Mfr PMI

09:30 UK Markit Mfr PMI

10:00 Eurozone CPI (Core e0.2% p0.2%)

13:30 Canada Q3 GDP (e-39.6% p-38.7%)

14:30 Canada Markit Mfr PMI

14:45 US Markit Mfr PMI

15:00 US ISM PMI (e57.5 p59.3)

15:00 Fed Chair Powell testifies

17:00 Fed Brainard speech

17:00 ECB President Lagarde speech


Wednesday December 2

Fed Williams and ECB Lane speak today. ADP will give us a preview of Friday’s NFP, the estimate is lower. There is a rate decision in Poland.


00:00 RBA Governor Lowe speech

00:30 Aus Q3 GDP (e2.5% p-7.0%)

07:00 Germany Retail Sales (e6.6% p6.5%)

10:00 Eurozone Unemployment

13:15 ADP Employment Change (e420k p365k)

19:00 Fed Beige Book


Thursday December 3

Plenty of data, but relatively low-level. BoJ Suzuki speaks today.


00:30 Aus Imports/Exports/TB (TB e5.8B p 4.84B)

01:45 China Caixin Services PMI(Nov)

08:55 Germany Markit Composite PMI

09:00 Eurozone Markit Composite PMI

10:00 Eurozone Retail Sales (e2.9% p2.2%)

13:30 US Jobless Claims

15:00 US ISM Services PMI (e56.0 p56.6)


Friday December 4

The final NFP of the year is the key takeaway today. There is a rate decision in India.


00:30 Aus Retail Sales (p1.6%)

07:00 Germany Factory Orders

13:30 US NFP/AHE/UnEmp (NFP e520k p638k)

13:30 Canada NFP/UnEmp (NFP e100k p83.6k)

13:30 US Trade Balance(Oct)

15:00 US Factory Orders (MoM)(Oct)

Saturday, 21 November 2020

Week to Nov 20th

Deja vu on vaccine, First ATH for DJIA since Feb, Inside weeks in all asset classes
MY CALL THIS WEEK : SELL EURGBP


There was a sense of deja vu this week as another successful vaccine candidate, this time from Moderna, pushed markets up firmly on Monday to new highs, but from then, markets retreated and consolidated again, as the world seems to progress but cannot shake COVID. All indices moved less than 1% and (except FTSE) reported inside weeks. We also saw inside weeks in DXY, Gold, Bonds and Oil, probably the first time for years that this has happened across all asset classes. The dollar merely reversed last week’s move and DXY has traded in a 3% range, and largely in a 2% range since July. Similarly Gold stayed in the 6% range it has occupied since August.


Mon Nov 16

There was a sense of deja vu today, as MRNA announced that their vaccine was “95% effective”. There was the immediate pre-market in DJI futures but not in NDX futures. Unlike last week, though, the effect persisted all day and SPX closed up 1.2% at a new ATH, as DJIA for the first time since February. The small-cap RUT also hit an ATH, and Oil and yields (inverse to bond prices) were up in line. Other world indices followed suit. Although briefly spiking up on the vaccine news, the dollar retreated to end the day down, following the pullback which started last week, and still within the 2% the greenback has followed since July.


Tuesday November 17

The Retail Sales miss at 1330, and general coronavirus concerns resulted in a slight decline today in markets. SPX fell a little more than NDX. Oil was flat on the day. The dollar continued to pull back, and JPY outperformed in line with the equity move, as did bonds, which advanced. Gold’s reaction, a decline of 0.37% did not follow either equity or dollar trend, but appeared, as we will see later in the week, to be treating the market as still (vaccine) risk-on. We have written before about how Gold sometimes detaches itself from intermarket forces.


Wednesday November 18

Markets tried to rally today, but collapsed in the US afternoon session, with SPX giving up 2.1% from the point Europe closed (up). This may have been a reaction to NYC announcing a new schools closure due to COVID-19. Sentimentally, anything in the Big Apple is going to have more of a reaction. The main index was 1.2% down on the day (NDX down 0.8%). The dollar was down yet again, but reversed from 92.20 support (at which point there was slight EUR resistance at 1.1890). Yen was the largest gainer, in line with stocks. Oil was up on the EIA beat at 1530, and although it pulled back, the black stuff still managed a green candle for the day. Bonds were flat, and Gold once again ignored the dollar and markets, and fell.


Thursday, November 19

After Wednesday’s sharp drop, there was a bounce back today, and markets were slightly up, (NDX outperformed) although only in the final US hour, meaning Europe closed red. Oil and yields were up in line. We are seeing a pattern where good news pushes the market up, but this quickly fades. Note however, that unlike the dollar, and even NDX, SPX and DJIA are starting to break out to new levels. The dollar was down again today, as was Gold and yields, arguably in line with equities


Friday, November 20

A familiar pattern again today, markets tried to rise, but collapsed into the close with little difference between SPX and NDX, as TreasSec Mnuchin decided not to extend several emergency lending facilities set up by the Fed. The dollar bounced again off 92.20, and ended the day slightly up. Gold and Bonds were up in line with the equity move. Oil had its fifth day of gains, making 4.05% up on the week.


WEEKLY PRICE MOVEMENT

A very flat week with no index moving more than 1%, the largest move being SPX. Forex was also quiet with NZDUSD being the strongest mover. EURUSD posted an inside week. FANGs were exciting again with BTCUSD putting on 14.2% in sight of its amazing 2017 high. The crypto-asset BTCUSD has risen 76% in two months. FANGs reflected equities generally and were largely flat.


My GBPUSD short failed again, this time costing me 0.65% taking my running total to 8.44% (21 of 39 wins). I have given up trying to short it, and this week I am selling EURGBP.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.


NEXT WEEK (all times are GMT)

(Calendar High volatility items are in bold)


  • Thanksgiving short week
  • Black Friday
  • Possible sentiment change
  • US Durable Goods and GDP


Monday November 23

CB speeches today from BoE Haldane at 0930, and Fed Daly and BoC Gravelle later in the day. Markets are closed in Japan for Worker’s Day.


22:00 Aus Commonwealth Bank PMIs (Sunday)

08:30 Germany Markit PMIs (Mfr e55.1 p58.2)

09:00 Eurozone Markit PMIs (Comp e49.3 p50.0)

09:30 UK Markit PMIs

13:30 Chicago Fed National Activity Index (Oct)

14:45 US Markit PMIs


Tuesday November 24

A quiet day for data,. BoE Haskel speaks at 1100, with Fed Williams at 1700.


00:30 Aus Imports/Exports/TB

02:30 RBA Debelle speech

07:00 Germany Q3 GDP

09:00 Germany IFO Sentiment Reports

12:05 BoJ Governor Kuroda speech

14:00 US Housing/Home Price Indices

15:00 US Consumer Confidence(Nov)


Wednesday November 25

A raft of US number at 1330 is the busiest data point of the week. FOMC Minutes will of course also be closely watched, but today marks the effective end of the week.


09:00 EU Financial Stability Review

13:30 US Durable/ND Capital Goods (NDC e0.5% p1.0%)

13:30 US PCE/Personal Income

13:30 US Jobless Claims

13:30 US Q3 Prelim GDP (e33.2% p33.1%)

15:00 Michigan CSI

15:00 New Home Sales (MoM)(Oct)

15:00 UK Autumn Forecast Statement (time approx.)

19:00 FOMC Minutes


Thursday November 26

Today is Thanksgiving and US markets are closed. There are rate decisions in Sweden (SEK is part of the DXY basket) and South Korea, but all market activity is expected to be muted.


07:00 Germany Gfk Consumer Confidence Survey

12:30 ECB MPC Minutes

23:30 Tokyo CPI


Friday November 27

Today is retail sales day Black Friday. Also US markets are closed for a half-day as the holiday season starts. There is a rate decision in Colombia.


10:00 Eurozone Consumer Confidence

10:00 Eurozone Business Climate(Nov)