Showing posts with label QE. Show all posts

Monday, 3 January 2022

Review of 2021

Year of the Vaccine and recovery, First year of Biden, and hints of tightening.


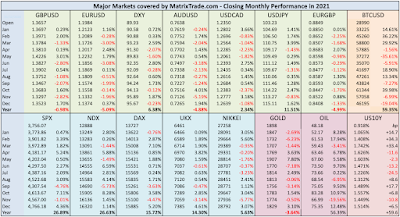
The first full year of the Biden presidency, and of the COVID vaccine program was generally positive, with SPX and NDX both up just over 25%. Notably SPX outperformed NDX for the first time since 2016. There was notable two-way DJI/NDX divergence this year, as the industrial index reacted to COVID, and tech stocks reacted to taper. Foreign indices did better than last year. The dollar recovered last year's losses, as did Oil. Gold was flat on the year, after a 25% rise in 2020. Yields were up 60bp after falling 100bp last year. COVID still dominated everything, and other world events were notably subdued. The most notable factor of the year was the return of inflation, although equally notable. There were no big dips this year in equities.


January 2021
The Capitol riots, and a weak NFP kicked off a weak month, with SPX unable to rise at all. NDX did a little better as it had done throughout the pandemic. The vaccine rollout started in earnest as Joe Biden was inaugurated as the 46th president. The "meme stock" phenomenon started with GME rising from $17 to $482 in a few days, only to pull straight back. Foreign markets were down, as was Gold, whereas Oil rose and yields were up above 1% for the first time since the pandemic.


February 2021

President Biden's commitment to mass vaccination rallied markets, with SPX rallying above and beyond the relatively COVID-immune NDX. Gold fell 6.23% its worst month since November 2016, against a flat dollar. Oil was particularly strong, and yields were up.


March 2021

March saw the worst equity pullback if the year, (although mild by previous years, SPX down 5.21%, DJI 6.62%), after Janet Yellen made hawkish remarks, and the Fed did nothing dovish. The dollar was up 2.59%, its best week since 2016, on tightening fears. Bitcoin surpassed $60,000 for the first time. Gold was down, reacting to the dollar rather than risk, and yields had their best month of the year.


April 2021

A strong earnings season, a blowout 916k NFP, the lowest jobless claims since the pandemic started, and continued rollout of vaccine meant a recovery in equity and oil markets. Bitcoin hit a new ATH of $65k. The dollar pulled back after three months of gains, and Gold recovered, against reacting to the dollar. The turn also affected yields, which turned down for the first time in the year.


May 2021

Sentiment changes this time of year, and with the appearance of the more virulent Indian variant (later called the delta variant), markets were subdued, with SPX flat and NDX slightly down. Another meme stock, AMC, rose 500%, although like GME, never recovered its first high. The dollar was down again, which in addition to the mood gave Gold its best month of the year, and another fall in yields. Oil carried on rising.


June 2021

June saw the G7 meeting agreeing a minimum 15% global corporation tax, which should have depressed the market, but it seems that the only things that matters in 2021 were COVID and QE. NFP was 'Goldilocks', not too high to trigger taper fears, but high enough to shoe recovery. Even the inflation print, a thirteen-year high, and a hawkish Fed did not prevent modest SPX gains, NDX outperformance, and Oil up nearly 10%. The dollar rose in line with the Fed and Gold consequently had its worst month of the year. However yields fell again, running to a different timetable.


July 2021

Another good NFP (850k) and quality earnings kept markets moderately buoyant through July, as traders focus moved away from COVID and towards inflation which the Fed declared to be 'transitory' for now. There were definite pullbacks but these only lasted days and were not deep. Oil rallied as OPEC failed to raise production. Currencies, Gold and oil were flatter than usual, although in the absence of anything hawkish from the Fed, yields fell 24.5bp. 


August 2021

Another great NFP (943k) kept markets (although not Oil) buoyant, with the NDX/DJI making a six-month high. Congress passed the $1Trn infrastructure bill. However gains were trimmed later in the month, when FOMC minutes confirmed taper was on the agenda, and Chair Powell at (virtual) Jackson Hole saying inflation was no longer regarded as transitory. The dollar hit a 9-month high, and yields were back up again. The end of the US 20-year war in Afghanistan had little effect on markets.


September 2021

Concern about taper and the Chinese Evergrande crisis led to a sharp pullback this month (SPX -4.76%) This was expressed very firmly on the massively unexpected Retail Sales print (+2.5% vs -0.1% estimate) which resulted in an instant 0.4% move up in DXY, and 1.73% gain on the month. Notably NKY rallied this month, but admittedly after five months of decline. Gold was down with the dollar move, and Oil down with equities. Yields were sharply up in line with the Retail Sales print's implication of inflation to come. FB, which had been at all-time highs was 10% down after the WSJ published a whistleblower's account of the company's disregard of public safety.


October 2021

With a low NFP print of 194k, October started badly but strong earnings recovered Septembers losses and more, despite continued hawkish views from the Fed. In fact, SPX and NDX had their best months of the year, and Oil was up 10% in line, with no particular reason except the time of year, and perhaps the continuing vaccine program and general recovery. The dollar was flat, as was Gold.  FB dropped 5% after a one-day outage, but this was recovered a week later. Inevitably the dollar rallied, hitting a 16-month high. Gold was flat.


November 2021

The rally was halted with another poor month for SPX (-1.01%) on the outbreak of the much more transmissible but, it turned out later, less serious omicron variants of COVID. The long-expected taper timetable announcement was actually seen as positive, removing uncertainty, and mitigated the drop. NDX managed to stay green despite the 31-year high CPI print of 6.2% (which came after the Fed announcement), and the NDX/DJI ratio reached its highest level since 2000. The dollar was of course up, again with flat Gold, but Oil followed omicron and fell nearly 20%. Notably Bitcoin hit a new ATH at $69k. Yields were down.


December 2021

Despite another low NFP, the year finished nicely with a traditional Santa Rally across US and international markets, all reaching 2021 and in many cases all-time highs as omicron fears faded. The dollar was slightly down, producing a small rise in Gold. Oil rallied over 10% and yields recovered slightly.


Sunday, 7 April 2019

Week to Apr 5th


Equities rally on China hopes, Flat dollar despite wild GBP, Best crypto week for over a year

Mon Apr 01
The first day of the week, the month and the quarter opened strongly after the China Manufacturing PMI beat at 0145. We pointed out the significance of this last week. The figure came in at 50.8 vs 49.9 est, only 0.9 beat, but critically crossing the 50 point, the line between contraction and expansion. The important US ISM similar release beat at 1400, giving a sharp uptick to USDJPY. (the same release for Germany at 0700 - 44.1 vs 44.7 est - showed that last month’s print of 47.6 was not an outlier, as some commentators had thought.

The net result was a strong risk-on run for equities across the board, and an advance of 0.13% for DXY. EUR, JPY, Gold and 10-year Bonds (inverse to yields) dropped suddenly after the ISM print. Against this, CAD perked up after hawkish (well less dovish than expected) remarks from the BoC at 1755. AUD, without news, was flat. The dollar advance would have been greater expect for cable, up 1% on ‘soft’ Brexit hopes.

Tuesday April 02
As we predicted last week, the RBA did indeed join the chorus of doves at 0330, and the day started with a sharp fall in AUD. GBP had collapsed overnight, but climbed back to end the day flat on reports of bipartisan (ie May and opposition leader Corbyn) Brexit talks. CAD faded the Poloz gains. As AUD is not part of DXY, and the other majors had a quiet day, the DXY basket closed virtually flat (-0.03%), as did yields. Gold was slightly up. Equities had another good day, but mostly outside the US. NDX managed to add 0.3% but SPX was flat.

What was interesting is that after months in the doldrums, BTC spiked up 20% up in an hour from 0430, with, obviously, over 100x normal volume (and held onto these gains). This was accompanied by a similar move in ETH, but that took two days to complete. Naturally rumours abounded an Asian ‘whale’ in this unregulated world.

Wednesday April 03
Reports in the FT that the US and China were close to finalising their trade deal, plus a raft of PMI Services beats, resulted in a third day of equity gains, particularly in DAX. Only the US wobbled slightly after their ISM Non-Manufacturing print missed at 1400, trimming an SPX 0.6% advance to 0.2% at the close. After two green days Oil was down slightly after the substantial EIA stock miss (+7.2M vs -0.4M, more is worse) at 1430.

DXY shed 0.22% today, on the contrasting US and other PMIs, and possibly the ADP jobs miss at 1215. Gold was down, and yields and AUD were up in line with risk-on equities. JPY and CAD were probably pulled in two directions, risk on vs dollar weakness and Oil respectively. Both currencies were flat. EUR and GBP were both up.

Thursday April 04
Another up day from equities as Trump confirmed the China progress, although the pace was slowing. FTSE gapped down 0.4% to reflect overnight GBP strength but managed to recover this to end flat. The dollar recovered to close where it ended on Tuesday, evenly across all currencies. Oil faded slightly in line with the dollar. Gold was unusual, spiking down 0.5% through six hours to touch it Mar 7 low before recovering. Yields were flat on the day.

Friday April 05
Without a lead from China, which was closed, markets breathed a sigh of relief on the NFP beat at 1230, showing that last month was an outlier, and all were up, although the DAX gain was marginal. The SPX ran nicely to a pattern we have pointed out before, where after an instant spike, the price fades until the cash open, and then the size of that spike is repeated, as shown in the chart here. The trade is to buy SPX at the open, with a stop below the pre-NFP price, and a target of the ramp repeated. Oil was up 1.5% in line with the mood.


DXY was only very slightly up (+0.07%), EUR made small gains to offset the fall in GBP (Brexit) and CAD (Canadian NFP miss). After a strong week, yields fell 4bp after Trump called for the Fed to reintroduce QE.

The US major markets are now very close to previous all-time highs. SPX and DJIA are 1.68% away, NDX is even nearer at 1.39%, although notably RUT, DAX, NKY are around 10% off. It will be interesting to see if the SPX record close of 2930 is beaten next week.


WEEKLY PRICE MOVEMENT
Another strong week for DAX makes it the top index mover again. In forex, the best trade would have been AUDJPY, up 0.90%. FANGs all beat their parent NDX index, with a particularly strong showing from FB, and the Tuesday crypto spike held, to give BTC and ETH their best week for over a year.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on UUP. The equity and index prices are now based on the cash close each day.


NEXT WEEK (all times are GMT, not BST)


(Calendar High volatility items are in bold)
  • EU consider further Brexit delay
  • US, China and German inflation
  • ECB rate decision and statement
  • Earning season starts on Friday

Monday April 08
After last weeks big calendar and start to the week and quarter, we are back to the usual quiet Monday today. Watch out for any weekend news, particularly on Brexit or Trump tweets. There are rate decisions on ILS and LKR. Markets are closed in Thailand.

06:00 EUR Germany Trade Balance
14:00 USD US Factory Orders (MoM)

Tuesday April 09
Another quiet day, with no releases in the European and US cash sessions, except the JOLTS jobs openings at 1400. Fed Vice Chair Clarida, (voter, obviously) centrist by definition, but thought to be leaning dovishly at the moment. Markets are closed in the Philippines and in Israel where there is an election, where the incumbent Likud government may not win. There is a rate decision on RSD.

01:30 AUD Aus Home Loans
05:45 CHF Switzerland Unemployment Rate
20:30 WTI API Oil Stock
22:45 USD Fed Clarida speech
23:01 GBP UK BRC Like-For-Like Retail Sales
23:50 JPY Japan Machinery Orders

Wednesday April 10
Easily the busiest day of the week, the EU summit is almost certain to grant UK PM May a long extension to Brexit, rather than the short one she has asked for, figuring that the longer the extension, the softer the eventual Brexit, which is the EU’s stated preference. With Bund yields still negative, the ECB statement should prove interesting. Further TLTRO details may be unveiled, and if not, may be asked about in the presser.

US CPI is expected to be unchanged, which validates the Fed’s current no hike policy. The risk is to the upside, ie a beat may make traders think again. Although not a rate set meeting, the FOMC March minutes today put some flesh on the bones of the dovish reversal seem recently.

00:30 AUD Aus Westpac Consumer Confidence
02:30 AUD RBA's Debelle speech
06:15 JPY BoJ Governor Kuroda speech
08:30 GBP UK Manufacturing/Industrial Production
08:30 GBP UK GDP (MoM Feb)
11:45 EUR ECB Rate Decision/Statement (est 0% hold)
12:30 USD US CPI (Core YoY est 2.1% prev 2.1%)
12:30 EUR ECB Presser
15:30 WTI EIA Oil Stock
15:50 USD Fed Quarles speech
18:00 USD FOMC Minutes

Thursday April 11
Voting in the Indian election starts today. The world’s largest electorate will take six weeks to vote, with the counting starting on May 23. Exit polls are notoriously unreliable, but nevertheless, any significant move from the BJP to the Congress party may have an effect on markets. Chinese and German inflation are the key prints on the day.

00:00 AUD Aus Consumer Inflation Expectations
01:30 CNY China CPI (est 2.3% prev 1.5%)
02:30 AUD RBA's Debelle speech
06:00 EUR Germany CPI (est 1.4% prev 1.5%)
12:30 USD US PPI
12:30 USD US Jobless Claims
13:30 USD Fed Clarida 2nd speech
20:00 USD Fed Bowman speech
22:30 NZD Business NZ PMI
22:45 NZD NZ Electronic Card Retail Sales 

Friday April 12
The Q1/2019 Earnings Season starts today with the usual first reporter JPM, and fellow bank WFC, before the bell. The dovish Fed is bad for banks, and traders will be watching forward estimates closely. The IMF begin a three-day meeting in Washington DC. Today is the next Brexit 'deadline' although it is likely another extension will have been granted before then. Markets have a half-day in Sri Lanka. There are elections in Finland on Sunday.

02:00 CNY China Imports/Exports/Trade Balance
02:15 CNY China FDI
09:00 EUR Eurozone Industrial Production
14:00 USD Michigan Consumer Sentiment Index (est 98.0 prev 98.4)
17:00 WTI Baker Hughes Rig Count

This report is published every week as an email by MatrixTrade.com - you can sign up to receive it here. This blog is supported solely by advertising, so if any of the ads interest you, please click on them. If you want notification when the blog is updated, please follow me on Twitter, Facebook, Stocktwits, TradingView or Linkedin (all open in separate windows). Details of how I compile the report are here