Showing posts with label YearReview. Show all posts

Monday, 3 January 2022

Review of 2021

Year of the Vaccine and recovery, First year of Biden, and hints of tightening.


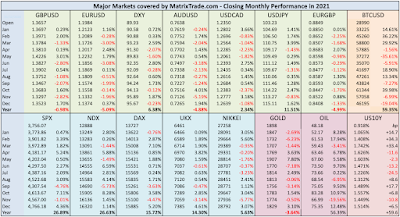
The first full year of the Biden presidency, and of the COVID vaccine program was generally positive, with SPX and NDX both up just over 25%. Notably SPX outperformed NDX for the first time since 2016. There was notable two-way DJI/NDX divergence this year, as the industrial index reacted to COVID, and tech stocks reacted to taper. Foreign indices did better than last year. The dollar recovered last year's losses, as did Oil. Gold was flat on the year, after a 25% rise in 2020. Yields were up 60bp after falling 100bp last year. COVID still dominated everything, and other world events were notably subdued. The most notable factor of the year was the return of inflation, although equally notable. There were no big dips this year in equities.


January 2021
The Capitol riots, and a weak NFP kicked off a weak month, with SPX unable to rise at all. NDX did a little better as it had done throughout the pandemic. The vaccine rollout started in earnest as Joe Biden was inaugurated as the 46th president. The "meme stock" phenomenon started with GME rising from $17 to $482 in a few days, only to pull straight back. Foreign markets were down, as was Gold, whereas Oil rose and yields were up above 1% for the first time since the pandemic.


February 2021

President Biden's commitment to mass vaccination rallied markets, with SPX rallying above and beyond the relatively COVID-immune NDX. Gold fell 6.23% its worst month since November 2016, against a flat dollar. Oil was particularly strong, and yields were up.


March 2021

March saw the worst equity pullback if the year, (although mild by previous years, SPX down 5.21%, DJI 6.62%), after Janet Yellen made hawkish remarks, and the Fed did nothing dovish. The dollar was up 2.59%, its best week since 2016, on tightening fears. Bitcoin surpassed $60,000 for the first time. Gold was down, reacting to the dollar rather than risk, and yields had their best month of the year.


April 2021

A strong earnings season, a blowout 916k NFP, the lowest jobless claims since the pandemic started, and continued rollout of vaccine meant a recovery in equity and oil markets. Bitcoin hit a new ATH of $65k. The dollar pulled back after three months of gains, and Gold recovered, against reacting to the dollar. The turn also affected yields, which turned down for the first time in the year.


May 2021

Sentiment changes this time of year, and with the appearance of the more virulent Indian variant (later called the delta variant), markets were subdued, with SPX flat and NDX slightly down. Another meme stock, AMC, rose 500%, although like GME, never recovered its first high. The dollar was down again, which in addition to the mood gave Gold its best month of the year, and another fall in yields. Oil carried on rising.


June 2021

June saw the G7 meeting agreeing a minimum 15% global corporation tax, which should have depressed the market, but it seems that the only things that matters in 2021 were COVID and QE. NFP was 'Goldilocks', not too high to trigger taper fears, but high enough to shoe recovery. Even the inflation print, a thirteen-year high, and a hawkish Fed did not prevent modest SPX gains, NDX outperformance, and Oil up nearly 10%. The dollar rose in line with the Fed and Gold consequently had its worst month of the year. However yields fell again, running to a different timetable.


July 2021

Another good NFP (850k) and quality earnings kept markets moderately buoyant through July, as traders focus moved away from COVID and towards inflation which the Fed declared to be 'transitory' for now. There were definite pullbacks but these only lasted days and were not deep. Oil rallied as OPEC failed to raise production. Currencies, Gold and oil were flatter than usual, although in the absence of anything hawkish from the Fed, yields fell 24.5bp. 


August 2021

Another great NFP (943k) kept markets (although not Oil) buoyant, with the NDX/DJI making a six-month high. Congress passed the $1Trn infrastructure bill. However gains were trimmed later in the month, when FOMC minutes confirmed taper was on the agenda, and Chair Powell at (virtual) Jackson Hole saying inflation was no longer regarded as transitory. The dollar hit a 9-month high, and yields were back up again. The end of the US 20-year war in Afghanistan had little effect on markets.


September 2021

Concern about taper and the Chinese Evergrande crisis led to a sharp pullback this month (SPX -4.76%) This was expressed very firmly on the massively unexpected Retail Sales print (+2.5% vs -0.1% estimate) which resulted in an instant 0.4% move up in DXY, and 1.73% gain on the month. Notably NKY rallied this month, but admittedly after five months of decline. Gold was down with the dollar move, and Oil down with equities. Yields were sharply up in line with the Retail Sales print's implication of inflation to come. FB, which had been at all-time highs was 10% down after the WSJ published a whistleblower's account of the company's disregard of public safety.


October 2021

With a low NFP print of 194k, October started badly but strong earnings recovered Septembers losses and more, despite continued hawkish views from the Fed. In fact, SPX and NDX had their best months of the year, and Oil was up 10% in line, with no particular reason except the time of year, and perhaps the continuing vaccine program and general recovery. The dollar was flat, as was Gold.  FB dropped 5% after a one-day outage, but this was recovered a week later. Inevitably the dollar rallied, hitting a 16-month high. Gold was flat.


November 2021

The rally was halted with another poor month for SPX (-1.01%) on the outbreak of the much more transmissible but, it turned out later, less serious omicron variants of COVID. The long-expected taper timetable announcement was actually seen as positive, removing uncertainty, and mitigated the drop. NDX managed to stay green despite the 31-year high CPI print of 6.2% (which came after the Fed announcement), and the NDX/DJI ratio reached its highest level since 2000. The dollar was of course up, again with flat Gold, but Oil followed omicron and fell nearly 20%. Notably Bitcoin hit a new ATH at $69k. Yields were down.


December 2021

Despite another low NFP, the year finished nicely with a traditional Santa Rally across US and international markets, all reaching 2021 and in many cases all-time highs as omicron fears faded. The dollar was slightly down, producing a small rise in Gold. Oil rallied over 10% and yields recovered slightly.


Sunday, 3 January 2021

Review of 2020

 The year of COVID, New US President, Interest Rates to zero, Bitcoin triples


The China trade war took a back seat as the year was dominated by the effect of COVID-19 on the economy, the degree of lockdown, and the stimulus measures used to keep markets and confidence afloat. Against this, what would normally be the principal event of the year, the presidential election, almost seemed like a sideshow. Markets saw their fastest deep crash since 1987 or even 1929, but rebounded fairly quickly, particularly in the tech sector, where a move on online work and life produced COVID winners old (AMZN, NFLX) and new (ZM). European indices fared much worse, not helped by currency appreciation, with DAX only flat for the year and FTSE down. The dollar was down on the year, and the yen even more reflecting the strong equity rally. AUD was the top currency, reflecting its lighter COVID burden, but the outstanding performer was Bitcoin, whose value tripled, in a rally reminiscent in season and scale of 2017.


January 2020

The year started with the China Phase 1 trade agreement in place and strong earnings, and new all-time highs were reached on the 13th. However we then got the first inklings of COVID-19 from Wuhan, China at the end of the month, and the market pulled back to close slightly down. The Iranian assassination incident on the 3rd initially spiked Oil, which then pulled back sharply when the Iranians didn’t retaliate, and the black stuff was down 15%. In line with the negative moves in equities and Oil, we saw Gold, bonds and yen all appreciated materially. Of course much more was to come …


February 2020

News that would normally substantially move markets, such as the Trump impeachment acquittal and Joe Biden losing the Iowa Caucus (leaving the possibility of left-wing Bernie Sanders as the Dem candidate) was all ignored as the world woke up to the seriousness of COVID-19. South Korea declared an emergency, Italy suspended China flights, and companies started to revise their guidance. Equity and Oil markets tumbled (SPX -8.41%, CL -12.28%) mostly in the final week which was the worst in decades. Bonds soared as a safe haven, but against a flat dollar, Gold was up less than 5%, an early inkling of its reduced value as a risk indicator.


March 2020

This was the worst month in decades, and the quickest drop in history, as the seriousness of COVID was shown in Italy. On 3rd, the Fed made a 50bp emergency cut, which has little effect, so on 16th, cut the rate to zero, which arrested the drop. The low point for SPX was 35.2% below the February high, only 23 days earlier. Oil’s drop was even more momentous, over 50% down in the same period. Further QE stimulus was announced on the 20th. The final week’s bounce back up (+12%) was the best week for SPX since 1938. Also this month (4th) Joe Biden won Super Tuesday, confirming his nomination for the Presidential race, and virtually the entire western world went into lockdown. As you would expect, bonds soared again, with the 10-year rate dropping 48.4bp to 0.668%.


April 2020

Strong lockdowns inevitably arrested the rise in COVID cases, and markets did not return to the March lows. The first week posted the worst initial jobless claims number in history, and the worst NFP since 2009 (-1.373M). Earnings estimates had all been revised down sharply in February and March, and although many companies reported earnings between a third and two thirds lower than Q4/19, stocks steadily rose throughout the month, helped by even more QE stimulus on 9th. Also seen this month was noticeable lockdown rotation, stocks such as NFLX recovered extremely quickly (it had beaten its March low by Apr 14), whereas aviation and travel stocks languished at around a quarter of their pre-lockdown highs. SPX closed up 12.68%, although failing to recover all of March’s fall.


The dollar was stable, ending the month flat. However, the contagion spread to other assets, with Gold up 7%, and the amazing story of Crude Oil. After the momentous drop in March, so much pressure was put on the near (May-20) contract that on the day before expiration, it actually moved into negative territory for a few hours, as low as minus $37.63 a barrel. The next day, the June contract fell 70% to $6.50, prices not seen for decades.


May 2020

There was no ‘Sell in May’ this year, except for the first day, as markets were still largely oversold after the March crash. This despite the worst NFP report, by an order of magnitude, over 20 million jobs lost in April. Warren Buffett exited the airline sector, a sign that he doesn’t see even a medium-term recovery. Markets fell in Hong Kong, not on COVID, which they were handling well, but on the new Beijing-inspired security laws. However there was a glimmer of hope, as MRNA reported successful vaccine trials. Overall SPX was up a modest 4.5%, but Oil made a much faster recovery, up 73% on the month. Once again the dollar (-0.75%) was flat and Gold (+2.61%) was up.


June 2020

After two months of lockdown with the inevitable fall in COVID cases, markets were cautiously optimistic, especially with a reversal in the NFP situation. The print of +2.725 million was the best since records began in 1939, and other macro metrics had improved. Also the ECB added €600Bn of QE, and crucially the White House did not escalate the trade war due to the Hong Kong situation. Nevertheless there were setbacks, for example a spike in Texas and California cases caused a 7% market drop on 12th, and SPX only added a modest 1.84% for the month, but 19.95% for the quarter, the best quarter for decades. Lockdown equals online, and online equals tech, and NDX added 6.29% fully covering the March dip and posting new all-time highs. Other assets were similar to May, the dollar again fell only slightly (-0.93%), Gold was up 3.07%, and Oil continued its fast recovery adding 12.4%.


July 2020

Further good news this month led to a smooth rise in equity markets. BNTX announced successful vaccine trials (we now know this as the PFE vaccine), and MRNA confirmed further success. Shares in both these companies soared. Also the NFP print made yet a new record, adding 4.8M jobs, and the Fed made more dovish noises. Markets continued to rotate into COVID-proof tech stocks, with NDX adding 7.37% vs 5.51% for SPX. The Fed policy did however finally trigger a large drop in USD, with DXY falling 4.03%. The underlying fragility of the recovery, plus the dollar move meant that Gold added 10.83% and made new all-time highs after 11 years.


August 2020

August saw the inflation rules changed at the virtual Jackson Hole conference, a dovish move, more stimulus was discussed in Congress, and Russia announced a working vaccine. The Democrats selected Joe Biden as their candidate, not the left-wing Bernie Sanders. All positive and SPX duly rose again up 7.42% with considerable outperformance from NDX up 13.58%, as good as April, the first recovery month. SPX recovered the COVID drop on 21st making a new ATH. Oil rose 5.19%. Gold consolidated, as did the dollar, only dropping 1.39% after the large fade in July.


September 2020

In September, a ‘whale’ buyer (Softbank) was discovered as part of the reason for the substantial NDX outperformance over summer, and there was a sharp pullback in the first three weeks of the month, but mostly the days into and after Labor Day. A lot of this was a ‘healthy correction’, as NDX had reached an RSI level of 81, the highest since Dec 2019, and the DJI/NDX ratio fell to 2.32 on Aug 31, the lowest since March 2000, and the second only time since NDX was created in 1986. AAPL and TSLA had performed splits, which distorted DJIA, and the Fed was insufficiently dovish at their meeting on the 16th. SPX was down over 10% and NDX 14% by the 21st, and only a statement to Congress by Chair Powell saying that further stimulus was needed, a point unusually echoed by a raft of Fed speakers that week, and supported by Speaker Pelosi, reversed the decline and SPX ended the month 4% down. NDX was down 6.5% and the DJI/NDX ratio rose 3.65%, the highest since October 2018, setting the stage for a bottom in that ratio and the COVID-driven almost daily rotation we have seen since. The only other good news was successful trials of the AZN/Oxford vaccine. The equity drop caused a slight dollar recovery, up 1.79%, and Gold followed that with a 4% drop. Oil followed equities and declined 6.32%


October 2020

This was of course the month before the election, and when not pre-challenging the election result in advance, the President caught and quickly recovered from COVID, mentioned stimulus being delayed post-election, but then came up with a figure ($1,200 for every American). The Biden lead did not advance, but COVID cases most certainly did. However there was positive news in that PFE, then MRNA, then AZN announced on consecutive Mondays that their vaccine was very (ie 90% or more) effective, and also we had Thanksgiving, and the rally that usually accompanies it, which finally made a new ATH for DJI. Nevertheless, this good news balanced uncertainly about COVID cases, the stimulus and the election, and led to a stalemate, ie a consolidating month in both SPX (-2.77%), the dollar (0.25%), and Gold (-0.42%). Only Oil collapsed, down 10%.


November 2020

Joe Biden won the election, eventually, although the Senate remained undecided until Georgia run-off elections on Jan 5. The election was called for Biden over the weekend 7/8, although President Trump refused to concede (and still has at the time of writing). Of more importance, PFE announced before the 9th Monday bell that their vaccine (formerly the BNTC vaccine) trials were complete and was over 90% effective. DJIA futures rose 4% in seconds (finally hit a new ATH), and most notably NDX dropped sharply, the quickest rotation every seen. This happened twice on the following two Mondays for the MRNA and then the AZN vaccines, with similar effects. This was enough to drive optimism into Thanksgiving at which point seasonal sentiment took over. History may well show a Biden election rally but careful examination of timing on Mon 9th show that was not the cause. The month end shows a rare situation where SPX was up 10.75%, its best month since April, but NDX was down, as money moved out of COVID-immune tech back into the battered and underpriced defensive sectors. The dollar and Gold continued to consolidate in their 3% (dollar) and 6% (Gold) ranges, although following the vaccine rally, Oil was up 25%.


December 2020

The Santa Rally took over, with a healthy gap up on the first day and with the vaccine program underway, equity markets rose in waves throughout the month. The finalisation of the Brexit deal also helped. However, set backs such as the new more virulent strain of coronavirus on 21st, created pullbacks and SPX only managed to add 3.71% for the month, although NDX did better, both making new highs, a sign that seasonal sentiment was more important than COVID. On 17th, Bitcoin broke through its 2017 high, also co-incidentally on 17th Dec. It carried on, ending up at triple its 2019 closing value. Oil added 7.04% although it still ended 21% down on the year. The dollar continued to make new 30-month lows, ending the year 6.85% down, with all currencies up. Gold continued to fall on the weaker dollar, adding 5.74%, and ending up a better investment than SPX (although not NDX) for the year.