Showing posts with label taper. Show all posts

Sunday, 19 December 2021

Week to Dec 17th

Fed confirms taper acceleration, dollar up, equities down
MY CALL THIS WEEK : SELL USDCAD


THIS WEEK

As expected, the Fed doubled the pace of taper this week in response to runaway infation (worse this week), and forecast three rate hikes in 2021, the first in January. The BoE delivered a surprise rate rise of 0.15% which made GBP the second strongest currency after the dollar this week.


Markets sold into the Fed, and after a brief spike on the announcement, fell again, with rate-sensitive NDX underperforming. The dollar did the reverse, rallying into Wednesday, spiking down then rallying again. Gold was back up over $1,800 for the first time in three weeks, and Oil had relatively low volatility, despite the weak CAD move. Yields were down, in an inside week that partially reversed last week.


WEEKLY PRICE MOVEMENT

The biggest index mover was NDX, down 3.25%, in what was still an inside week. The top forex mover was USDCAD up 1.31%. Bitcoin and Ethereum were flat after last week's drop, and FANG performed even worse than NDX, except for FB.


Last week’s AUDNZD short made 0.23%, taking my year to date profit to 5.83% and 33/49 wins. This week I will take the reversal of the top mover and short USDCAD.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.


NEXT WEEK


The four-day week will be quiet as traders wind down for the Christmas holiday. The US, Europe and the UK (half day) will be closed on Friday. On the calendar is the relatively unimportant final GDP reading from the UGK, US and Canada, which are estimated to be in line with preliminary readings. Even PCE (Fed's preferred method of inflation) of low interest after Fed have already spoken on taper acceleration. Other than this, the week is traditionally bullish.


CALENDAR  (all times are GMT)


Monday December 20

01:30 PBoC Interest Rate Decision (e3.85% hold)


Tuesday December 21

00:30 RBA Meeting Minutes

07:00 Germany Gfk Consumer Confidence

13:30 Canada Retail Sales (MoM e1.2% p-0.6%)

15:00 Eurozone Consumer Confidence

23:30 Aus Westpac Leading Index

23:50 BoJ MPC Minutes


Wednesday December 22

07:00 UK Q3 Final GDP (e1.3% p1.3%)

13:30 Chicago Fed National Activity Index

13:30 US PCE QoQ

13:30 US Final Q3 GDP Annualised (e2.1% p2.1%)

15:00 US Consumer Confidence


Thursday December 23

13:30 US PCE MoM & YoY

13:30 US Durable/ND Capital Goods (Nov Durable e1.5% p-0.4%)

13:30 US Jobless Claims

13:30 Canada Q3 GDP

15:00 Michigan CSI

15:00 US New Home Sales

23:30 Japan National CPI


Friday December 24 

No releases

Sunday, 5 December 2021

Week to Dec 3rd

Fed hint of taper acceleration adds to omicron misery.

MY CALL THIS WEEK : BUY NZDJPY


THIS WEEK

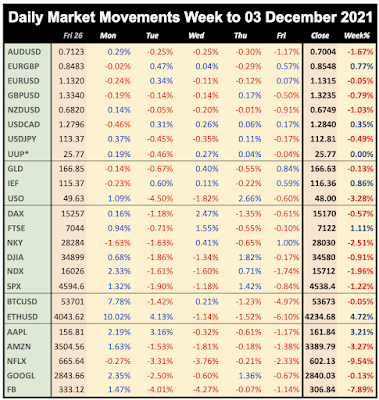
This week, the Omicron variant continued to spread, albeit slowly, but a warning from MRNA that their vaccine may be less effective weighed on the market, and indeed on their own stock which, unlike fellow vaccine producer PFE, was also down. Of more concern to markets was Fed Chair Powell's testimony to the Senate where he explicitly confirmed that inflation is no longer 'transitory', and indicated that the rate of taper may be accelerated (ie to finish before June 2022). If the DJI had not already had three down weeks, at one point 7% off its last high, the drop might have been worse. All indices were down except FTSE which rose on sterling weakness.


The dollar was strong against commodity/risk currencies AUD, NZD and CAD, and indeed GBP, although a flat Euro and safe haven yen appreciation led to a perfectly flat week for the DXY basket. Gold was down slightly, and Oil fell to below $63/bbl, a four-month low. The 2-year US bond hit highs not seen since the pandemic collapse in Mar 2020, and given the sharp dip in 10-year paper, the yield curve (US10Y-US02Y) had its worst week for a decade.


The material NFP miss (210k vs 550k) caused the logical reaction, a decline from the open until the last 15 minutes when a few shorts took profit. There was a momentary 'bad delays taper' spike to the upside on the print, so it is hard to say whether Friday's decline was driven by the miss, or the general downward taper acceleration and omicron pressure. The severe underperformance of NDX on Friday suggests the former.


WEEKLY PRICE MOVEMENT


The biggest index mover was NKY, down 2.51%. The top forex mover was AUDJPY this week, down 2.16%. Bitcoin and Ethereum were flat,, and FANGs, except AAPL were particularly weak.


Last week’s NZDJPY short lost 1.55%, taking my year to date profit to 4.35% and 31/47 wins. This week I am convinced it will recover and thus buying NZDJPY again.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.


NEXT WEEK


There is only really one important print next week, the US inflation print on Friday. The core estimate of 4.9% is the highest for years and the Fed have said that acceleration of taper program will follow. A much lower figure would move markets strongly, ahead of the FOMC meeting on Dec 15. Chinese and German inflation are also reported. Otherwise Omicron news is likely to dominate, although of course, with markets already over 5% off highs, a lot of both these factors has already been priced in, given the normally buoyant time of year. 


CALENDAR  (all times are GMT)


Monday December 6

00:00 Aus TD Securities Inflation

07:00 Germany Factory Orders

11:30 BoE Broadbent speech

23:30 Japan Overall Household Spending


Tuesday December 7

00:30 Aus House Price Index

02:00 China Imports/Exports/TB

03:30 RBA Rate Decision/Statement (e0.1% hold)

05:00 Japan Leading Economic Index

07:00 Germany Industrial Production

10:00 Eurozone Q3 GDP (QoQ e2.2% p2.2%)

10:00 Germany ZEW Sentiment

13:30 US Trade Balance

13:30 US Productivity/Labor Costs

13:30 Canada Trade Balance

15:00 Canada Ivey PMI

23:50 Japan Q3 GDP (e0.4% p-0.8%)


Wednesday December 8

10:30 DE10Y Bond Auction (time approx.)

15:00 BoC Rate Decision/Statement (e0.25% hold)

22:00 RBA Governor Lowe speech


Thursday December 9

01:30 China CPI (YoY e2.5% p1.5%)

07:00 Germany Trade Balance

13:30 US Jobless Claims

19:00 BoC Gravelle speech


Friday December 10

07:00 UK GDP

07:00 UK Ind/Mfr Production

07:00 Germany CPI (YoY e6.0% p6.0%)

13:30 US CPI (Core YoY e4.9% p4.6%)

15:00 Michigan CSI (e67 p67.4)

19:00 US Monthly Budget Statement

Sunday, 7 November 2021

Week to Nov 5th

Taper confirmed, NFP beat, new ATHs
MY CALL THIS WEEK : BUY GBPNZD


THIS WEEK

This week saw the Fed finally introduce taper, as widely expected, to start immediately at the rate of $15Bn per month, meaning the taper will complete in June 2022. The Fed warned that the programme may alter if conditions change. The equity market welcomed the certainty, in addition to a strong ISM PMI and further strong earnings, and hit new highs. As predicted by ADP, the first post-taper NFP was a firm beat, and without the "bad is good, tightening delay" factor, markets reacted as you would expect, rising to further highs. In fact markets made a high every single day this week. Markets took some profit into the Friday close.


Yields fell all week, as did most currencies against the dollar, strengthened by the taper announcement. The pullback in Oil from the multi-year highs, did not allow commodity currencies (AUD and CAD). The only unusual move was from Gold which rose despite the risk on and strong dollar.


WEEKLY PRICE MOVEMENT


The biggest mover this week was again NDX, up 3.21%. The top forex mover was AUDJPY this week, up 2.09%. Bitcoin and Ethereum were flat, and FANGs were variable but generally strong (except NFLX). My EURGBP long made 1.5% taking profit year to date to 5.77% and 29/43 wins.


Week to 5 Nov 21


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.


NEXT WEEK (all times are GMT)


Things are much quieter next week. The US Daylight Savings Time ends putting market hours back in line with Europe. Veterans/Armistice Day on Thursday is not a market holiday anywhere except France. The only notable macro event is US inflation, estimated to remain at 4%. Other than that there is Aussie jobs and UK GDP, and one major warnings report, DIS, on Wednesday.


CALENDAR (all times are GMT)


Monday November 8

05:00 Japan Leading Economic Index

23:50 Japan Current Account


Tuesday November 9

00:00 HIA New Home Sales (time approx.)

07:00 Germany Trade Balance

10:00 Germany ZEW Economic Indicators

13:30 US PPI

17:10 BoC Beaudry speech

22:45 BoC Governor Macklem speech

23:30 Aus Westpac Consumer Confidence


Wednesday November 10

01:30 China CPI

07:00 Germany CPI (YoY e4.6% p4.6%)

10:30 DE10Y Bond Auction (time approx.)

13:30 US CPI (YoY e4.0% p4.0%)

13:30 US Jobless Claims

19:00 US Monthly Budget Statement


Thursday November 11

00:00 Aus Consumer Inflation Expectations

00:30 Aus NFP/UnEmp (NFP e50k p-138k)

07:00 UK Mfr/Ind Production

07:00 UK GDP (YoY p5.5%)

09:00 Eurozone Economic Bulletin


Friday November 12

10:00 Eurozone Industrial Production

15:00 Michigan CSI

Sunday, 24 October 2021

Week to Oct 15th

Earnings week strong start, CPI beat, Taper looming
MY CALL THIS WEEK : BUY NZDCAD


LAST WEEK


After a lacklustre start, the strong earnings from JPM on Wednesday and the US CPI beat triggered a two-day rally as the other banks also easily beat estimates, with a particularly strong showing from GS. A Fed taper announcement in November still looks likely and the Fed’s Bostic admitted price increases “will not be brief.” The market’s reaction to all this was somewhat contra to the norm, reversing recent strength in the USD and yields, accompanied by large rallies in stocks and metals.


WEEKLY PRICE MOVEMENT

The biggest mover this week was NKY, up 3.64%. The top forex mover was NZDJPY this week, up an amazing 4.13%, a major forex magnitude not seen for years. Bitcoin and ETH were strongly up again, and FANGs were once again variable.

Another bad week, losing 2.69% on my CADJPY short, taking my year to date profit to 3.09%, half of what it was two weeks ago, and 27/40 wins. This week I am buying NZDCAD again.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.

 
NEXT WEEK (all times are GMT)

Earnings season continues next week, with a wider range than the banks last week. As always first FANG to report is NFLX on Tuesday, with NDX giants TSLA and INTC later in the week. Dow giants IBM, JNJ and PG also report. From China, we have GDP, Retail Sales and a rate decision, as well as an Evergrande debt deadline on Tuesday. There are inflation reports from the UK and Canada, but otherwise little of significance in sovereign scheduled data. The first Bitcoin ETF is launched on Monday.

 
CALENDAR (High volatility items in bold)

Monday October 18
02:00 China Q3 GDP (YoY e5.2% p7.9%)
02:00 China Retail Sales (YoY e3.3% p2.5%)
09:30 Fed Quarles speech
15:40 BoC Lane speech
18:00 US Monthly Budget Statement

Tuesday October 19
00:30 RBA Meeting Minutes
12:30 US Building Permits/Housing Starts
17:15 Fed Bowman speech
19:00 Fed Waller speech
23:30 Aus Westpac Leading Index
23:50 Japan Imports/Exports/TB

Wednesday October 20
01:30 PBoC Rate Decision/Statement (e3.85% hold)
06:00 UK CPI (p3.2%)
09:00 Eurozone CPI
10:30 Germany 10Y Bond Auction (time approx.)
12:30 Canada BoC CPI (p3.5%)
17:00 Fed Quarles speech
18:00 Fed Beige Book

Thursday October 21
00:30 Aus NAB Business Confidence
12:30 Philly Fed Mfr Survey
12:30 US Jobless Claims
14:00 Eurozone Consumer Confidence
19:00 RBA Governor Lowe speech
22:00 Aus Commonwealth Bank PMIs
23:30 Japan National CPI

Friday October 22
06:00 UK Retail Sales
07:30 Germany Markit PMIs 
08:00 Eurozone Markit PMIs
08:30 UK Markit Mfr/Svcs PMIs
12:30 Canada Retail Sales (p-0.6%)
13:45 US Markit PMIs

Saturday, 28 August 2021

Week to Aug 27th

SPX & NDX ATH, Dollar falls after Jackson Hole
MY CALL THIS WEEK : BUY GBPAUD


LAST WEEK


In a week where strong action came on Monday’s ramp higher in stocks and oil, bad news/data was perceived as good for the market. Weak PMIs and Capital Goods reports globally dampened expectations for a taper announcement in the week’s main event at Jackson Hole and sent the SPX and NDX to new all-time highs. Powell’s Friday Jackson Hole speech confirmed that the inflation target had been met (no more talk of ‘transitory’) but that further job recovery was needed. This was more dovish than expected, and pushed stocks up further, and the dollar sharply down.

This meant that USD failed to hold last week’s break to new 2021 highs, posting an inside week. EURUSD spent the majority of the week above 1.17, also having an inside week as did the majority of currencies. Gold however broke out to a 3-week high. Yields surprisingly held up despite the dollar decline, and Oil fully reversed last week’s decline in line with the equity risk-on move.

Meanwhile, developments in New Zealand continue to be interesting, particularly as they are the G10 bank most advanced in normalizing rates. Assistant Governor Christian Hawkesby told Bloomberg that they were ready to raise rates last week and that policy decisions are not tightly linked to COVID and lockdowns. However, they held back on the hike as it would have been announced on the same day as the start of a national lockdown. 


WEEKLY PRICE MOVEMENT

The biggest mover this week was NKY, up 2.32%. The top forex mover was again AUDJPY this week  up 2.58%. Crypto was extremely flat, I cannot remember seeing weekly moves of less than 1%. FANGs were strong, following the risk-on NDX.

My CADJPY buy made 1.44% taking my year to date profit to 6.85% and 24/33 wins. This week I am buying GBPAUD as it is at support.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.


NEXT WEEK (all times are GMT)

Next week is the final week before the vacation season ends on Labor Day. A new month means of course NFP, and the estimate of 763k is in line with previous months. This print is crucial, as Fed Chair Powell indicated last week that with the inflation target met, only 
Otherwise, the week is packed with non-US data, including Eurozone and German inflation, Japanese and German Retail Sales, and PMIs from every territory including the important US ISM prints, both of which estimate slight pullbacks.


CALENDAR
High volatility items in bold

Monday August 30
23:50 Japan Retail Sales (Sun)
09:00 Eurozone Consumer/Industrial Confidence(Aug)
12:00 Germany CPI (e2.9% p3.1%)
12:30 Canada Current Account(Q2)
14:00 US Pending Home Sales
23:30 Japan Jobs/Unemployment

Tuesday August 31

01:00 China NBS PMIs (Services e50.8 p50.4)
01:00 Aus TD Securities Inflation
01:30 Aus Building Permits
07:55 Germany Unemployment
09:00 Eurozone CPI (YoY 2.5% p2.2%)
12:30 Canada Q2 Final GDP (e6.7% p5.6%)
13:00 US Housing/Home Price Indices
13:45 Chicago PMI
14:00 US Consumer Confidence
22:30 Aus AiG Performance of Mfg Index

Wednesday September 1 
01:30 Aus Q2 Final GDP (e1.6% p1.8%(
01:45 Caixin Mfr PMI
06:00 Germany Retail Sales (e3.2% p6.2%)
07:55 Germany Markit Mfr PMI
08:30 UK Markit Mfr PMI
09:00 Eurozone Unemployment
12:15 US ADP Employment Change (e575k p330k)
13:30 Canada Markit Mfr PMI
13:45 US Markit Mfr PMI
14:00 ISM Mfr PMI (e59.1 p59.5)

Thursday September 2
01:30 Aus Imports/Exports/TB (TB p-10.5B)
12:30 US Trade Balance
12:30 US Jobless Claims
12:30 Canada Trade Balance
14:00 US Factory Orders
22:30 Aus AiG Performance of Construction Index
23:00 Aus Commonwealth Bank Services PMI

Friday September 3
01:45 China Caixin Services PMI
07:55 Germany Markit Composite PMI
08:00 Eurozone Markit Composite PMI
09:00 Eurozone Retail Sales (p5.0%)
12:30 US NFP/AHE/UnEmp (e763k p943k)
13:45 US Markit Services PMI
13:45 US Markit Composite PMI
14:00 ISM Services PMI (e63.0 p64.1)

Sunday, 10 June 2018

Week to Jun 8th


Monday June 04
Equity markets gapped up and rose further on Monday, with RUT, and NDX and its top component AAPL hitting all-time highs, and Das concerns about Italy faded (Italian yields fell 28bp!), and despite the ongoing ‘trade war’ issues. JPY and Gold were down in line with rising equities (risk on). Commodity currencies AUD and CAD were up (despite a sharp 1.3% fall in oil, and a 2% fall in Brent) but cable was down. Despite this mixed picture, US 10-year yields were firmly up by 5bp to 2.94%

Tuesday June 05
Indices continued to rally on Tuesday, with another ATH for NDX and RUT, two indices considered to be less affected by trade wars. DAX was virtually flat on the day, after EUR rallied as tensions reduced in Italy, and FTSE and NKY were slightly down on a stronger pound and yen respectively, the former after the UK Markit Services PMI beat at 09:30. We can say that the USD trend was down as  Gold, Oil, and bond prices (inverse to yields) were up, however CAD and AUD were down, the latter after the RBA rate hold at 04:30.

Wednesday June 06
A third day of rally, this time across the board as all indices were up, more on momentum than news. This was despite further rallying of EUR and GBP, the former because ECB board member and BuBa President Weidmann that the central bank could end its bond buying programme before the end of 2018. German Bund yields rose 10bp, and even US yields put on 5bp, despite the day being weak for USD. AUD was strong after the GDP beat at 01:30, as was CAD after the Trade beat at 12:30. In fact JPY was the only currency to fall, leaving DXY down 0.1% on the day. Gold was flat, and Oil was down 0.7% after the EIA Stock miss at 14:30. Notably Brent was up 0.5%, widening the BNO-WTI spread.

Thursday June 07
marketseasonals.com
We were guided on Thursday by the weekday average chart for SPX provided by our friends at marketseasonals.com. This week the index performed almost exactly as the average, with NDX and RUT coming off their highs. The picture was not uniform, as SPX was flat, and DJIA was actually up, following a sharp 4.37% rise in MCD after restructuring plans.

DAX and FTSE came off even more sharply as EUR and GBP continued their upward path. This often happens with a few days of currency appreciation, the relevant index breakdown is delayed and then happens suddenly. The risk-off mood (Gold, JPY and bond prices up) was exacerbated by weekend G7 worries after Trump set out his position in a combative tweet. Also Italy is not yet right, Italian 10-year yields added 10bp today. When you add in the potential German car tariff Trump has been talking about, the DAX fade of 178 points (1.38%) was not surprising.

In forex, whilst EUR, GBP and JPY were up, AUD and CAD bucked the trend again and fell. Oil was up nearly 2%, erasing the previous day’s losses after reports that troubled OPEC member Venezuela was a month behind in its deliveries.

Friday June 08
After a poor start due to G7 tensions, US markets still managed to close green Friday, although as you might expect, non-US markets fared badly, as the potential victims in a trade war. Risk-off JPY and Gold were up. Currencies reflected the equities position, ie USD was up, and European currencies were down, as was AUD. Yields were up in line with the stronger dollar (or perhaps it’s vice versa). The surprise move of the day was CAD which despite the miss on jobs at 12:30, the Trump/Trudeau tension, and a volatile but ultimately down day in Oil, still managed to put on 0.35% (45 pips) to end the day and week green against the dollar.

Please note all figures and percentages given for daily movement on indices cover the entire cash and futures period in that day.


WEEKLY PRICE MOVEMENT

A low volatility week. USD was down across the board, but only slightly. The best forex trade was buying EUR, but even this yielded less than 1%. Indices were similarly flat, with SPX being the best trade. Cryptos followed suit with a second sub-10% week .

AUDUSD 0.7595 (+0.40%)
EURGBP 0.8771 (+0.46%)
EURUSD 1.1767 (+0.94%)
GBPUSD 1.3409 (+0.50%)
NZDUSD 0.7032 (+0.66%)
USDCAD 1.2926 (-0.20%)
USDJPY 109.51 (+0.02%)
DAX     12798 (+0.43%)
FTSE     7703 (-0.01%)
NIFTY   10757 (+0.57%)
NKY     22697 (+1.50%)
SPX   2779.02 (+1.74%)
GOLD  1298.72 (+0.38%)
OIL     65.49 (-0.30%)
BTCUSD   7641 (+1.58%)
ETHUSD 602.45 (+3.95%)

(Crypto prices are given as at 0000GMT Saturday, two hours after the other markets close.)


NEXT WEEK (all times are GMT)

A packed week ahead includes three rate decisions, four inflation prints, and two jobs reports, as well as plenty of opportunity for Trump-related black swans.

Monday June 11
Monday is likely to be dominated by the fallout from the G7 meeting. The British broker IG Markets runs a proprietary weekend market for DJIA, FTSE and DAX, and you can see that the 150-point DJIA drop indicates a gap down open. The only news today is UK Manufacturing and Production and Trade Balance. No Fed speakers today as the pre-FOMC purdah continues. Australian markets are closed for the Queen’s Birthday (but curiously the UK is not).

Tuesday Jun 12
Today is the possibly historic Trump-Kim summit. Anything positive here could deflect market trade war concerns, and of course the day will have finished in Singapore before New York opens. In the UK, the Brexit bill goes back to the House of Commons, and we have the key unemployment and average earnings figures. These will need to be good to keep up GBP momentum. Also out is US inflation, although this print is too close to FOMC to make any different to the rate decision.

Wednesday June 13
FOMC Rate Set day, and a rise from 1.75% to 2.00% is widely expected. No change is expected to the ‘dot-plot’, the summary of all voting members future intentions. A speech by Chair Powell is scheduled and his language will be watched closely. No let up in matters affecting GBP, with the all-important inflation figure this morning. Key is the ex-food and energy figure estimate at 2.1%.

Thursday June 14
The fourth print to affect GBP this week is Retail Sales, although this will have less effect as it is only an inflation proxy, and the real thing was the day before. Traders now have all the information they are going to get to predict whether the BoE will raise rates next week.

The main event of the day is the Euro rate decision, or more correctly the 13:30 press conference, where traders will be looking for ECB Pres Draghi to confirm Weidmann’s bullish remarks last week. German CPI earlier in the day will also have an effect on EUR although this rarely deviates from the estimate. The US Retail Sales print is less important because the same reason given above about the equivalent UK print.

Friday June 15
The third rate decision of the week comes from Japan, although this is less of an event—unless of course BoJ Gov Kuroda says something unexpected. In practice in a week like this, markets will still be digested the ECB and Feb positions. ECB CÅ“uré speaks at 08:45. Also today, the USTR to publish final list of $50bn Chinese imports subject to 25% tariff. This many affect certain sectors in US stocks.


CALENDAR (all times are GMT). High volatility items are in bold

Sun Jun 10
23:50 JPY Japan Machinery Orders

Mon Jun 11
08:30 GBP UK Manufacturing/Industrial Production

Tue Jun 12
01:00 USD Trump - Kim meeting
01:30 AUD Australia Home Loans/Investment Lending
02:00 CNY China FDI
08:30 GBP UK Unemployment/AHE/Claimant Count Change
09:00 EUR Germany ZEW Survey - Economic Sentiment/Current Situation
12:30 USD US CPI (est 2.2% prev 2.1%)
18:00 USD US Monthly Budget Statement
20:30 WTI API Stock

Wed Jun 13
00:00 EUR Eurogroup meeting (all day)
00:30 AUD Westpac Consumer Confidence
02:00 AUD RBA Governor Philip Lowe Speech
02:00 CNY China GDP (QoQ) (prev 1.4%)
08:30 GBP UK CPI/RPI/PPI (est 2.6% prev 2.5%)
09:00 EUR Industrial Production s.a. (MoM)
10:00 EUR DE10 Bond Auction
12:30 USD PPI ex Food & Energy (YoY)
15:30 WTI EIA Stock
18:00 USD Fed Rate Decision/Statement/Conference (est 2.00% prev 1.75%)

Thu Jun 14
00:00 EUR EcoFin Meeting (all day)
01:00 AUD Australia Consumer Inflation Expectation
01:30 AUD Australia NFP/Unemployment/Participation (est 18k prev 22.6k)
02:00 CNY China Retail Sales/Industrial Production (YoY)
06:00 EUR Germany CPI (est 2.2% prev 2.2%)
08:30 GBP UK Retail Sales
11:45 EUR ECB Rate Decision (est 0.0% prev 0.0%)
12:30 USD US Retail Sales (MoM) (est 0.4% prev 0.3%)
12:30 USD Jobless Claims
12:30 EUR ECB Statement and Press conference
22:30 NZD Business NZ PMI

Fri Jun 15 
02:00 JPY BoJ Rate Decision/Statement (est -0.1% prev -0.1%)
03:30 AUD RBA Assistant Governor Ellis Speech
04:00 JPY BoJ Press Conference (time approx)
09:00 EUR Eurozone CPI (est 1.9% prev 1.9%)
13:15 USD Industrial Production/Capacity Utilization
14:00 USD Michigan Consumer Sentiment Index
17:00 WTI Baker Hughes US Oil Rig Count

This report is published every week as an email by MatrixTrade.com - you can sign up to receive it here.