Showing posts with label NZDCAD. Show all posts

Sunday, 16 January 2022

Week to Jan 14th

CPI highest since 1982, Oil at 6-year closing high

MY CALL THIS WEEK : SELL NZDCAD 


THIS WEEK

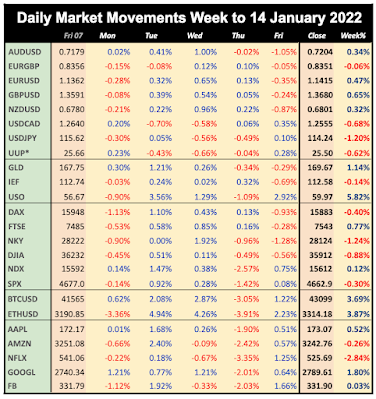
Markets were weak this week. There was an initial spike down and recovery into the Powell hearings (less hawkish than expected), and then the post-Santa sell-off moved into consolidation, with the 7% inflation print, the highest since 1982 spooking markets into giving back early gains, resulting in a flat week. The dollar fell all week, accelerated by the CPI figure, as did yields, although the latter was after the huge move up last week. Incidentally 10-year yields hit the 200-week moving average for the first time since May 2019. Oil made a 6-year closing high on Friday as last week's rally continued. Gold continued to consolidate, erasing half of last week's gains. Earnings on Friday had little effect, JPM only beat estimates with a one-off credit, and along with C the stock fell on Friday.


WEEKLY PRICE MOVEMENT


The biggest index mover was NKY, down 1.44%. The top forex mover was USDJPY down 1.20%. Bitcoin and Ethereum fall ended, and the pair were slightly up. FANG was variable, although less volatile than in previous weeks.


Last week's NZDCAD long position lost 0.26%, which when added to last week’s 0.33%, means I am ahead 0.07%, with 1/2 (50%) wins. This week I try buying NZDCAD again, as Oil is as a double-top.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.


NEXT WEEK


Monday is the MLK Day holiday in the US only, and earnings season starts properly on Tuesday with GS reporting before the bell, followed in the week by Dow giants PG and UNH, and first of the FANGs NFLX on Thursday after the bell. The week sees a raft of inflation reports from the UK, Canada, Germany, Eurozone and Japan on Wednesday and Thursday, and a rate decision on the yen. Friday is January's OpEx day.


CALENDAR  (all times are GMT)


Monday January 17

02:00 China GDP (QoQ e1.1% p0.9%)

02:00 China Retail Sales (e3.7% p3.9%)

15:30 BoC Business Outlook Survey


Tuesday January 18

03:00 BoJ Rate Decision/Statement (e-0.1% hold)

04:30 Japan Industrial Production

06:00 BoJ Press Conference

07:00 UK Claimant Count/UnEmp/AHE (UE e4.2% p4.2%)

10:00 Germany ZEW Sentiment Surveys


Wednesday January 19

07:00 UK CPI (p5.1%)

07:00 Germany CPI (e5.7% p5.7%)

13:30 US Building Permits/Housing Starts

13:30 Canada BoC CPI (e3.6% p3.6%)

14:15 BoE Gov Bailey Speech

23:30 Aus Westpac Consumer Confidence

23:50 Japan Imports/Exports/TB


Thursday January 20

00:30 Aus NFP/UnEmp (UE e4.5% p4.6%)

01:30 PBoC Rate Decision/Statement (e3.8% hold)

07:00 Germany PPI

10:00 Eurozone CPI

12:30 ECB MPC Minutes

13:30 US Jobless Claims

13:30 Philly Fed Mfr Survey

23:30 Japan National CPI

23:50 BoJ MPC Minutes


Friday January 21

07:00 UK Retail Sales

13:30 Canada Retail Sales (e1.0% p1.6%)

15:00 Eurozone Consumer Confidence

Sunday, 9 January 2022

Week to Jan 7th

Rally collapses on hawkish Fed, OPEC holds Oil up.
MY CALL THIS WEEK : SELL NZDCAD


THIS WEEK


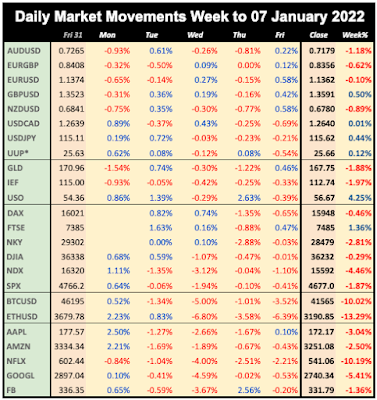
A new year, and stocks initially continued upwards this week, but were halted by hawkish remarks in the Fed minutes, which depressed indices generally and tech stocks particularly, already sensitive to omicron COVID, reflected in the US ISM PMI miss. The weak NFP (199k vs 400k) did not help. Naturally yields rallied on the Fed, hitting a 9-month high, although notably the effect was not seen in the dollar, except against commodity currencies AUD and NZD. (CAD was protected by a rally in Oil caused by OPEC sticking to their production schedule). Gold fell in line with yields.


WEEKLY PRICE MOVEMENT

The biggest index mover was NDX, down 4.46%, much more than the other indices, showing the effect of the Fed remarks. The top forex mover was AUDJPY down 1.68%. Bitcoin and Ethereum were well down again, and FANG performed in line with NDX.

My total forex profit for 2021 was 6.49% with 36/52 wins. Last week’s CADJPY short made 0.33%, a win for the first week in 2022. This week I will buy NZDCAD.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.


NEXT WEEK


The most important macro print this week is US inflation on Wednesday. The estimate of 5.4% is the highest for 30 years. Earnings season starts this week, but only just, with JPM (as always), C, and WFC reporting on Friday. Fed Chair Powell has his second term confirmation hearing, otherwise we have Chinese inflation (only 1.8%!), and US and Australian Retail Sales.


CALENDAR  (all times are GMT)


Monday January 10

00:00 Aus TD Securities Inflation (time approx.)

00:30 Aus Building Permits

10:00 Eurozone Unemployment Rate(Nov)


Tuesday January 11

00:30 Aus Imports/Exports/TB (TB e10.6B p-11.2B)

00:30 Aus Retail Sales (e4% p4.9%)

15:00 Fed Chair Powell testifies

23:50 Japan Current Account


Wednesday January 12

00:00 Aus HIA New Home Sales (time approx.)

01:30 China CPI (e1.8% p2.3%)

10:00 Eurozone Industrial Production

13:30 US CPI (Core YoY e5.4% p4.9%)

19:00 US Monthly Budget Statement


Thursday January 13

00:00 Aus Consumer Inflation Expectations

02:00 China Imports/Exports/TB

13:30 US Jobless Claims

13:30 US PPI


Friday January 14

07:00 UK GDP (MoM)

07:00 UK Ind/Mfr Production

13:30 US Retail Sales (Control Group Dec p-0.1%)

15:00 Michigan CSI (e70.6 p70.6)

Sunday, 24 October 2021

Week to Oct 15th

Earnings week strong start, CPI beat, Taper looming
MY CALL THIS WEEK : BUY NZDCAD


LAST WEEK


After a lacklustre start, the strong earnings from JPM on Wednesday and the US CPI beat triggered a two-day rally as the other banks also easily beat estimates, with a particularly strong showing from GS. A Fed taper announcement in November still looks likely and the Fed’s Bostic admitted price increases “will not be brief.” The market’s reaction to all this was somewhat contra to the norm, reversing recent strength in the USD and yields, accompanied by large rallies in stocks and metals.


WEEKLY PRICE MOVEMENT

The biggest mover this week was NKY, up 3.64%. The top forex mover was NZDJPY this week, up an amazing 4.13%, a major forex magnitude not seen for years. Bitcoin and ETH were strongly up again, and FANGs were once again variable.

Another bad week, losing 2.69% on my CADJPY short, taking my year to date profit to 3.09%, half of what it was two weeks ago, and 27/40 wins. This week I am buying NZDCAD again.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.

 
NEXT WEEK (all times are GMT)

Earnings season continues next week, with a wider range than the banks last week. As always first FANG to report is NFLX on Tuesday, with NDX giants TSLA and INTC later in the week. Dow giants IBM, JNJ and PG also report. From China, we have GDP, Retail Sales and a rate decision, as well as an Evergrande debt deadline on Tuesday. There are inflation reports from the UK and Canada, but otherwise little of significance in sovereign scheduled data. The first Bitcoin ETF is launched on Monday.

 
CALENDAR (High volatility items in bold)

Monday October 18
02:00 China Q3 GDP (YoY e5.2% p7.9%)
02:00 China Retail Sales (YoY e3.3% p2.5%)
09:30 Fed Quarles speech
15:40 BoC Lane speech
18:00 US Monthly Budget Statement

Tuesday October 19
00:30 RBA Meeting Minutes
12:30 US Building Permits/Housing Starts
17:15 Fed Bowman speech
19:00 Fed Waller speech
23:30 Aus Westpac Leading Index
23:50 Japan Imports/Exports/TB

Wednesday October 20
01:30 PBoC Rate Decision/Statement (e3.85% hold)
06:00 UK CPI (p3.2%)
09:00 Eurozone CPI
10:30 Germany 10Y Bond Auction (time approx.)
12:30 Canada BoC CPI (p3.5%)
17:00 Fed Quarles speech
18:00 Fed Beige Book

Thursday October 21
00:30 Aus NAB Business Confidence
12:30 Philly Fed Mfr Survey
12:30 US Jobless Claims
14:00 Eurozone Consumer Confidence
19:00 RBA Governor Lowe speech
22:00 Aus Commonwealth Bank PMIs
23:30 Japan National CPI

Friday October 22
06:00 UK Retail Sales
07:30 Germany Markit PMIs 
08:00 Eurozone Markit PMIs
08:30 UK Markit Mfr/Svcs PMIs
12:30 Canada Retail Sales (p-0.6%)
13:45 US Markit PMIs

Sunday, 6 December 2020

Week to Dec 4th

Vaccine rally continues, NFP Miss good for QE, USD hits 2.5yr low
MY CALL THIS WEEK : BUY NZDCAD


We saw a raft of positive news this week including bi-partisan progress on the stimulus figure, OPEC production level agreements being lower than estimated, and of course, news of the rollout of the three viruses (four if you include the Russian one). Also President Trump appears to have gone quiet on the election, easing the Biden transition.

This resulted in all three US indices rallying to new highs, and the safe haven dollar plunging to lows last seen in April 2018. The drop was uniform, with EUR, GBP, NZD and CAD all making two-and-a-half year highs, and caused another Gold rally. Confirming the positive trend, the yield curve (US10Y-US02Y yields) rose to 0.821%, its highest level since October 2017.


Slight blips such as a delay in the Pfizer rollout, and an NFP miss were shrugged off in the larger positive picture, aided of course by seasonal sentiment.


The gains were not shared by DAX which is underperforming, partly due to EUR strength, but also the huge German second COVID wave being seen not only in cases (understandable as there is more testing), but more worryingly in deaths, meaning unlike, say the US, the infection locus has not moved to a safe cohort (younger people).


The left-hand chart shows the issue by comparing the performance of DAX (in USD, to remove the EUR effect) versus, ie divided by SPX against the number of Germany cases. The right-hand chart goes one further and compares the German case/fatality ratio against that of the US, which removes any testing density variation. You can see the correlation which goes some way to explaining DAX underperformance.


Next week is lighter on data as we move into the holiday season proper. The key events are the ECB rate decision and presser on Thursday, and an FDA meeting on the same day concerning approval of the PFE and MRNA vaccines (these have already been approved in the UK). This is followed by an EU banking and capital markets summit on Friday. Traders will be looking for the ECB view on the exchange rate, plus of course any further COVID news. Scheduled macro data is unlikely to be as important, unless, as always, there is a big surprise.


Mon Nov 30
As we predicted last week, there was some profit-taking today after a very strong November, which saw, for example the FTSE 100’s best month for 31 years. SPX fell 0.5% and other indices followed suit. Oil was down in line. After initially continuing last week’s decline, the dollar made a late rally to close 0.2% up, meaning Gold was down. Bonds were flat on the day.


Tuesday December 1

A beat on China PMIs set the tone for a strong opening to the month, with all indices up, and NDX outperforming. The tech index was up 1.52%. Copper, a forward indicator of tech activity (as it is required for all electrical cabling) hit $7,719 per tonne, although Oil fell ahead of the OPEC meeting. The safe haven dollar fell sharply, hitting a new 30-month low, especially after the Powell testimony (nothing new) and the ISM PMI miss. Bonds were down in line, and Gold rose on the weaker dollar.


Wednesday December 2

Markets took a breather today after the ADP miss, and were generally flat except for FTSE which rallied 1.23% after a 1c fall in GBP due to Brexit no-deal concerns. The bond market was more active, with a 6bp rise in the 10-year yield, and a rise in the yield curve (US10Y-US02Y) to 78 points, the highest level for three years, as investors sold Bonds fearing inflation after the COVID stimulus package, which edged closer to reality today with some bipartisan support for a $908B package. This inevitably pushed USD down further against all currencies (except GBP and CAD), and Gold. Oil recovered after yesterday’s drop on news that OPEC would cut production.


Thursday December 3

Another flat day for SPX and NDX, although DJI managed a 0.29% rise, although SPX hit a new ATH earlier in the day, but pulled back on news that PFE vaccine production levels may be restricted. Yields (inverse to bonds) pulled back slightly after yesterday’s strong move. Oil rose again on the OPEC news. The dollar continued to hit new lows, with JPY particularly strong after being even weaker than USD all week (in line with the stocks rally). The greenback was down across the board, including Gold.


Friday December 4

The NFP report at 245k was worryingly below the 520k estimate, but the markets saw this as “bad is good”, meaning that the prospect of QE taper is less likely. As you would expect therefore, markets rose again, with SPX adding 0.88%, and of course the dollar rose (including against Gold) for the same reason. Only CAD was up, following the Canadian NFP beat. Bonds were again down in line, with yields briefly touching 0.984, an eight-month high.


WEEKLY PRICE MOVEMENT

The strongest index this week was FTSE, reflecting a slightly weaker GBP. The top forex mover was CADJPY up 1.69%. Cryptos recovered after last week’s sharp fall, as BTC continues to flirt with ATHs. FANGS were generally in line with NDX with AAPL outperforming.


This week I am buying NZDCAD, as both currencies seem to be at pivots. I would trade the major (dollar) pairs, but it’s hard to say whether the dollar will recover or fall further. At the current level of 90.70, main support is still about 1c lower. Last week's GBPJPY buy was up 1%, taking my total to 8.01% (22 wins out of 40)


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.


NEXT WEEK (all times are GMT)

(Calendar High volatility items are in bold)


Next week is lighter on data as we move into the holiday season proper. The key events are in Europe with the ECB rate decision and presser on Thursday, and an FDA meeting on the same day concerning approval of the PFE and MRNA vaccines (these have already been approved in the UK). This is followed by an EU banking and capital markets summit on Friday. Traders will be looking for the ECB view on the exchange rate, plus of course any further COVID news. Scheduled macro data is unlikely to be as important, unless, as always, there is a big surprise.


  • ECB week
  • FDA vaccine meeting
  • EU capital markets summit
  • China, US, Germany inflation


Monday December 7

China’s trade balance may set the tone for the day, although the important news comes later in the week.


22:05 RBA Governor Lowe speech (Sunday)

02:00 China Imports/Exports/TB

07:00 Germany Industrial Production

15:00 Canada Ivey PMI

23:50 Japan Q3 Final GDP (e5.0% p5.0%)


Tuesday December 8

Another slow data day. Markets are closed in Spain, Italy, Portugal and several South American countries for the Feast of the Immaculate Conception.


10:00 Eurozone ZEW Survey – Economic Sentiment

10:00 Eurozone Q3 Final s.a. GDP (e12.6% p12.6%)

10:00 Germany ZEW Sentiment Surveys

13:30 US Nonfarm Productivity/Unit Labor Costs

23:30 Aus Westpac Consumer Confidence


Wednesday December 9

A light data day, with the BoC decision as the main news.


01:30 China CPI (YoY e0.0% p0.5%)

07:00 Germany TB

15:00 BoC Rate Decision/Statement (e0.25% hold)


Thursday December 10

The FDA meet today and tomorrow to discuss the approval of the PFE and MRNA vaccines. The EU also meet to discuss COVID.


00:00 Aus Consumer Inflation Expectations

07:00 UK Manufacturing/Industrial Production

07:00 UK GDP MoM

12:45 ECB Rate Decision/Statement (e0% hold)

13:30 US CPI (Core YoY e1.8% p1.6%)

13:30 US Jobless Claims

13:30 ECB President Lagarde Presser

19:00 US Monthly Budget Statement


Friday December 11

There is an EU leaders summit today on banking and capital markets. Any surprise takeaways will no doubt affect EUR and thus DAX.


07:00 Germany CPI (YoY e-0.5% p-0.7%)

13:30 US PPI

15:00 Michigan Prelim CSI (e77 p76.9)