Showing posts with label Huawei. Show all posts

Sunday, 26 May 2019

Week to May 24th


Google/Huawei trade war intensification, USD hits two-year high, UK PM May resigns


Mon May 20
The trade dispute decline carried on today, as Google announced the termination of Android operating system supply to Huawei. SPX was down 0.7% and NDX shedded double that. A similar story was seen in DAX, FTSE and NKY. Australian and Indian markets were up sharply, in both cases following the surprise Conservative election wins.

The dollar, however, was flat against most currencies and Gold, with only AUD making a sharp move up. Oil and Bonds (inverse to yields) were slightly down.

Tuesday May 21
A moderate Turnaround Tuesday on equities saw most indices recover their Monday losses, triggered by a a three-month reprieve for Huawei.

The dollar was up again, but only by 0.1%. Most currencies were sluggish, but GBP spiked sharply on news that PM May was offering a second Brexit referendum to MPs, if they would vote for her deal. It quickly retreated when it was clear they would not. Similarly AUD gave up all its election gains in short order after the RBA Minutes and Governor’s speech. Gold was down in line with equity reversal, and Oil and Bonds declined slightly again.

Wednesday May 22
Tuesday’s rally was short-lived and stocks continued their trade war inspired downward path again today, with all markets giving up ground. For once the effect was strongest in the US, with only slight moves down in Europe.

DXY added 0.1% against most currencies to briefly touch a two-year high of 98.37.  Brexit-troubled GBP was notably down, but balanced by an appreciation in safe haven JPY. Bonds were also up in line, although Gold was flat. Oil followed equities down after the EIA miss at 1430. The FOMC minutes offered no surprises and markets hardly moved at the 1900 release.

Thursday May 23
Maybe the failure of the Fed to give rate cut encouragement, or just technical downward momentum, but today saw a sharper fall in equities, with SPX down 1.2% and NDX 1.6%. The mood was the same in Europe and Japan, with all indices registering declines of over 1%. The further decline of the German Manufacturing PMI to a new low of 44.3 at 0730 did not help. A clear risk-off mood saw Bonds, Gold and JPY sharply up, with 10-year yields up 8.1bp on the day, and a near 5% drop in Oil.

There was a sharp turn up in EUR, after it briefly hit a two-year low, following the ECB MPC Minutes  are 1230, and disappointing US Market PMIs, but as the move was seen across most currencies, it was probably a reaction to the previous day’s DXY high. All currencies were up (GBP barely so), and DXY lost 0.24%.

Friday May 24
Friday saw the resignation of UK PM May, and both GBP and FTSE rose. Markets may hate Brexit, but they hate uncertainty more (although the strong UK Retail Sales beat at 0830 may have helped)

The key US print of the day, Durable Goods/Non-Defence Capital Goods at 1230 missed, but SPX also rose. But overall markets recovered less than half of Thursday’s fade so it was probably only a technical move into the long Memorial Day weekend. Oil’s move was similar.

The dollar continued to retreat from its high, with DXY down 0.25% and all currencies up, and a particularly strong AUD, which returned to Monday’s election high. Gold and yields were flat.


WEEKLY PRICE MOVEMENT
The standout equity performer was the Indian NIFTY after the surprise BJP (Modi) win. Otherwise the biggest mover would have been risk barometer NDX. For the fourth week in a row, GBPJPY was the biggest mover, although only down 0.74% this week. Cryptos continued their advance, with BTC closing about $8000 for the first time since July 2018. As last week, AAPL underperformed the other FANGs.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on UUP. The equity and index prices are now based on the cash close each day.


NEXT WEEK (all times are GMT)
(Calendar High volatility items are in bold)
  • Four day week
  • Plenty of CB speakers
  • Currency manipulation report due
  • Canada in focus

Monday May 27
Markets in the US and UK are closed today, for Memorial Day and Spring Bank Holiday respectively. KHC report earnings. The results of the European Parliamentary Elections will be announced, with a large UK vote (largely seen as a ‘second Brexit referendum proxy’) expected to go to the Brexit Party, but by how much may affect markets. President Trump is in Japan today and tomorrow.

11:45 EUR ECB Lautenschläger speech (Sunday)
03:00 JPY BoJ Governor Kuroda speech
05:00 JPY Japan Leading Economic Index

Tuesday May 28
The US Commerce department ‘currency manipulation’ study is due to be published today. There is a rate decision on HUF.

05:45 CHF Switzerland 19Q1 GDP
06:00 EUR Germany Gfk Consumer Confidence Survey
09:00 EUR Eurozone Business Climate
13:00 USD US S&P/Case-Shiller Home Price Indices (YoY)
14:00 USD US Consumer Confidence
20:00 NZD RBNZ Financial Stability Report

Wednesday May 29
The BoC is expected to hold, although unlike the US, the risks are to the hawkish side, although Canadian data has been poor of late.

00:00 JPY BoJ Governor Kuroda speech
01:00 NZD RBNZ Governor Orr speech
01:00 AUD Aus HIA New Home Sales (time approx)
07:55 EUR Germany Unemployment Rate/Change
14:00 CAD BoC Rate Decision/Statement (e1.75% hold)
22:45 NZD NZ Building Permits s.a. (MoM)

Thursday May 30
Markets are closed today in Germany and much of Europe (although not the UK) for Ascension Day. US VP Pence meets with Canadian PM Trudeau to discuss USMCA ratification in the Canadian parliament. There are rate decisions on KRW, TRY and COP.

01:30 AUD Aus Building Permits (MoM)
12:30 CAD Canada Current Account
12:30 USD US Jobless Claims
12:30 USD US 19Q1 GDP/PCE QoQ (prelim)(GDP e3.1% p3.2%)
14:00 USD US Pending Home Sales
15:00 WTI EIA Oil Stock
16:00 USD Fed Vice Chair Clarida speech
18:15 CAD BoC Wilkins speech
21:30 WTI API Oil Stock
23:01 GBP UK GfK Consumer Confidence
23:30 JPY Japan Jobs/Applicants, Unemployment
23:50 JPY Tokyo CPI (e1.2% p1.3%)
23:50 JPY Japan Industrial Production (YoY)
23:50 JPY Japan Retail Sales

Friday May 31
The final day of the month may see some rebalancing volatility. The Canadian GDP print is final, not preliminary. There is a rate decision on BGN.

01:00 CNY China NBS PMIs
06:00 EUR Germany Retail Sales (MoM)
08:30 GBP UK Consumer Credit/Mortgage Approvals
12:00 EUR Germany CPI (e1.5% p2.1%)
12:30 USD Personal Spending/PCE YoY & MoM
12:30 CAD Canada GDP (QoQ e1.2% p0.4%)
13:45 USD Chicago PMI
14:00 USD Michigan CSI (e100.00 p102.4)


This report is published every week as an email by MatrixTrade.com - you can sign up to receive it here. This blog is supported solely by advertising, so if any of the ads interest you, please click on them. If you want notification when the blog is updated, please follow me on Twitter, Facebook, Stocktwits, TradingView or Linkedin (all open in separate windows). Details of how I compile the report are here.


Saturday, 8 December 2018

Week to Dec 7th


Monday Dec 03
Markets seized on remarks following Trump/Xi meeting at the G20 Conference in Buenos Aires as a softening of the trade war. The US said they would suspend new trade tariffs for 90 days. Equity markets gapped up. The SPX added 1.5%, its largest weekend gap up in 18 years. The gains were however eroded throughout the European and US sessions although all indices still posted a green candle, albeit a doji. The other big news of the day (which also helped equities) was Russia confirming it would co-operate with Saudi Arabia on production cuts. The black gold added 4.82%, its best day since Jun 22nd. Also there were more encouraging reports from Italy about budget compromise, and BTP yields fell.

However, around 1800, the US 3-year bond yield fell below that of the 5-year note. Although most focus is on the 2 and 10 year bonds, this inversion was seen as a warning sign by markets. The two times this happened were in 2001 and 2006, shortly before bear markets emerged. This is what quashed what would otherwise have been a very positive day and start to the traditionally strong ‘Santa Rally’ month of December.

DXY fell 0.2% on the day. It would have been more except that GBP, after a good start, fell sharply on concerns that British PM May will not get her Brexit deal through Parliament. All other currencies were up (JPY was nearly flat, being pulled between risk-on equity strength and the weaker dollar). Gold was up and 10-year yields were down in line with the weaker dollar.

Tuesday December 04
Equity indices had a firm Turnaround Tuesday, as SPX fell 3.2%, its worst day for two months. This was of course partly due to the large ‘air pocket’ from the record weekend gap up, and concerns about the reality of the thaw in trade relations (in the absence of follow-up news), but the main driver was that shortly after the markets closed on Monday, the 2 year/5 year curve also inverted in the futures market, and this was confirmed when the cash markets opened. Note that all yields are now falling, it is that longer term yields are falling faster than shorter term ones. The main worry is the that the 10y/2y yield will invert. At +0.128 it is already the lowest since June 2007, when SPX topped four months later, and then went on to lose 57%. Also the SPX made a ‘death cross’ (where the 50-day moving average falls below the 200-day for the first time since 

Other indices also fell hard, but the FTSE fell the least, due to a fall in GBP after the British government was found in contempt of Parliament for not publishing Brexit legal advice (which confirmed that the EU had sole control of the ‘’backstop’ exit). This was after an earlier rise like the day before. There was similar pattern in EUR (also affected by Brexit of course), and CAD and AUD were also down, but a sharp 0.8% appreciation in JPY as equities fell left DXY more or less flat. Oil was slightly down, and Gold slightly up in line with JPY. 10-year yields fell sharply, in line with the short-term inversions, giving up 8bp on the day.

Wednesday December 05
US equity and bond markets were closed today for the funeral of President GHW Bush. The day’s economic releases were also postponed, and SPX futures actually managed a small gain. DAX was flat on the reduced volume, and FTSE was slightly down as GBP rose after the ECJ confirmation that Brexit could be reversed by a simple withdrawal of the Article 50 notice, meaning ‘no Brexit’ is actually possible. Needless to say this is along way from a Brexit softening, and for the third day in a row, a spike up faded.

DXY was flat again today, with advances in EUR and GBP being balance by a weaker JPY and a sharp drop in CAD to an 18-month low on dovish remarks (no inflation, no rate hikes) from the BoC following the rate hold at 15:00.  The loonie instantly spiked down 100 pips (0.77%). AUD (not part of DXY) was also sharply down after the substantial miss (2.8% vs 3.3%) on GDP. Gold was flat, and Oil managed a small 0.6% advance, with price action similar to Tuesday. The bond markets were closed.

Thursday December 06
Today the CFO (and daughter of the CEO) of controversial Chinese comms vendor Huawei was arrested in Canada under US orders on potential Iran sanctions violations, causing semiconductor ETF SOXX to gap down 2.8%, although it later partly recovered. SPX gapped down 1.35%. All indices followed a similar pattern, recovering but still ending the day in the red. At the cash close, DAX, FTSE and STOXX were over 3% down, at two-year lows. STOXX had its worst day since June 2016. There was a slight improvement in the yield curve, 2 year paper fell 5bp, whereas the 10 year bellwether only fell by 4bp, which may have mitigated the US losses.

Another sentiment factor was the US trade balance print came in as a miss (-$55.5Bn vs -$54.9Bn). This release is not normally significant, but the figure was marginally worse that the Feb 18 print ($54.9Bn), before the trade war started, and thus the worst imbalance since the 2008 crisis. The implication of course is that Trump’s tariffs were supposed to narrow the trade gap, yet it has been getting worse every month since May this year.

We finally saw some dollar movement today, with DXY down 0.23% after a strong showing from EUR and GBP, following rises in German and British bond prices, and of course JPY in line with equity fade. Risk currency AUD however was down for a second day. EMs also suffered with ZAR, RUB and BRL notably down. Oil also fell (2.3%) despite the EIA beat at 15:30, but Gold was flat, as was CAD, holding yesterday’s move (despite misses on Trade Balance and Ivey PMI) in anticipation of the simultaneous US/Canadian NFP reports.

Friday December 07
The relief today in the Oil market which leapt 4.85% on OPEC cuts confirmation was short-lived, and it ended the day a mere 0.81% up. The equity sentiment was dampened further by reports from Trump advisor Navarro (remember him, the China hawk) saying the US would definitely push ahead with the tariff increased if Washington and Beijing could not agree a truce in the 90-day period mentioned above. The 10yr/2yr bond yield narrowed by 2bp, as the shorter note faded 4bp. Then to add to this, US NFP missed at 155k vs 205k estimated, although the AHE figure, which we have said many times is more important, printed in line with the estimate of 3.1% YoY (reminder: US YoY CPI is 2.1%). As you would expect markets fell substantially, with SPX giving up 2.3% to post its worst week since March, and its worst December Friday since 1932. AAPL filled the May gap, and moved into negative territory for the year as did DJIA. DAX and NKY followed suit downward, with only FTSE trimming losses to 0.35% on weaker GBP and stronger Oil.

DXY was down 1% on the day, as EUR advanced despite the Eurozone GDP miss at 10:00 (of course Eurozone stats are usually priced in, as the individual countries report beforehand). GBP followed the pattern it has done all week, only this time the fade of the rally took an extra day. These near-100 pip moves in sterling are related to the constant flow of good and bad Brexit news, more pronounced since BoE Governor Carney firmly linked the rate hike path to the degree of soft or hard exit. JPY and CAD hardly moved, but the winner of the day was CAD, which fully retraced (as it often does) Wednesday’s fall after the stellar jobs report (94.1k vs 11k, 850% over estimate, and equivalent to 847k in US terms, adjusting for population). Canadian unemployment also beat, and CAD instantly reversed the 100 pips it (instantly) lost on Wednesday. It was helped also by the Oil move, but being a risk currency like AUD, there are still pressures against it. This kind of move happens a lot with USDCAD and there is not usually a stop-hunting reverse spike, nor is there a quick reversal, which makes this event very easy to trade. Gold was up $11 (0.88%) in line with both the weaker dollar and a week of risk off, to finish at a five-month high of $1,248.

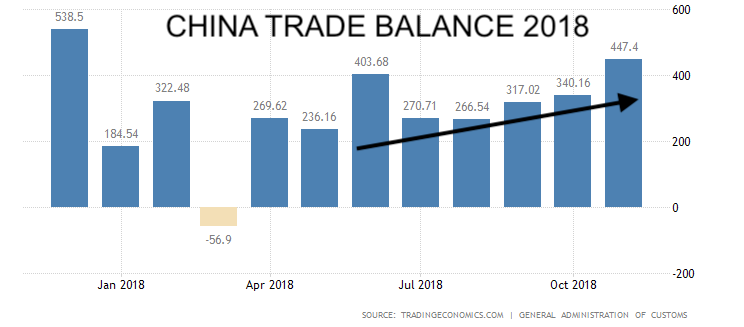
On Saturday, China released a stellar trade balance beat ($44.74Bn vs $34Bn est), a new 2018 high. The trade balance has been increasing steadily over the last five months. Taken together with the US decline over this period, it makes you wonder how effective the Trump tariffs are.

Please note all figures and percentages given for daily movement on indices cover the entire cash and futures period in that day.

WEEKLY PRICE MOVEMENT

No Santa Rally yet! After last week’s brief respite, markets continued their slide down, with NKY the worst performer. A much quieter week for USD saw both gains and losses (The strong Euro resulted in a 0.43% softening of DXY). Selling AUDJPY would have netted you 2.16%. Cryptos continued to plunge to new 15-month lows. NDX gave up 4.76%, and some of the FAANGs did even worse. Outside cryptos, shorting NFLX (which still has a PE ratio of 69.3) was the best trade of the week.

AUDUSD 0.7201 (-1.57%)
EURGBP 0.8941 (+0.82%)
EURUSD 1.1382 (+0.57%)
GBPUSD 1.2731 (-0.24%)
NZDUSD 0.6876 (+0.01%)
USDCAD 1.3324 (+0.21%)
USDJPY 112.73 (-0.69%)
DAX     10717 (-5.45%)
FTSE     6766 (-3.65%)
NIFTY   10694 (-1.68%)
NKY     21353 (-4.73%)
SPX    2636.8 (-4.57%)
GOLD  1248.59 (+2.14%)
OIL     52.12 (+2.50%)
BTCUSD   3459 (-14.36%)
ETHUSD  94.95 (-16.48%)
FB     137.42 (-2.27%)
AAPL   168.49 (-5.65%)
AMZN  1629.13 (-3.61%)
NFLX   265.14 (-7.34%)
GOOGL 1046.58 (-5.68%)

(Crypto prices are given as at 0000GMT Saturday, after the other markets close.)

NEXT WEEK (all times are GMT)
(Calendar High volatility items are in bold). 

Monday December 10
There may be some GBP movement following Sunday’s Brexit debate between British PM May and opposition leader Corbyn. The formal election of Annegret Kamp-Karrenbauer to replace Angela Merkel as CDU party leader takes place. The UK GDP print will probably be ignored as all GBP traders care about at the moment is Brexit. There is also Chinese trade balance data released at weekend.

01:30 CNY China CPI/PPI (Sunday)
21:30 AUD RBA Asst Gov Kent Speech (Sunday)
00:30 AUD Aus Home Loans/Investment Lending for Homes
07:00 EUR Germany Current Account n.s.a.
09:30 GBP UK Industrial/Manufacturing Production
09:30 GBP UK GDP (MoM) (est 0.1% prev 0.0%)
13:15 CAD Canada Housing Starts s.a (YoY)

Tuesday December 11
All eyes on the UK today for the crucial Parliamentary vote on Brexit around 1900. The British Conservative government, you will remember do not have an overall majority after the disastrous June 2017 election, and it is widely expected their motion to pass the current plan will fail (a surprise win would boost GBP hugely). This could lead to PM May resigning (to be replaced by a hard Brexiteer?), a successful vote of no confidence and subsequent snap election, or a second referendum, which in turn does or doesn’t have ‘cancel Brexit’ as an option. All options will have a strong effect on markets. 

00:30 AUD Aus House Price Index (QoQ)
09:30 GBP UK Average Earnings (exc Bonus est 3.2% prev 3.2%)
09:30 GBP UK Claimant Count Change/Unemployment 
10:00 EUR Germany ZEW Economic Sentiment/Current Situation
21:30 WTI API Stock
23:30 AUD Aus Westpac Consumer Confidence

Wednesday December 12
The US CPI print at 1330 is the most important release of the day. A slight uptick is expected, but anything to the downside could affect next week’s anticipated hike, and therefore USD pricing. The Fedwatch likelihood of next week’s hike is already down to 71% from 82.7% on Nov 30th, so a hold is a definite possibility. There are also CPI report from Sweden, India, and South Africa, and rate decisions on PHP and BRL. Mexican markets are closed.

10:00 EUR Eurozone Industrial Production s.a. (MoM)
13:30 USD US CPI (Core est 2.2% prev 2.1%)
15:00 USD Fed Chair Powell Speech
15:30 WTI EIA Stock
19:00 USD US Monthly Budget Statement

Thursday December 13
Back to Europe today for German inflation and then the all-important ECB statement at 1245 followed by the usual press conference 45 minutes later. This month is when the bank is due to end its three-year €2,600Bn QE. Commentators are however leaning towards a dovish rhetoric from ECB President Draghi. There are rate decisions on TRY, PHP and PEN.

00:01 GBP UK RICS Housing Price Balance
00:30 AUD RBA Bulletin
01:00 AUD Aus Consumer Inflation Expectation
07:00 EUR Germany CPI
12:45 EUR ECB Rate Decision/Statement (est 0% prev 0%)
13:30 EUR ECB Pres Draghi Presser
13:30 USD US Jobless Claims
13:30 CAD Canada New Housing Price Index
21:30 NZD Business NZ PMI

Friday December 14
The US retail sales figures today are less important, as this print is a CPI proxy, and the actual inflation figure was published two days earlier. Today is the last session of the US Senate in 2018. ECB Lautenschläger speaks at 0930. There is a rate decision in Russia, a 25bp hike is expected. Turkey is due to get a new Fitch rating today.

00:00 EUR EcoFin Meeting (all day)
02:00 CNY China Retail Sales/Industrial Production
08:30 EUR Germany Markit PMIs
09:00 EUR Eurozone Markit PMIs
10:00 EUR Eurozone Labour cost
13:30 USD US Retail Sales MoM (Control Group est 0.4% prev 0.3%)
14:15 USD US Capacity Utilization/Industrial Production
14:45 USD Markit PMIs
18:00 WTI Baker Hughes Rig Count