Showing posts with label Iran. Show all posts

Sunday, 12 January 2020

Week to Jan 10th


Iran retaliation muted, DJIA 29000, NFP miss halts rally

Mon Jan 6
Markets were on edge in the early part of today, continuing the sentiment from Friday, and awaiting Iran’s response to the assassination of their top general last week. However, although DAX and FTSE closed down, by the close, sentiment had recovered sufficiently to post a positive day for US indices and non-US futures.  The dollar was initially sold off in London for the same reason, and did not recover by the end of the day. Gold, JPY and Bonds were of course up, but Oil faded slightly, giving back some of its huge gain on the initial action.


Tuesday January 7
Another down day for the same reasons as Monday, waiting for Iran, with all indices in the red. The dollar stayed a recovery, maybe in response to Trade Balance (1330) and Services PMI (1500) beats, which added to the beats in yesterday’s Manufacturing PMIs. However, the risk-off mood remained, with JPY, bonds and Gold all up. At the very end of the day, the Iranians did strike back, which cause a sudden move in the markets, in the risk off direction, which you can see around midnight.


Wednesday January 8
As relief unfolded that the Iranian response to the Solemaini killing was relatively muted, a few missiles at a US base with apparently no casualties, and a statement from Iran that their response was concluded, markets rallied, and risk assets and Oil fell sharply, erasing completely last Thursday’s gains. The dollar was up across the board (other than with AUD and NZD were flat/slightly up) as well, a clear change in mood, not doubt helped by the substantial beat (202k vs 150k) in the ADP jobs report.


Thursday January 9
The Iran relief factor continued into a second day, despite a series of economic misses, particularly the Chinese inflation print at 0130. All indices everywhere were up, as again was the dollar across the board. Gold was down in line, but after a 10bp move up on Wednesday, yields pulled back slightly. Oil was down although the move was much shallower than on Wednesday. Late in the day, without any fanfare, the UK finally passed its long-awaited Brexit bill.


Friday January 10
The NFP print today disappointed, coming in at 145k against the modest estimate of 164k. Futures had made a new ATH of 3288 just before the release, and then SPX (and all other indices) faded gently for the rest of the day, although DJIA briefly made a new round point high of 29000. The dollar was also down today (with only GBP going lower), and in line with equities, the haven trio were all up. Oil hardly moved, down about 30c on the day.


WEEKLY PRICE MOVEMENT
The biggest forex move in this risk-on week was unsurprisingly USDJPY, leading to the biggest index gain on the NKY. Crypto assets rallied as well, and some FANGS well-outperformed NDX generally.
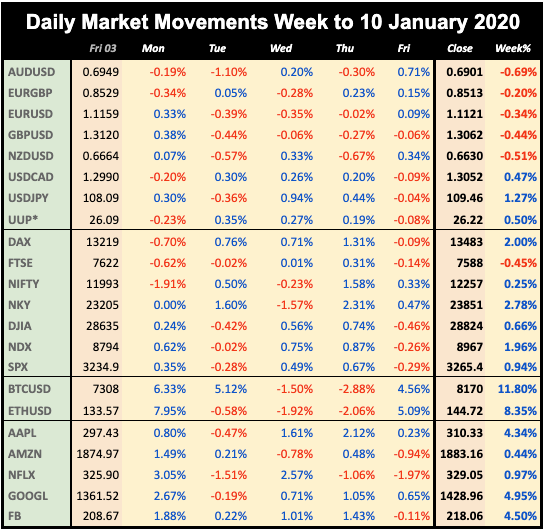


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.


NEXT WEEK (all times are GMT)
(Calendar High volatility items are in bold)

  • Earnings season begins
  • US, UK and Germany inflation
  • Phase 1 deal to be signed
  • Large Fed speaker roster


Monday January 13
Fed Rosengren (hawk) and Bostic (centrist) speak today, although both are non-voters. Boris Johnson’s Brexit deal, passed last Thursday in the UK’s lower house, goes to the upper House of Lords today, although the convention is that manifesto commitment bills are not challenged.

09:30 GBP UK GDP
15:30 CAD BoC Business Outlook Survey

Tuesday January 14
Earnings season opens today, with, as always the banks. Today JPM, C and WFC report before the bell. Fed Williams (dovish) and George (hawk) speak today. Only Williams has a vote.

07:00 CNY China Imports/Exports/TB
13:30 USD US CPI (MoM e0.2% p0.2%)
14:00 USD Fed's Williams speech


Wednesday January 15
The long awaited Phase 1 of the China trade deal is due to be signed today, although clearly, this is already priced in. More bank earnings today before the bell from BAC and GS, and also from DJIA component UNH. Fed Harker and Kaplan (voters) speak.

08:40 GBP BoE Saunders speech
09:30 GBP UK CPI (YoY e1.5% p1.5%)
10:00 EUR Eurozone Industrial Production
13:30 USD US PPI
16:00 USD US-China Phase One Trade Deal Signature
16:00 USD Fed Harker speech
18:00 EUR ECB Weidmann speech


Thursday January 16
A US Forex treasury report is expected today. All eyes will be on whether China is de-listed as a currency manipulator. Some smaller banks report before the bell. There are rate decisions on TRY and ZAR. US Retail Sales is the main release.

07:00 EUR Germany CPI (YoY e1.5% p1.5%)
09:30 GBP BoE Credit Conditions Survey (Q4)
12:30 EUR ECB MPC Minutes
13:30 USD US Retail Sales (Control Group MoM e0.4% p0.1%)
13:30 USD Philly Fed Manufacturing Survey
13:30 USD US Jobless Claims
15:00 USD Fed Bowman speech

Friday January 17
Fed Harker speaks again today, and there are more small bank earnings. There is a rate decision on KRW
02:00 CNY China GDP (YoY e6% p6%)
02:00 CNY China Retail Sales
09:30 GBP UK Retail Sales
10:00 EUR Eurozone CPI
13:30 USD US Building Permits/Housing Starts
14:00 USD Fed Harker speech
14:15 USD US Industrial Production (MoM) (Dec)
15:00 USD US Michigan CSI (e99.4 p99.3)
17:45 USD Fed Bowman speech


This report is published every week as an email by MatrixTrade.com - you can sign up to receive it here. This blog is supported solely by advertising, so if any of the ads interest you, please click on them. If you want notification when the blog is updated, please follow me on Twitter, Facebook, Stocktwits, TradingView or Linkedin (all open in separate windows). Details of how I compile the report are here.

Sunday, 5 January 2020

Week to Jan 3rd


New Year Week, China Good News, Iran Assassination

Mon Dec 30
After a strong rally for weeks, markets took a breather today, possibly banking year-end profits, as there was no specific news to cause the 0.70% pullback. The move was reflected in Gold and Bonds and JPY, all of which were up. The move was not as strong in other currencies, but all gained against the dollar. Oil was down in line with equity mood. With many markets closed thin trading may have exacerbated the moves.


Tuesday December 31
It was a quiet ending to the day, month, year and decade, with stocks quiet at first, and then making a strong rally into the close to erase yesterday’s losses and then some. Only FTSE failed to go green, following a strong 1.14% rally in GBP. The dollar continued to pull back and Gold and all major currencies advanced. Bonds were down in line with the equity move, but Oil fell again. This short day was all about positioning for end-of-year reporting, rather than any actual news moves.


Wednesday January 01
Markets were closed everywhere, although forex trades, which are not done on exchanges, continued , although as you would expect, volume and therefore volatility was very thin. A move up of 0.22% in CAD was the most any major made.


Thursday January 02
The China Phase 1 deal was augmented today by positive comments from China about it, and further negotiations made during the trading session. Coupled with some New Year positioning, carrying on the ramp on Tuesday afternoon meant all indices were up. Notably however, Gold, JPY and Bonds were also up, an indicator of possible things to come. The move in JPY was only 0.03% on another nearly flat forex day, where only CAD moved more than 0.1%. Oil was also down in a sign that the rally was fragile and done on low volume. It should be noted that four out of five manufacturing PMI reports today missed, only Germany beat estimates.


Friday January 03
The overnight US targeted strike on a top Iranian commander sent Asian and then European and US markets into a tailspin. As you might expect with anything Middle Eastern, oil soared in price, as did Gold, JPY and bonds. Otherwise the dollar was down across the board. A strong risk-off day, as you would expect.


WEEKLY PRICE MOVEMENT
The biggest index move on this quiet week was DAX, down 0.88%, and the strongest currency move was NZDJPY, down 1.77%. ETH made up some of the ground from last week, whereas BTC once again was flat. FANGs slightly outperformed NDX, in particular AAPL, which briefly touched $300 for the first time.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on DXY. The equity and index prices are now based on the cash close each day.


NEXT WEEK (all times are GMT)
(Calendar High volatility items are in bold)
  • Non-Farm Payrolls
  • Services PMIs
  • Various CB speakers
  • First full week of new decade

Monday January 6
Back to work for many traders, and volumes should increase with plenty of data this week. Last week was Manufacturing PMIs which were generally poor, and this week it is Services. Unusually, ECB Lane and BoC Wilkins speak over the weekend, but markets will generally be guided by the next step in the latest US-Iran bellicosity.
01:45 CNY China Caixin Services PMI (Dec)
07:00 EUR Germany Retail Sales (MoM) (Nov)
08:55 EUR Germany Markit PMI Composite (Dec)
09:00 EUR Eurozone Markit PMI Composite (Dec)
09:30 GBP UK Markit Services PMI (Dec)
14:45 USD US Markit Services PMI (Dec)
14:45 USD US Markit PMI Composite (Dec)


Tuesday January 7
The ISM Services PMI is important today, following the miss in the Manufacturing print last week. Otherwise Eurozone inflation is the key release. 

10:00 EUR Eurozone Prelim CPI (Core YoY e1.3% p1.3%)
13:30 USD US Trade Balance (Nov)
13:30 CAD Canada International Merchandise Trade (Nov)
15:00 USD US ISM Non-Manufacturing PMI (Dec) (e54.5 p53.9)
15:00 CAD Canada Ivey Purchasing Managers Index
15:30 NZD NZ GDT Milk Index (time approx)


Wednesday January 8
A quiet day on the news front as markets get back to normal. The ADP ‘preview’ of Friday’s jobs report has a similar estimate. There are rate decisions on PLN and RON.

07:00 EUR Germany Factory Orders s.a. (MoM) (Nov)
10:00 EUR Eurozone Business Climate (Dec)
10:30 EUR Germany 10Y Bond Auction (time approx)
13:15 USD US ADP Employment Change (Dec) (e150k p67k)


Thursday January 9
Chinese inflation will definitely set the tone on this busy day, and we have our first Fed speakers of 2020. There is a rate decision on ILS

00:30 AUD Aus Imports/Exports/TB
01:30 CNY China CPI (p4.5%)
07:00 EUR Germany Trade Balance s.a. (Nov)
07:00 EUR Germany Industrial Production s.a. (MoM) (Nov)
10:00 EUR Eurozone Unemployment Rate (Nov)
13:00 USD Fed Clarida speech
13:15 CAD Canada Housing Starts s.a (YoY) (Dec)
13:30 USD US Jobless Claims
16:30 USD Fed Williams speech
19:00 CAD BoC Governor Poloz speech
19:10 EUR German Buba President Weidmann speech


Friday January 10
The first jobs print of 2020, and the estimate is climbing back to the 180-200k mean. Canada reports simultaneously so the scope for a big USDCAD move is there, especially if it first moved strongly on Thursday’s BoC speech.

00:30 AUD Retail Sales s.a. (MoM) (Nov)
13:30 USD US NFP/AHE/UnEmp (NFP e160k p266k)
13:30 CAD Canada NFP/AHE/UnEmp (NFP e20k p-71.2k)


This report is published every week as an email by MatrixTrade.com - you can sign up to receive it here. This blog is supported solely by advertising, so if any of the ads interest you, please click on them. If you want notification when the blog is updated, please follow me on Twitter, Facebook, Stocktwits, TradingView or Linkedin (all open in separate windows). Details of how I compile the report are here.

Sunday, 21 July 2019

Week to July 19th


Mixed earnings week, Fed dovishness and rebuttal, Oil ignores usual triggers


Mon Jul 15
The Chinese GDP printed in line with expectations, and so offered no direction to the markets in early trading. C opened earnings season with a modest beat. Both C and the US markets in general were flat, although all three US indices still posted marginal new all-time highs.

USD was up (DXY+0.21%), which allowed the non-US indices to post gains (as their denominated currencies fell)), in particular FTSE, reacting to GBP fading 0.5% on Brexit no-deal concerns in the run up to the Prime Ministerial change. AUD and NZD were outliers, up 0.27% and 0.43% respectively. Gold was flat, and Oil and yields faded slightly in line with the dollar.

Tuesday July 16
JPM, JNJ and GS all beat earnings and revenue forecasts. However the market is a record highs, so this was priced in. Against this, the Retail Sales beat at 1230 was viewed as possibly giving the Fed room to delay or reduce rate cuts. US equities drifted downwards and DXY added 0.47%. Gold, Oil, all currencies and bonds (inverse to yields) were down in line, and once again DAX and FTSE posted green candles on account of the currency moves.

Wednesday July 17
The downward trend accelerated today with SPX’s worst day in three weeks, down 0.65% after an earnings and guidance miss from rail operator CSX (it dropped over 10%) which is part of DJT, and traditionally is supposed to lead DJIA. Also President Trump dampened hopes of an early deal with China. All other indices and Oil (transport-linked) fell, the latter despite the EIA stock beat at 1430. NFLX reported reduced growth after the close and also fell 10% after hours.

The dollar also pulled back (DXY -0.20%) with all currencies rising. Yields were down on both the weaker dollar and stock-bond rotation.

Thursday July 18
As always, interest rate policy trumps everything, even earnings. Today Fed Williams said that “it’s better to take preventative measures than to wait for disaster to unfold”, and Vice-Chair Clarida echoed similar sentiments to Fox News. This was enough to fully restore Wednesday’s pullback in equities, (helped by the strong Philly Manufacturing Survey at 1230 which printed 21.8 vs est 5.0) and had an equally strong effect on DXY, coming off 0.52%. in short order. All currencies and Gold moved down, as did yields of course.

Oil was strange, falling despite the equity ramp, the falling dollar and news of an Iranian drone being shot down by the US, all normally factors which would make it rise. This may be to do with the August contract expiry next Monday.

Friday July 19
Today Iran seized a British tanker in the Gulf, but more importantly, the NY Fed (where Williams is President) issued a very unusual press release saying his speech was “not about potential policy actions at the upcoming meeting”.  SPX, the dollar (DXY -0.41%) did a straight reversal of Thursday’s moves, as did yields to a lesser extent. Equities were not helped by the Michigan CSI miss at 1400. There are no more Fed speeches before the rate decision. Other equity markets followed, except FTSE which managed to close flat (as did Oil, despite Iran). 


WEEKLY PRICE MOVEMENT
The worst week since May saw NDX move the most, influenced of course by the massive 15% fade in NFLX.  NZD was the strongest for a second week, with GBPNZD falling 1.59%. Cryptos pulled back fairly strongly.


Note we use Google Finance data for daily movements, listing UUP as a proxy for DXY. All references to ‘the dollar’ are based on UUP. The equity and index prices are now based on the cash close each day.


NEXT WEEK (all times are GMT)
(Calendar High volatility items are in bold)
  • Big week in earnings
  • How dovish will the ECB be?
  • New British Prime Minister
  • Fed Blackout period starts

Monday July 22
There may be some reaction to the Japanese election at weekend. We are now in the ‘blackout’ period for Fed announcements before the crucial rate decision on the 31st. We may also see the completion of the USTR on $300Bn of Chinese imports.

12:30 USD Chicago Fed National Activity Index 
15:00 JPY BoJ Governor Kuroda speech
22:30 AUD RBA Kent speech

Tuesday July 23
The British ruling Conservative party announce their new Prime Minister today, which can only be Boris Johnson. Sterling is of course at multi-year lows already, so any surprises from the new PM can only be to the upside. Lots of earnings action as four DJIA companies report There is a rate decision on HUF. Markets are closed in Egypt and Oman.

08:00 EUR ECB Bank Lending Survey
08:30 GBP BoE FPC Meeting Minutes
10:55 KO, UTX, TRV Earnings 
12:15 GBP BoE Haldane speech
13:00 USD US Housing Prices/Existing Home Sales
20:05 V Earnings
20:30 WTI API Oil Stock
22:45 NZD NZ Imports/Exports/TB

Wednesday July 24
The tone of the day will probably be set by BA earnings before the bell. The largest component of DJIA has of course been hit by the 737 Max problems. NDX giant FB reports after the bell.

An interesting one at that time is troubled German bank DB, who report after a wholesale restructuring last week. Their stock is currently valued at 20% of balance sheet (although note that most banks have P/B<1, eg BARC 39%, RBS 57%, SAN.ES 57%, LLOY.L 77% even the mighty GS 86% and C 91%).

The important German Manufacturing PMI is expected to recover. Failure to do so will surely hurt DAX. Today is also the first deadline for results of Mexico’s compliance with US illegal border crossing suppression demands. Markets are closed in Venezuela.

07:30 EUR Germany Markit PMIs (Manuf e45.1 p45.0)
08:00 EUR Eurozone Markit PMIs (Composite e52.0 p52.2)
11:30 BA, CAT Earnings
13:45 USD US Markit PMIs
14:00 USD US New Home Sales
14:30 WTI EIA Oil Stock
20:05 FB Earnings
20:15 TSLA, PYPL Earnings

Thursday July 25
A big day with ECB expected to outline further TRLTO (QE 2) moves. The EUR risk is therefore to the upside (ie if Draghi surprises and doesn’t mention them). Earnings continue with MMM and DOW before the bell (together 5.6% of DJIA), and more importantly the AMZN and GOOGL reports after the bell (the four companies listed are 22.3% of NDX). There is also a rate decision in Turkey. Markets are closed in Costa Rica and Tunisia.

03:05 AUD RBA Governor Lowe speech
08:00 EUR Germany IFO Business Sentiment
10:30 MMM,DOW Earnings
11:45 EUR ECB Rate Decision/Statement (e0% hold)
12:30 USD US Jobless Claims
12:30 EUR ECB President Draghi Presser
12:30 USD US Durable/Capital Goods (CG Jun e0.1% p0.5%)
20:00 AMZN, GOOGL, INTC Earnings
20:05 SBUX Earnings
23:30 JPY Tokyo CPI (Core Jul e0.8% p0.5%)

Friday July 26
DJIA stalwart MCD (5.37% of the index) reports before the bell, followed shortly by the important first preliminary print of US Q2 GDP, severely cut back from the Q1 figure. There are rate decisions on RUB and COP.

12:00 MCD Earnings
12:30 USD US Prelim 19Q2 GDP (e1.9% p3.1%)
12:30 USD US PCE QoQ

This report is published every week as an email by MatrixTrade.com - you can sign up to receive it here. This blog is supported solely by advertising, so if any of the ads interest you, please click on them. If you want notification when the blog is updated, please follow me on Twitter, Facebook, Stocktwits, TradingView or Linkedin (all open in separate windows). Details of how I compile the report are here.


Saturday, 10 November 2018

Week to Nov 9th


Monday November 05
The mood was mixed in Monday, as the November upturn resumed to give SPX a 0.6% lift, but NDX turned down, still weighed by AAPL, after reports that production levels were static. The worlds largest company fell 2.84% in addition to its 6.7% drop on Friday. Italian yields rose again as Rome continued to defy Brussels on their budget, so it was no surprise that DAX was down, as was FTSE after the UK Market Services PMI miss at 09:30, and NKY finished flat on a slightly weaker yen.

Oil was particularly interesting. As the US reimposed Iranian sanctions there was a huge move in the Brent/WTI spread. Iranian Oil is priced in BNO and we saw a rare day where BNO rose 0.5% and WTI dropped 0.6%

DXY continued last week’s downtrend, and gave up 0.3%, with EUR, GBP and AUD all advancing. CAD was pulled back by WTI, and JPY and Gold continued their downward trend in line with the SPX gain. Yields were down 1bp in line with the weaker dollar.

Tuesday November 06
Markets diverged today with SPX, NDX and NKY firmly up as the mid-term vote took place, but a different story in Europe. Continued Italian budget concerns resulted BTP yields climbing 8bp, which pushed DAX into the red. Beats on the German, Spanish and Eurozone PMIs had no effect. FTSE was also down, but this was more a reaction to a notably stronger pound (up 0.4%), as nothing went wrong with Brexit today!

DXY had a virtually flat day (down 0.07%), with the GBP gain and a slight uptick in EUR balanced by a fade in JPY (and Gold) in line with the rising SPX. Notably VIX did not drop, suggesting some traders were hedging their bets on the election result. WTI continued to move down, losing 1.45% today, and CAD was down in line. Yields were up 2bp as the new paper auction at 18:00 sold at 3.209% yield.

Wednesday November 07
Markets love certainty, and they also loved the fact that no Democratic protest vote emerged. The midterms came in precisely as expected, and markets rose, with a clear risk-on sentiment. SPX added 2.1%, (riskier) NDX 2.7%, and VIX fell 17.8%. XLV outperformed on the belief that a gridlocked Congress would be unable to legislate way their profits, ie drug price controls.

DXY fell sharply on the results, at one point down 0.61% although it clawed back to close 0.10% down, again anticipating reduced legislation. Gold and JPY were of course down as stocks rose. EUR had a wild day but ended flat. GBP and commodity (risk on) currencies AUD and CAD were up, the latter despite a further fall in Oil after the EIA miss (5.78M vs 2.43M best) at 15:30

This was the seventh red day for Oil, the first time that has happened since January 2016. The fall is also because the US government has issued waivers to many countries to allow them to buy Iranian oil. Remember, like the dollar, the President has continually commented that he wants the Oil price lower. Yields had fallen as well in early trading, but tracked the dollar recovery and ended 1bp up. 

Thursday November 08
It was FOMC business as usual on Thursday, with the gradual rate hike path (and therefore resistance of White House pressure) confirmed again. This helped USD and depressed stocks, which took a breather after Wednesday’s strong performance, and SPX pulled back 0.3%. NDX was only down 0.61%. NKY, DAX and FTSE also registered small losses. 

DXY was up 0.46%, its best day for two weeks, and 0.31% of this came after the FOMC announcement. All currencies were down. Gold and bond prices (inverse to yields) were also down in line. Oil finished the day at 60.75, which is 20.98% from its Oct 3 high if 75.71, and so is now in ‘bear territory’ defined as a drop of over 20%.

Friday November 09
The continuing fall in oil prices, and other commodities, for example copper fell 4.84% this week, its worst since August was bound to eventually affect equities, and SPX fell 0.9% today. NDX, DJIA, NKY and the Oil-heavy FTSE also fell, whereas the resource buying (not selling) DAX managed a modest gain. Oil actually managed to stay flat, but closed the week under $60, the first time since February.

The dollar continued to react to the hawkish Fed, as it often does the day afterwards. DXY added 0.28%, and all currencies and Gold evenly moved down against it. Yields however turned down 4bp, as equity money rotated into bonds.

Please note all figures and percentages given for daily movement on indices cover the entire cash and futures period in that day.


WEEKLY PRICE MOVEMENT

DXY added 0.42% this week, despite being down 0.85% at one point. The only currency that outperformed the greenback was NZD, after months in the doldrums. With CAD being depressed by Oil, buying NZDCAD would have been this week’s best forex trade, netting 2.39%. SPX benefited from the midterms and was the top index this week (DJIA did even better at 2.88%. NDX underperformed and as you can see FAANG performance was mixed. Once crazy in price swings, BTC and ETH continued for another week to show even less volatility than traditional instruments.

AUDUSD 0.7228 (+0.07%)
EURGBP 0.8737 (-0.41%)
EURUSD 1.1337 (-0.46%)
GBPUSD 1.2975 (-0.05%)
NZDUSD 0.6744 (+1.31%)
USDCAD 1.3213 (+0.70%)
USDJPY 113.83 (+0.55%)
DAX     11532 (-0.19%)
FTSE     7130 (+0.24%)
NIFTY   10585 (+0.30%)
NKY     22194 (+0.58%)
SPX    2776.0 (+2.09%)
GOLD  1209.27 (-1.93%)
OIL     59.75 (-4.86%)
BTCUSD   6416 (-0.17%)
ETHUSD 210.57 (+4.13%)
FB     144.96 (-3.58%)
AAPL   204.47 (-1.45%)
AMZN  1712.43 (+2.82%)
NFLX   303.47 (-1.82%)
GOOGL 1077.02 (+0.52%)

(Crypto prices are given as at 0000GMT Saturday, after the other markets close.)

NEXT WEEK (all times are GMT)
(Calendar High volatility items are in bold). 

Monday November 12
It is Veterans Day in the US and Canada. Markets are not closed, but volume may be reduced, as also there are no release of note in either Europe or the US. Colombia markets are closed. Riksbank Sep Gov Flodén speaks at 1100 (SEK is 4.2% of DXY).

02:15 CNY China Foreign Direct Investment (YTD)(YoY)

Tuesday November 13
Today is the deadline for Italy’s response to the rejection of its budget by the EU. Expect further defiance, and thus EU retaliation. Any pragmatism on Italy’s part would be unexpected and be positive for EUR and BTP prices.

07:00 EUR Germany CPI
09:30 GBP Average Earnings/Unemployment/Claimant Change
10:00 EUR Germany ZEW Economic Sentiment/Current Situation
19:00 USD US Monthly Budget Statement
23:30 AUD Australian Westpac Consumer Confidence
23:50 JPY Japan GDP

Wednesday November 14
Today is the main release day of the week with inflation reports from both the UK and the US. Inflation is of course one of the Fed’s dual mandate items (the other being jobs), and unofficially, it is in the UK as well, so expect GBPUSD volatility. Although earnings season is largely over, IT giant CSCO, seventh-largest NDX component (2.7%) reports after the bell. Fed Quarles gives House Testimony at 1400. Fed Chair Powell and Fed Kaplan speak at 2305. There are rate decisions in Thailand and Israel.

00:00 EUR EcoFin Meeting (all day)
01:30 AUD Wage Price Index (QoQ)
02:00 CNY China Retail Sales/Industrial Production
07:00 EUR Germany GDP
09:30 GBP UK CPI (Core CPI prev 1.9%)
10:00 EUR Eurozone GDP (est 1.7% prev 1.7%)
10:00 EUR Eurozone Industrial Production s.a. (MoM)
13:30 USD US CPI (Core YoY est 2.2% prev 2.2%)
15:30 WTI EIA Stock

Thursday November 15
DJIA straggler WMT (2.7% of the index) reports before the bell today, and troubled giant NVDA (make of crypto-mining hardware, and 12th largest component of NDX at 1.7%) reports afterwards. Fed Quarles speaks again at 1500, and Fed uber-dove Kashkari is on at 2000. There is a rate decision in Mexico, and markets are closed in Brazil. 

00:30 AUD Australia NFP/Unemp/Participation (prev 5.6k)
01:00 AUD Australia Consumer Inflation Expectation
09:30 GBP UK Retail Sales (Control Group est 0.4% prev 0.1%)
13:30 USD Philadelphia Fed Manufacturing Survey
21:30 NZD Business NZ PMI

Friday November 16
A quiet day to finish the week. As we have said before, Eurozone CPI rarely moves EUR, as it rarely surprises as the individual 27 countries have already reported. Fed Evans speaks at 1630.

10:00 EUR Eurozone CPI
14:15 USD Industrial Production/Capacity Utilization
18:00 WTI Baker Hughes Rig Count

This report is published every week as an email by MatrixTrade.com - you can sign up to receive it here.


Saturday, 12 May 2018

Week to May 11th


Monday May 07
The week opened quietly, with SPX making modest gains. After dropping 200 points in the Asian session, NKY ended the entire day flat, and DAX and FTSE advanced as their denominated currencies declined. USD continued up, with DXY adding 0.21% to close at a new 2018 high, and all currencies and Gold were down against it. Oil was up in line, also benefiting from US-Iran sanctions talk, and breaking through the $70 level. US 10-year Treasury Bond yields were flat at 2.95%. TRY fell again, down 0.9%

Tuesday May 08
An even flatter day in US, Japanese and UK equities belied stirrings in Europe where the Italian MIB was down 2.4% at one point due to the failure of Italian coalition talks, and the  possibility of another election. DAX managed a slight (0.1%) gain on the back of further Euro losses. USD had another good day, advancing against all currencies except JPY, as President Trump confirmed the reimposition of Iran sanctions, and the yen benefited from its safe haven status. Gold was also flat, probably for a similar reason. Yields followed the dollar upwards, and EM currencies fell again. DIS beat on earnings and revenue after the bell and briefly spiked $2 before falling back.

Wednesday May 09
After the Iran decision, a rally in energy stocks pushed SPX up 1% today, and the energy-heavy FTSE 1.6%. DAX followed suit to an extent, up 0.31%, but energy importer Japan’s NKY only managed to end flat on the day. The dollar took a breather, with a flat DXY. This represented a flat EUR, gains on GBP, AUD and CAD, but a 70 pip move down for JPY as risk-on returned. Gold fell in line with JPY.

Oil was further up in line with the energy rally ending 3% higher at $71.16. There was a 10-year Treasury bill auction today, and although the auction only made a maximum of 2.995%, trading did push through the 3% barrier to end at 3.01% on the day. 

Thursday May 10
Despite mixed Jobless Claims results, and a miss on the important US CPI print at 12:30, US markets still had a strong day, as SPX put on 20 handles (0.76%), and NDX did even better, up 0.92%, with AAPL making a new ATH. DAX, FTSE and NKY were up in line, despite their denominated currencies rising.

The CPI print inevitably had an effect on the dollar, and DXY was down 0.39%, and most currencies and Gold were up. The exceptions were the two rate decisions, both holds. NZD dropped 77 points (1.11%) after the RBNZ decision, and GBP gave up 84 points (0.63%) after no change at the BoE. Although both currencies recovered somewhat, they still posted red candles for the day. Yields fell in line with USD, and ended back under 3%. Oil had a fairly quiet day, but held onto earlier gains in the week, and closed 0.4% up at $71.41. BKNG fell over 6%. Although the Q1 EPS was a beat, the forward guidance disappointed.

Friday May 11
The SPX energy-led rally continued on Friday, as did NKY, and the oil-rich FTSE. Healthcare stocks also rallied on Trump’s drug pricing proposals.The energy-free DAX did not join in and fell 0.2%. USD pulled back again, although the move was not uniform. USDCAD was up after the Canadian jobs miss at 12:30, and Gold was down in line with the equities rally. Oil also gave up some of its recent gains, but still closed above $70, the first weekly close at this level since November 2014. Yields were flat on the day despite the weaker dollar, at 2.97%

Please note all figures and percentages given for daily movement on indices cover the entire cash and futures period in that day.


WEEKLY PRICE MOVEMENT

The upward movement of the dollar we have seen recently was stalled this week. DXY was virtually flat (actually down 0.02%) with some currencies advancing and some receding. The best forex trade would have been to sell NZDCAD which moved down by 1.28%. SPX was the best-performing index.

The crypto-recovery of the last two weeks stalled, with substantial drops in Bitcoin and Ethereum, mainly on Thursday and Friday.

AUDUSD 0.7542 (+0.04%)
EURGBP 0.8813 (-0.29%)
EURUSD 1.1938 (-0.18%)
GBPUSD 1.3538 (+0.09%)
NZDUSD 0.6962 (-0.84%)
USDCAD 1.2791 (-0.44%)
USDJPY 109.36 (+0.28%)
DAX     12986 (+1.29%)
FTSE     7708 (+1.66%)
NIFTY   10806 (+1.77%)
NKY     22699 (+1.01%)
SPX    2728.9 (+2.44%)
GOLD  1318.83 (+0.31%)
OIL     70.44 (+1.00%)
BTCUSD   8422 (-13.69%)

ETHUSD 678.58 (-14.46%)

(Crypto prices are given as at 0000GMT Saturday, two hours after the other markets close.)


NEXT WEEK (all times are GMT)

Monday May 14
An huge roster of ECB speeches today: Mersch (10:00), Lautenschläger (10:15 and 15:00), Praet (11:45 and 17:15) and Coeure (17:45), added to the two Fed speakers Mester (06:45) and Bullard (13:40). Trade is back in focus with NAFTA talks continuing and Chinese Vice-Premier Liu visiting Washington. The Indian inflation print is at 12:00.

Tuesday May 15
A busy economic calendar today, especially for EUR. The British employment figures (the nearest the UK comes to an NFP) is the first major release since the rate hold decision, and average earnings growth is the key figure. US Retail Sales are less exciting as they are a CPI proxy, and we had that report last week. Fed speakers are Kaplan (12:00), and Williams (18:00), but of more interest are the Fed nominees Clarida and Bowman’s testimony at 14:00, particularly the latter, as we don’t know where she sits on the hawk-dove scale yet.

Wednesday May 16
German and Eurozone inflation are rarely much outside estimates and in any event do not move the markets much—unless of course there are big upsets. ECB President Draghi speaks at 12:00, but only a welcome address. Couere (12:30) and Praet (14:30) follow later in the day. In the EM world, Brazil, Poland and Thailand all have central bank rate decisions. Finally, NDX veteran CSCO reports after the bell.

Thursday May 17
The biggest economic event of the day comes in Asia, with Australia’s version of NFP. The estimate of 20k is mid-range.  Today is the NAFTA negotiations deadline set by US Speaker Ryan., and Chinese tech star BABA and DJIA heavyweight WMT report before the bell. ECB Constancio speaks at 10:30 and 12:00, and BoE Haldane is on at 16:00. The only Fed speaker is dove Kashkari at 14:45. Markets are closed in Norway.

Friday May 18
Canadian CPI is important, and beat or miss (as appropriate) could cause a sharp move. USDCAD is known to do that, especially if correcting an earlier move caused by the NAFTA outcomes. Three Fed speakers today: Mester at 07:00, Kaplan and Brainard (the dove turned centrist) at 13:15.


CALENDAR (all times are GMT). High volatility items are in bold

Mon May 14
06:45 USD FOMC Member Mester speech
23:10 AUD RBA Assist Gov Debelle Speech

Tue May 15
01:30 AUD RBA Meeting's Minutes
02:00 CNY Retail Sales/Industrial Production (YoY)
06:00 EUR Germany GDP
08:30 GBP UK Unemp/Claimant Count/Average Earnings
09:00 EUR Eurozone GDP
09:00 EUR Eurozone Industrial Production
09:00 EUR Germany ZEW Economic Sentiment/Current Situation
12:30 USD US Retail Sales
14:00 NZD GDT Milk Price Index (time approx)
20:30 WTI API Stock

Wed May 16
00:00 EUR Eurozone EcoFin Meeting (all day)
01:30 AUD Wage Price Index (QoQ)
07:00 EUR Eurozone Non-monetary policy's ECB meeting
06:00 EUR Germany CPI
09:00 EUR Eurozone CPI
12:30 USD US Housing Starts/Building Permits (MoM)
13:15 USD US Industrial Production/Capacity Utilization
14:30 WTI EIA Stock
22:45 NZD PPI
23:50 JPY Machinery Orders

Thu May 17
01:00 AUD Australia Consumer Inflation Expectation
01:30 AUD Australian Emp/UnEmp/Participation (NFP)
12:30 USD US Jobless Claims
12:30 USD Philadelphia Fed Manufacturing Survey
14:30 CAD BoC Review
23:30 JPY Japan National CPI

Fri May 18
12:30 CAD Canada Retail Sales
12:30 CAD Canada CPI
17:00 WTI Baker Hughes US Oil Rig Count

This report is published every week as an email by MatrixTrade.com - you can sign up to receive it here.